 Broker, not a lender
Hard Money Lenders inCypress, Texas
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Cypress investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Cypress deal right now
Prefilled with a realistic Cypress deal. Change any number and it reprices instantly on the lanes licensed in Texas, using the same engine behind our term sheets.
Financing a deal in Cypress
Cypress is one of the cleaner flip markets in the Houston area, and that is not a slogan, it is what the comps do. Homes move in roughly 48-50 days, a shade faster than the Houston single family average of about 52, and the higher end of the market carries a real premium: the median sale price in 77433 runs near 429 thousand against about 372 thousand in 77429. Buyers want to be here, which is the part that matters when you are underwriting an exit.
The reason there is steady flip supply out here is worth understanding, because it tells you where to look. A lot of these subdivisions were developed years ago and then simply held. Original owners stayed put, or the house passed down inside a family, and nothing was updated the whole time. Those properties are structurally sound and sitting in neighborhoods buyers actively want, they are just twenty or thirty years behind the finish level of the street. That is close to an ideal flip: the demand is already proven by the comps, and the work is bringing a dated house up to what the block already supports rather than betting on a neighborhood turning around.
What a Cypress deal looks like on paper
Cypress example: $220,000 purchase, $75,000 rehab, $400,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$33,000
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,620
- Title and closingTitle$3,630
- Prepaid interest (15 days)Lender$1,022
- Property insuranceInsurer$2,803
- AppraisalAppraiser$550
Interest while you rehab: $1,479 a month on the $187,000 funded at closing, $2,072 once every draw is out. Proof of funds is cash to close plus $18,750 of rehab reserve and $12,432 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Cypress
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 5-14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| First Flip, 10% Down1 | 10% | 680+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| Best Value | 5% | 590+ | First flip OK | 9.99% to 12.99% | 2% | 75% of ARV | 12 months | 5-14 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 680+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 3+ Flips3 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips4 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Lowest Down (100% financing) | 0% (100% financing) | 650+ | First flip OK | 11.50% | 3% | 70% of ARV | 12 months | 5-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Loans of $150,000 and up. Smaller loans are priced per file. Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Loans of $150,000 and up. Smaller loans are priced per file. Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What a real Cypress deal looked like
Bought at 220 thousand with a 75 thousand dollar rehab budget against a 400 thousand dollar after repair value. Total cost in at 295, which leaves real room between the finished number and what the work costs. That shape is typical of what actually funds in Cypress, and it is why the deals here tend to be clean: the spread is wide enough that a soft appraisal does not immediately wipe out the margin.
Where Cypress prices sit right now
Before we price a Cypress flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Our own pull of sold comps near the subject property, last 200 days: 36 sales, averaging 352,638 dollars and a median of 343,500. Average days on market came back at 48-49.
| Days on market, Cypress | 48-50 days |
| Days on market, Houston single family | about 52 days |
| Median sale price, 77433 | about $429,000 |
| Median sale price, 77429 | about $372,000 |
Sources: Houston Association of Realtors MLS reports · Texas A&M Real Estate Research Center, Houston Cypress South · Redfin, 77433 housing market
How a Cypress file actually gets priced
Cypress deals underwrite cleanly on the property and get held up by the paperwork around it. The housing stock is newer, so the scope is usually cosmetic to moderate and the inspection comes back short. What slows the file is the layer on top: municipal utility district disclosure, HOA transfer and resale certificates, and in the master-planned sections an architectural review that has to sign off before any exterior work starts.
MUD tax rates are the line investors forget. Cypress sits across a patchwork of municipal utility districts, and the rate difference between two neighboring districts can move a buyer monthly payment by a couple hundred dollars. That changes who can qualify for your finished house. Pull the MUD rate off the tax record during diligence and work it into your resale assumption, not just your carry.
Who buys your finished Cypress deal
The Cypress exit is a retail buyer using conventional financing, which means the appraisal has to support your number a second time on the way out. Because purchase prices start higher here than in Houston proper, your margin is a smaller percentage of a bigger number, and a twenty thousand dollar miss on the ARV eats a larger share of the profit than the same miss on a two hundred thousand dollar Houston flip.
What a Cypress deal looks like
| On our closed Cypress deals | Range |
|---|---|
| Purchase price | $220,000 to $230,000 |
| After repair value | $360,000 to $430,000 |
| Most common loan type | Fix & Flip |
The range we actually see on Cypress deals, as of September 2026. Bring us something outside it and we will still price it, the range is what is common here, not a cap.
Your whole loan, in one portal
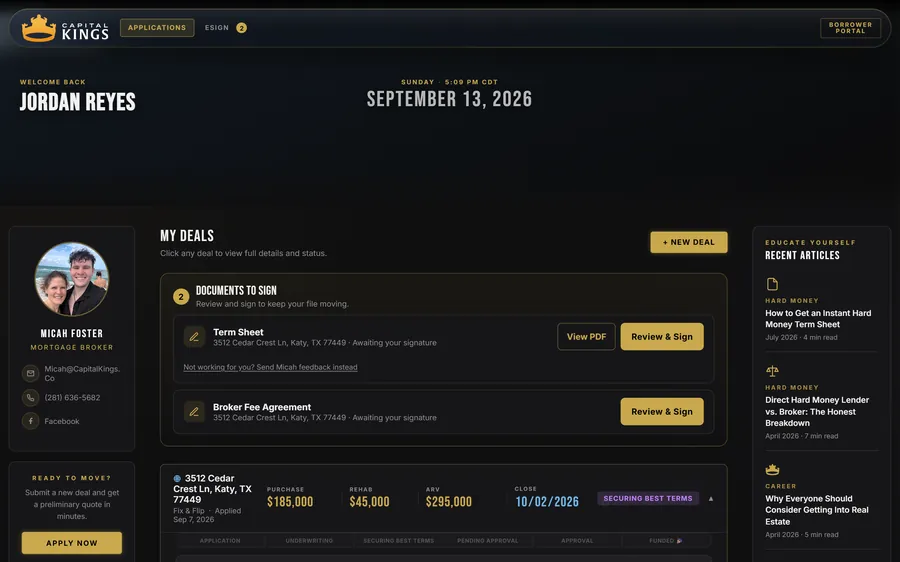
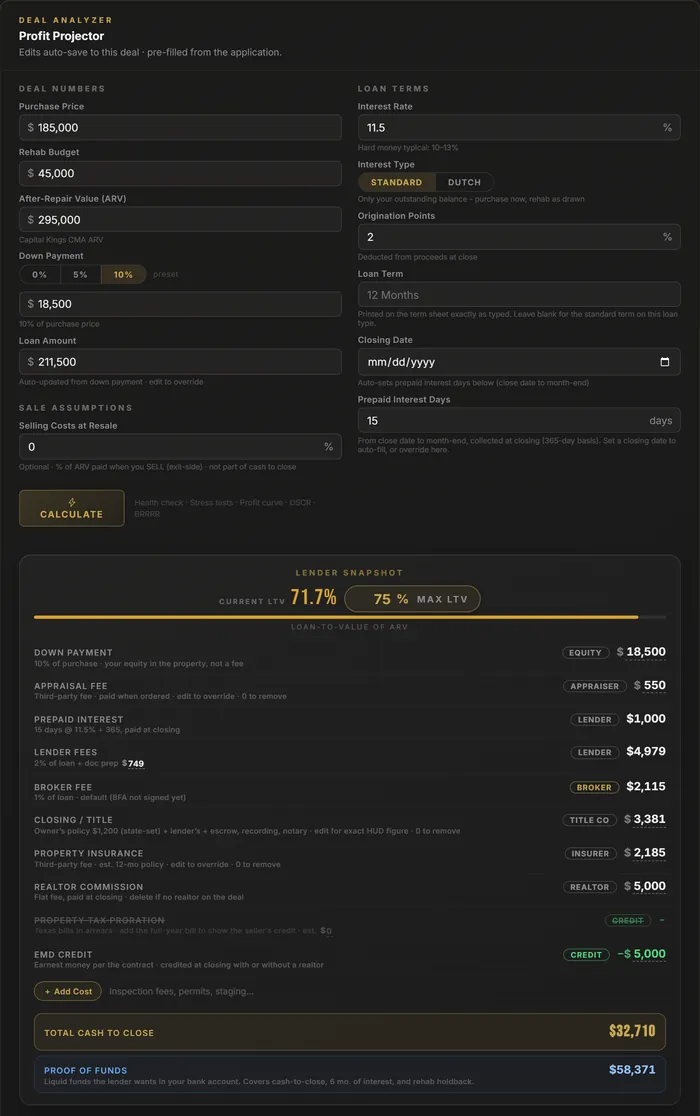
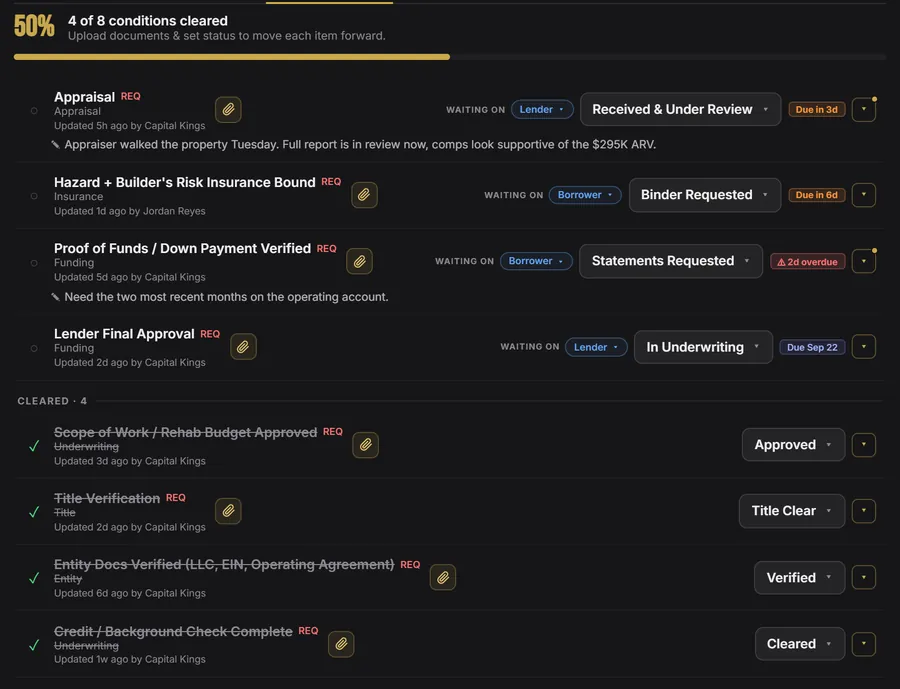
Apply once and the whole Cypress loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Cypress
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Cypress.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Cypress
We broker deals across the whole Cypress market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Texas, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Cypress hard money FAQ
Do you lend hard money in Cypress?
Which fix and flip programs apply in Cypress?
How fast can a Cypress hard money loan close?
How much do I need to bring to close on a Cypress flip?
Do you fund the rehab budget in Cypress?
What credit score do I need for a Cypress fix and flip loan?
Can I refinance a Cypress flip into a rental loan?
How do MUD districts affect a Cypress flip?
Will an HOA hold up my Cypress rehab?
Before you sign anything
Ready to fund your Cypress deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.