 Broker, not a lender
Hard Money Lenders inHouston, Texas
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Houston investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Houston deal right now
Prefilled with a realistic Houston deal. Change any number and it reprices instantly on the lanes licensed in Texas, using the same engine behind our term sheets.
Financing a deal in Houston
Houston is the deepest fix and flip market in Texas, and it is where most of our loan volume lives. It is a big, uneven market: a 1950s ranch in Oak Forest and a flood-damaged bungalow in the East End are priced by completely different logic, and lenders who do not work here regularly get the ARV wrong in both directions.
Two things decide most Houston deals. First, flood history: anything in a 100-year floodplain or with a prior claim changes both your insurance line and your buyer pool, and some lenders will not touch it at all. Second, the unrestricted-lot problem. Houston has no zoning, so a comp two streets over can sit next to a commercial use and appraise nothing like your subject. We price both of those in before we shop the file, because a lender surprise on either one is what kills a Houston closing at day 12.
What a Houston deal looks like on paper
Houston example: $155,000 purchase, $50,000 rehab, $282,500 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$23,250
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,234
- Prepaid interest (15 days)Lender$709
- Property insuranceInsurer$1,948
- AppraisalAppraiser$550
Interest while you rehab: $1,042 a month on the $131,750 funded at closing, $1,437 once every draw is out. Proof of funds is cash to close plus $13,500 of rehab reserve and $8,624 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Houston
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 5-14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| First Flip, 10% Down1 | 10% | 680+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| Best Value | 5% | 590+ | First flip OK | 9.99% to 12.99% | 2% | 75% of ARV | 12 months | 5-14 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 680+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 3+ Flips3 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips4 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Lowest Down (100% financing) | 0% (100% financing) | 650+ | First flip OK | 11.50% | 3% | 70% of ARV | 12 months | 5-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Loans of $150,000 and up. Smaller loans are priced per file. Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Loans of $150,000 and up. Smaller loans are priced per file. Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
How a Houston file actually gets priced
The Houston file that gets repriced late is almost always an ARV problem, not a credit problem. Because the city has no zoning, an appraiser can pull a comp from two streets over that backs onto a commercial lot, and the number lands under what your own comps supported. We set the ARV against finished sales inside the same pocket rather than a half-mile radius, and if the number you sent us is not going to hold, you hear it before the term sheet goes out.
Flood is the Houston underwriting question. A property in a 100-year floodplain, or one with a prior claim on record, changes your insurance line, narrows your resale buyer pool, and takes some lenders off the table entirely. Pull the flood zone before you go under contract rather than after. Buyers here ask, and an unresolved answer costs you weeks on the exit.
Who buys your finished Houston deal
Most Houston exits we see are retail resales in the 250-400 thousand band, which is where the buyer pool is deepest and where financing is easiest for whoever buys from you. Above about 500 thousand, days on market stretch and your carry assumption needs a longer runway. Below about 150 thousand the buyer is often another investor paying cash, so your price matters more than your finish level.
What a Houston deal looks like
| On our closed Houston deals | Median |
|---|---|
| Purchase price | $155,000 |
| After repair value | $282,500 |
| Spread between the two | $127,500 |
| Most common loan type | Fix & Flip |
Typical of the Houston deals we place, as of September 2026. Your deal will not be the median, but this is the shape of what actually funds here.
Your whole loan, in one portal
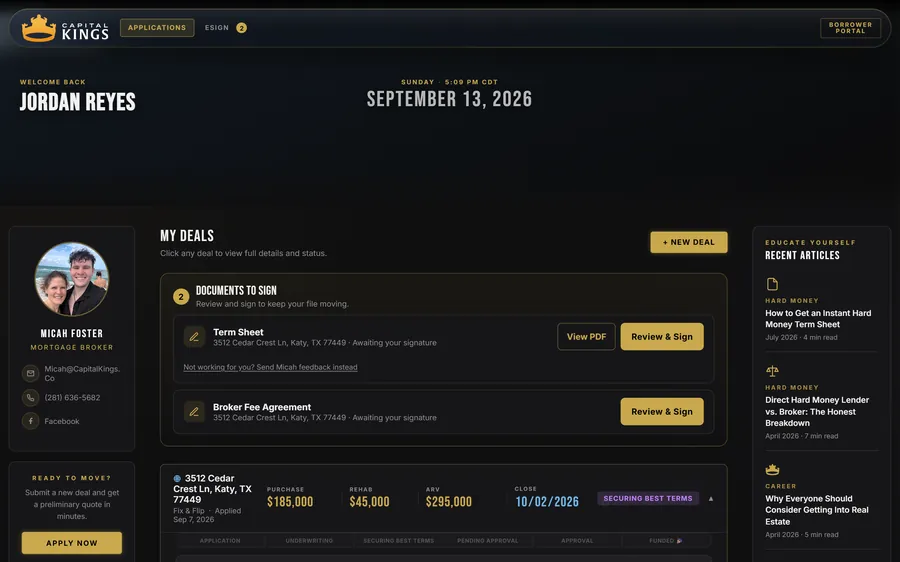
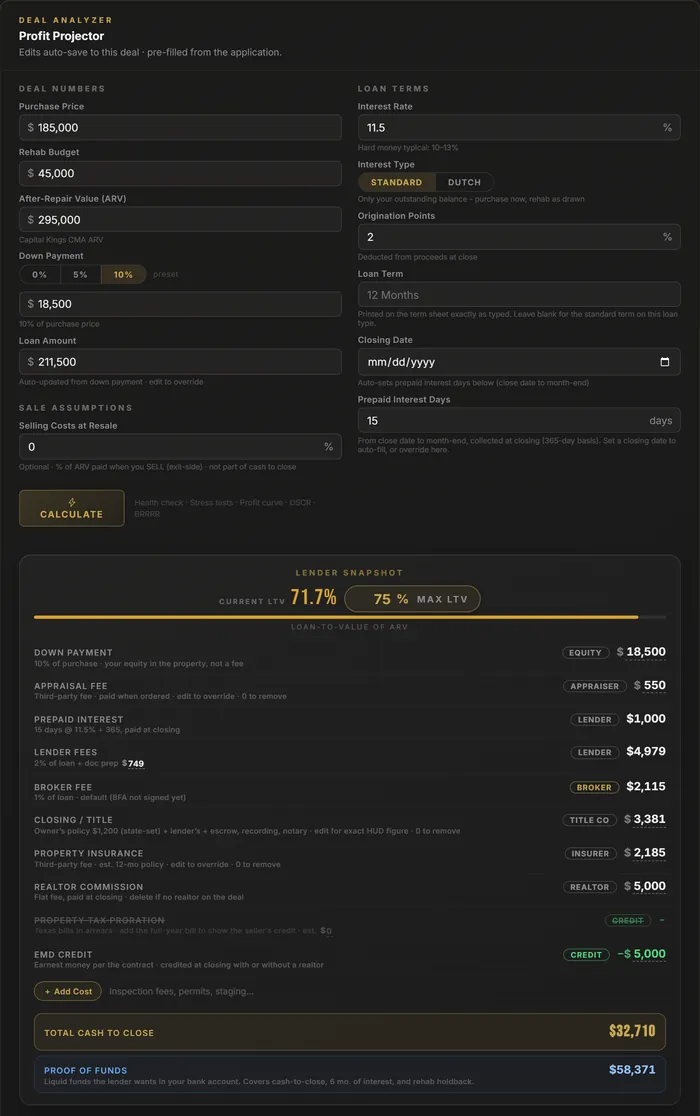
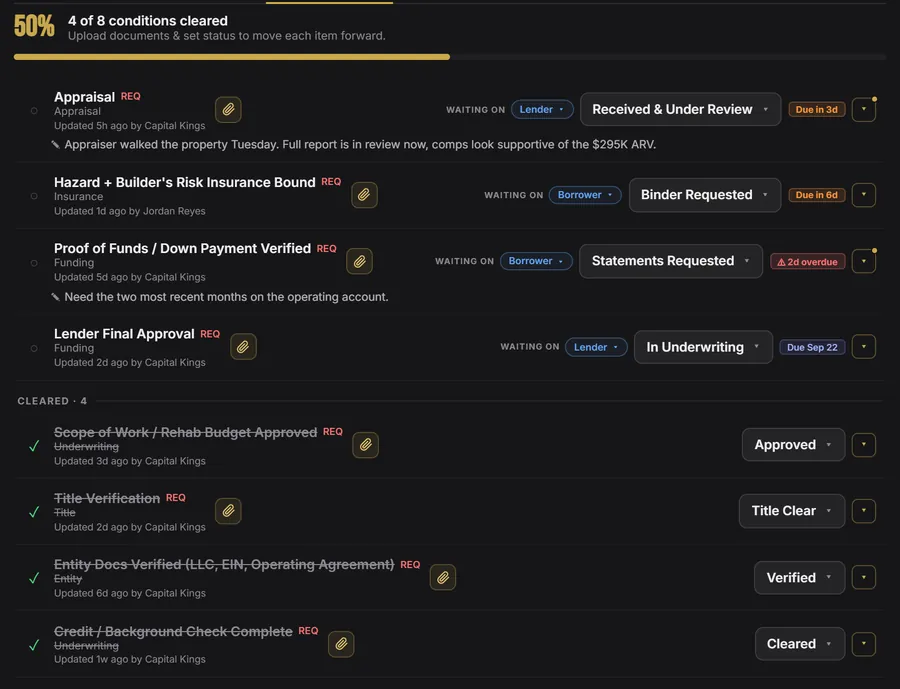
Apply once and the whole Houston loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Houston
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Houston.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Houston
We broker deals across the whole Houston market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Texas, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Houston hard money FAQ
Do you lend hard money in Houston?
Which fix and flip programs apply in Houston?
How fast can a Houston hard money loan close?
How much do I need to bring to close on a Houston flip?
Do you fund the rehab budget in Houston?
What credit score do I need for a Houston fix and flip loan?
Can I refinance a Houston flip into a rental loan?
Does flood zone affect a Houston hard money loan?
Can I get a hard money loan on a Houston property with no zoning protection?
Before you sign anything
Ready to fund your Houston deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.