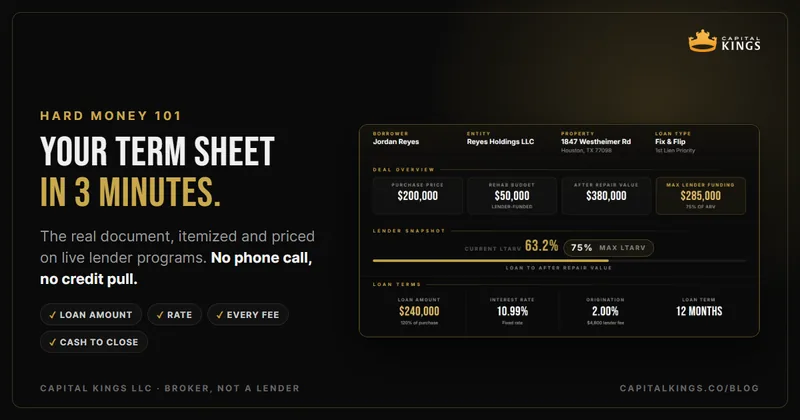
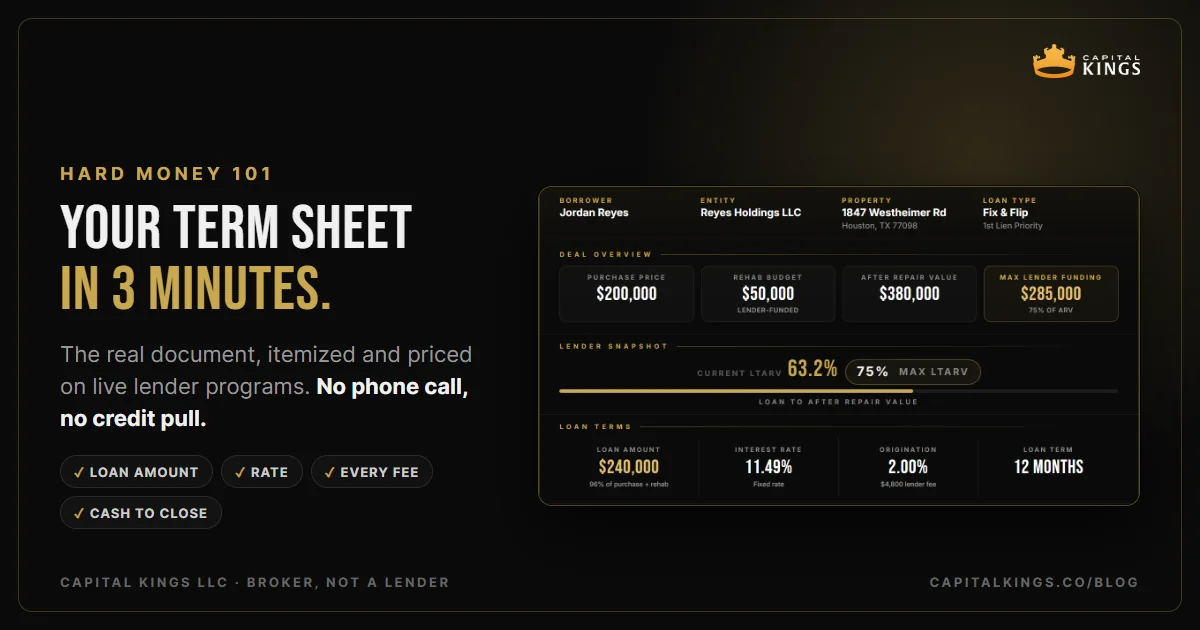
- You can build a real, itemized fix and flip term sheet in about 3 minutes, with no phone call and no credit pull.
- It shows your loan amount, rate, every fee, your cash to close, and the proof of funds a lender will want to see.
- It's a preliminary estimate built on real lender pricing. It isn't a binding commitment, and your final terms still depend on the appraisal and a review of your file.
When you're chasing a deal, the money is usually the slowest part. You find a property, the clock starts, and you still don't know what your loan looks like or how much cash you'll need to bring. Most lenders want a phone call first, and then you wait a day or two just for a ballpark. The instant term sheet skips that wait. You type in your deal, and about three minutes later you've got an itemized document priced against real lender programs, before you've talked to anyone.
What the Term Sheet Shows You
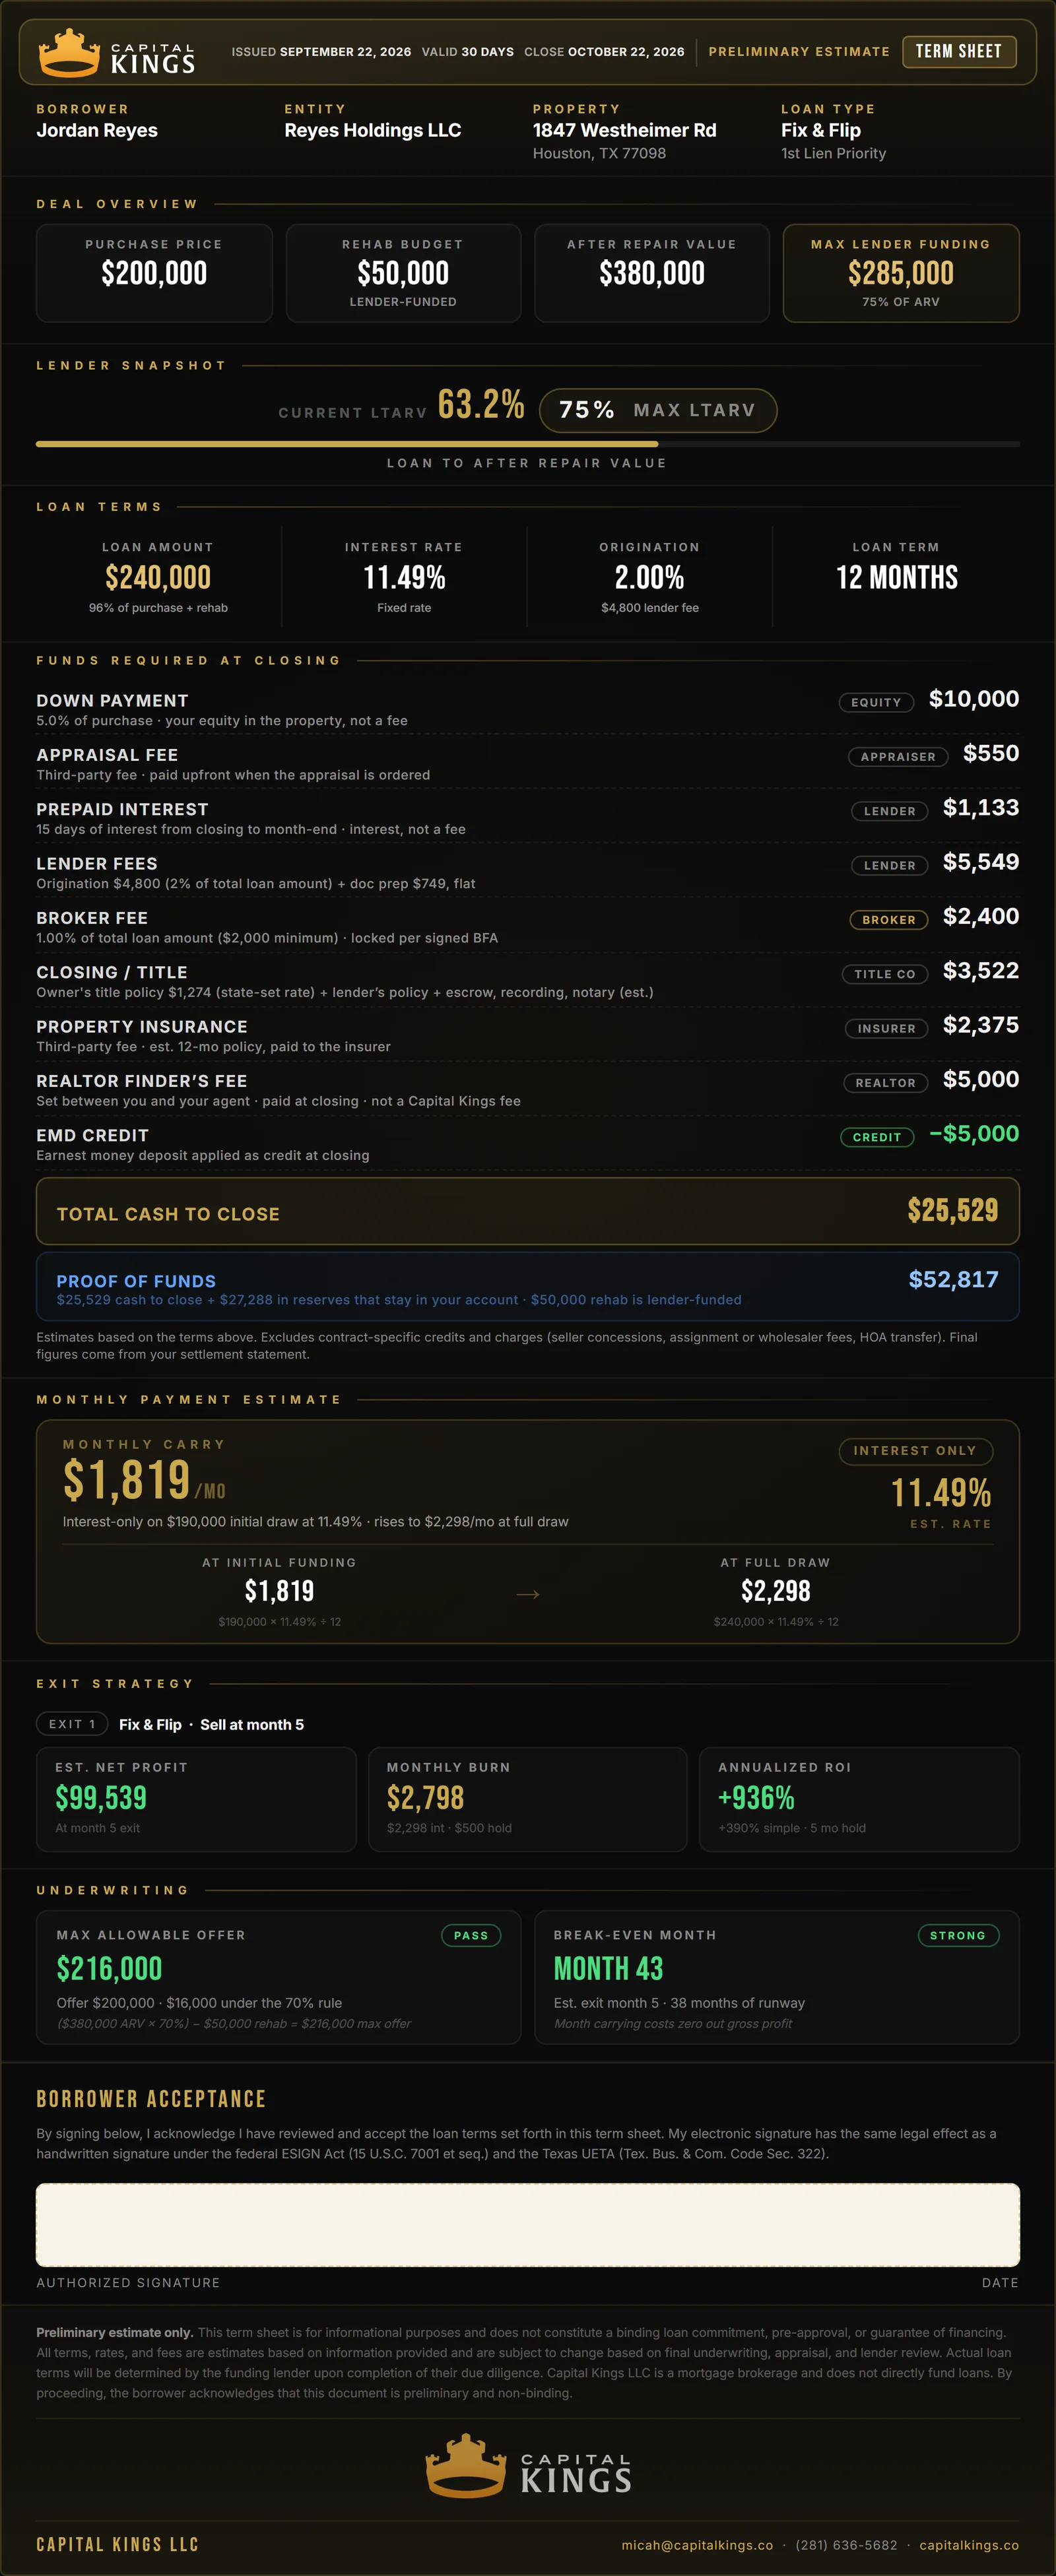
What you get back is a full term sheet with your name and your property on it. Here's what it shows:
- Your loan amount and how it's built: a percentage of the purchase price plus your rehab budget
- The interest rate and loan term
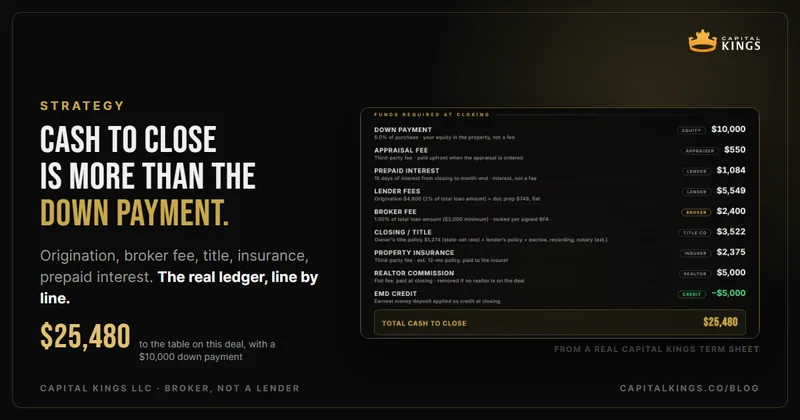
- Your down payment and every fee, each on its own line: origination, broker fee, title and closing
- Your cash to close, the actual number you wire at the closing table
- The proof of funds a lender will want to see in your account
- Your estimated monthly payment, both when the loan first funds and at full draw, once all your rehab money has been released
Does It Cost Anything, or Touch My Credit?
No, and no. It's free, and there's no credit pull. When the tool asks about your credit score, you're just telling it your range so it can match you to the right program. Whether you're sitting at an 800 or still rebuilding, I've got lenders for that. Nothing gets run, and nothing hits your report.
Just know going in that this is a preliminary estimate, not a loan commitment. It uses real lender pricing, so the numbers are honest, but the final number can still move. I'll get to why near the end.
What to Have Ready
You don't need much. Before you start, just have a rough idea of:
- The property address and purchase price
- Your rehab budget
- Your after repair value (ARV) estimate, meaning what the property sells for once it's fixed up
- Roughly how much cash you've got to work with
- Your credit range and how many deals you've done
Don't have exact numbers yet? Estimate them. Running your deal math first helps, but you can change any of it later.
How to Get Yours in About 3 Minutes
Before you apply, you can test a deal right here. The mini term sheet below is the same one on our homepage. Drag a slider, or click any number and type your own, and everything underneath updates as you go.
The 90%, 95% and 100% buttons set how much of the purchase price the loan covers, and the rest is your down payment. The LTV bar compares your loan to the ARV. Once the loan would pass 75% of the ARV (70% at 100% financing), it gets capped there and your down payment goes up to cover the difference. The 95% and 100% options are the major Texas metro programs; outside Texas, a first flip starts at 10% down.
 Mini Term Sheet
Capital Kings LLC
Live
Nothing you type here gets saved. These numbers price a first deal at 700-759 credit on our Texas programs, where 95% and 100% of the purchase are available in the major metros. Other states price on their state page. When you apply, the full term sheet adds your rate, loan term and monthly payment, priced for your own credit and experience.
When you're ready for the full sheet you can save and download, here's how to get it:
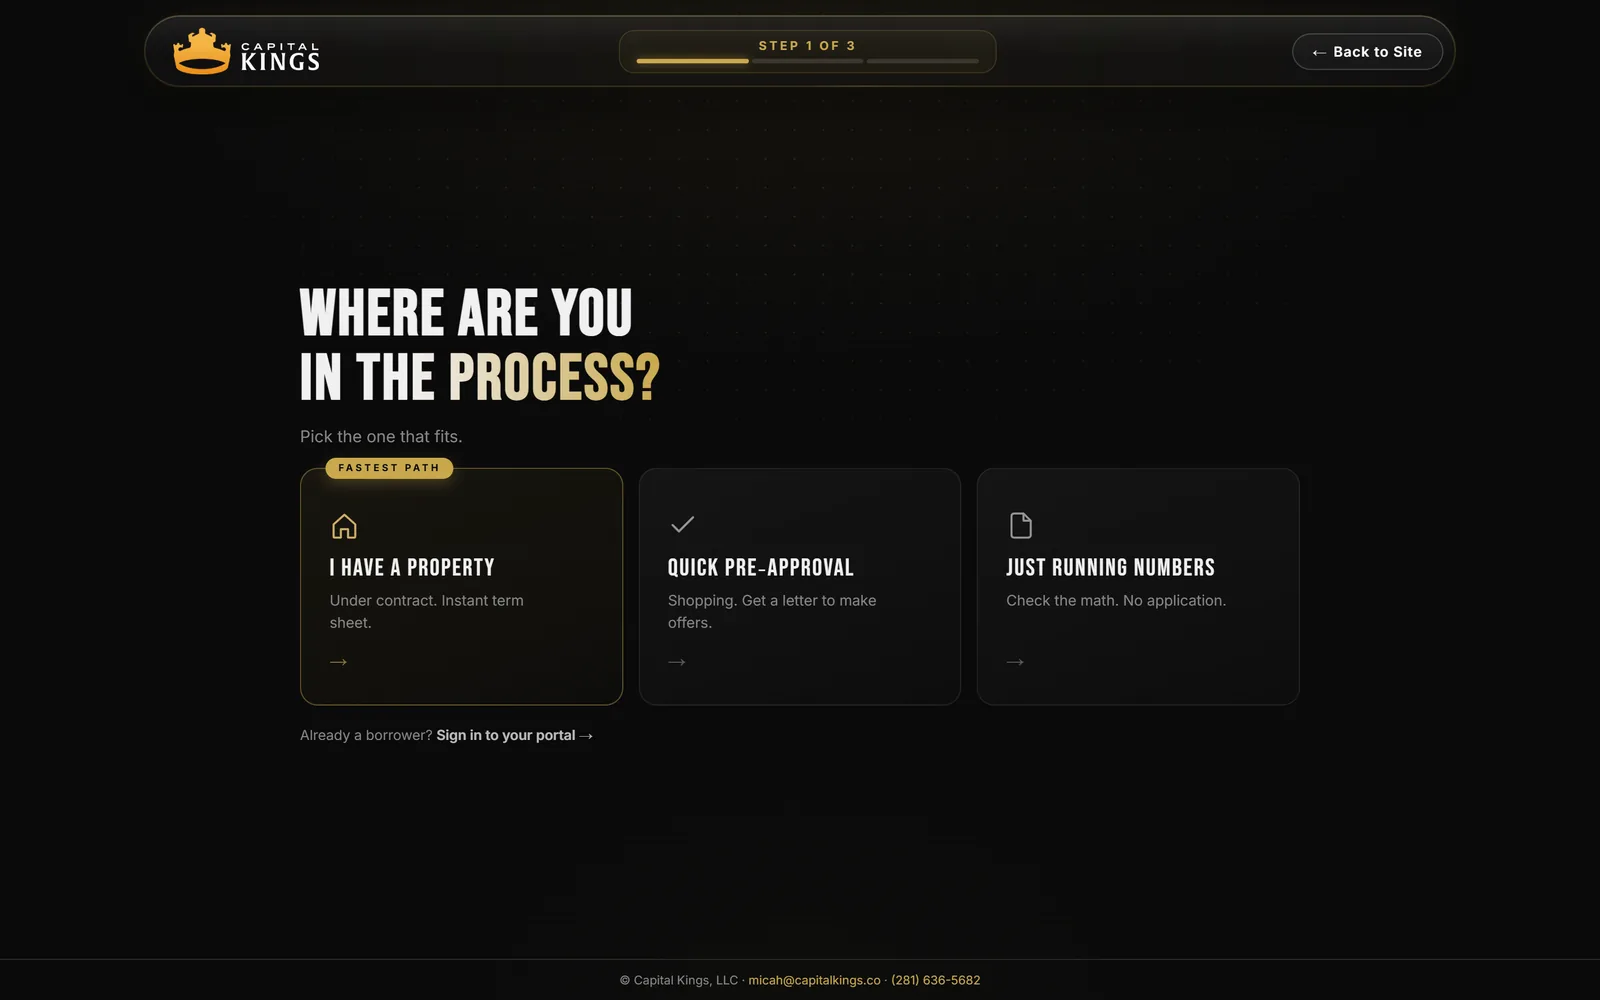
Start the application and pick "I have a property"
Head to the apply page. If you've already got a property under contract or picked out, choose the first path. If you're still shopping, the "Quick Pre-Approval" path gets you a letter you can make offers with.
Drop in your deal numbers
Property address, purchase price, rehab budget, and your ARV estimate. It's the same info you'd give any lender.
Choose your deal structure
After you enter your credit range and experience, you'll see a set of programs, each priced live for you. Less down keeps more cash in your pocket, and more down usually gets you a lower rate. Whichever one you pick is exactly what your term sheet will show, so you don't end up with a one-size-fits-all quote.
Get your term sheet
It's ready as soon as you finish. You can view it or download the PDF, and a copy saves to your borrower portal for whenever you need it.
Common Questions
Is an instant term sheet a real loan offer?
Will getting a term sheet run my credit?
How accurate is the instant term sheet?
What do I need to get a hard money term sheet?
Do I have to talk to anyone to get one?
Not sure a deal pencils out? Build the term sheet first, and then we can go over the numbers together. It won't cost you anything, and you'll know where you stand.