 Capital Kings LLC
Only 5% down onTexas fix and flips.
The lender funds 95% of the purchase and 100% of the rehab on one loan. In any Texas metro area (MSA), bring as little as 5% of the purchase price. The rehab comes back to you in draws, up to 75% of the after repair value. Your term sheet lists every fee and who it goes to.
- No credit pull
- Every fee on the sheet
- 400+ lender network
- First flips welcome
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Mini Term SheetCapital Kings LLCLiveOne Houston flip, four ways
A $160,000 Houston purchase with a $48,000 rehab and a $300,000 after repair value, 700 credit, first flip. The same deal on all four structures a 700 borrower can pick, priced by the term sheet the application generates.
| Structure | Down payment | Loan | Rate | Cash to close | Proof of funds |
|---|---|---|---|---|---|
| 0% down, 100% financingLeast cash0% down · 3% origination · 6 months · fits under the 70% capProof of funds $45,314 | $0 | $210,000 | 11.5% | $13,814 | $45,314 |
| 5% down5% down · 2% origination · 12 monthsProof of funds $47,563 | $8,000 | $200,000 | 11.74% | $21,423 | $47,563 |
| 12.5% down12.5% down · 1% origination · 12 monthsProof of funds $54,666 | $20,000 | $188,000 | 9.75% | $31,101 | $54,666 |
| 15% down, Best RateLowest rate15% down · 0.5% origination · 12 monthsProof of funds $59,421 | $24,000 | $184,000 | 9.49% | $36,290 | $59,421 |
100% financing is capped at 70% of the after repair value. On this deal it fits: 70% of $300,000 is $210,000 and purchase plus rehab is $208,000, so you bring $0 down on the purchase, the lender rolls $2,000 of the closing costs into the loan up to the cap, and you bring $13,814 at closing for the rest. 5% down asks for $7,609 more cash but about $2,391 less in fees, at a rate 0.24% higher, 11.74% against 11.5%.
$9,678 more cash at closing than 5% down buys 9.75% instead of 11.74%, about $429 a month less interest once the rehab is drawn. Every figure includes the $5,000 realtor finder’s fee line and the $5,000 earnest money credit, which offset on this deal.
The real term sheet for this flip, four ways
The same $160,000 Houston flip with a $48,000 rehab and a $300,000 after repair value, 700 credit, first deal, on the four programs a 700 borrower can pick. Every fee is on the sheet, and every line says who gets paid: your equity, the lender, the title company, the insurer, the appraiser, the realtor, or the broker.
- Down paymentEquity$0
- Appraisal feeAppraiser$550
- Prepaid interestLender$766
- Lender fees, origination and doc prepLender$7,049
- Broker feeBroker$2,100
- Closing / titleTitle co$3,373
- Property insuranceInsurer$1,976
- Realtor finder’s feeRealtor$5,000
- Earnest money creditCredit−$5,000
Fits under the 70% cap: $208,000 of purchase plus rehab against a $210,000 cap, so $0 down on the purchase, the lender rolls $2,000 of the closing costs into the loan (a $210,000 loan, all the room the cap leaves) and the $13,814 you bring is the rest of the closing costs. The gold broker line is the only money Capital Kings earns. The $5,000 realtor line is the agent’s own finder’s fee, paid by you and set between you and your agent, and comes off if nobody brought the deal, and the earnest money you already deposited comes back as the credit under it. Proof of funds is the cash to close plus $31,500, 15% of the $210,000 loan, in reserves that stay in your account (the lender verifies 15% to 20% of the loan; a 401(k) counts at half its vested balance).
- Down paymentEquity$8,000
- Appraisal feeAppraiser$550
- Prepaid interestLender$733
- Lender fees, origination and doc prepLender$4,840
- Broker feeBroker$2,000
- Closing / titleTitle co$3,324
- Property insuranceInsurer$1,976
- Realtor finder’s feeRealtor$5,000
- Earnest money creditCredit−$5,000
$8,000 down and $7,609 more cash to close than 0% down, for $13,423 in fees instead of $15,814 at 11.74% against 11.50%. The smaller loan also runs about $56 a month less interest once the rehab is drawn. 5% down also lends up to 75% of the after repair value, so it has more room if the appraisal comes in light. Proof of funds adds $14,400 of the rehab and $11,740 of interest that stay in your account.
- Down paymentEquity$20,000
- Appraisal feeAppraiser$550
- Prepaid interestLender$561
- Lender fees, origination and doc prepLender$2,749
- Broker feeBroker$2,000
- Closing / titleTitle co$3,265
- Property insuranceInsurer$1,976
- Realtor finder’s feeRealtor$5,000
- Earnest money creditCredit−$5,000
$9,678 more cash to close than 5% down buys 9.75% instead of 11.74% and $2,000 of origination instead of $4,000, about $429 a month less interest once the rehab is drawn. Needs 700+ credit; after 4 completed flips the down payment drops to 10%.
- Down paymentEquity$24,000
- Appraisal feeAppraiser$550
- Prepaid interestLender$530
- Lender fees, origination and doc prepLender$3,989
- Broker feeBroker$2,000
- Closing / titleTitle co$3,245
- Property insuranceInsurer$1,976
- Realtor finder’s feeRealtor$5,000
- Earnest money creditCredit−$5,000
$14,867 more cash to close than 5% down for 9.49% at 0.5% origination, $2,000 minimum. At 760+ credit, or 730+ with 10 completed flips, Best Rate drops to 8.99%.
These are sample sheets for a made-up borrower, built by the same engine that builds yours. Yours takes about five minutes and doesn’t pull your credit.
Five ways to structure a Texas flip
| Program | Down | Rate | Origination | Credit | ARV cap | Term |
|---|---|---|---|---|---|---|
| 5% Down | 5% | 9.99% to 12.99% | 2% | 590+ | 75% | 12 months |
| 10% to 12.5% Down | 10% at 740+ credit; 12.5% below it, 10% after 4 flips | 9.75% | 1% | 700+ | 75% | 12 months |
| Best Rate | 15% | 8.99% to 9.49% | 0.5% | 700+ | 70% | 12 months |
| 100% Financing | 0% | 11.5% | 3% | Any (11.5% at 650+) | 70% | 6 months, closing costs rolled in under the cap |
| Fastest Close | 10% | 11.99% | 2% | Any | 75% | 6 months, closes in as little as 72 hours |
Origination has a $2,000 minimum on every program, the broker fee is 1% with a $2,000 minimum and a $10,000 maximum, and the rehab is funded in draws on all five. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network, and we shop every flip against the whole network before it’s signed. 100% financing has its own page, with a Houston example scenario that fits under the 70% cap: 100% financing in Texas. Renovating to hold? Refinance into a DSCR rental loan once it’s rented. Brought the deal through a realtor or wholesaler? Their finder’s fee goes on the same sheet (how the partner program works).
What 5% down actually prices at
5% Down prices on two things: your credit and how many flips you have finished. A first flip at 700 or higher credit prices at 11.74% with 2% origination. Completed flips lower it: to 9.99% at 760+ credit after one completed flip, and to 10.74% at 700-759 after 10 or more completed flips.
| 5% Down rate by credit | First flip | 1-3 completed | 4-10 completed | 10+ completed |
|---|---|---|---|---|
| 760+ credit | 11.74% | 9.99% | 9.99% | 9.99% |
| 700-759 credit | 11.74% | 11.49% | 11.24% | 10.74% |
| 660-699 credit | 12.74% | 11.99% | 11.74% | 11.49% |
| 590-659 credit | 12.99% | 12.49% | 12.24% | 11.99% |
- 5% of the purchase, not the project. The rehab is funded on top, so on a $160,000 house with a $48,000 rehab the down payment is $8,000.
- The deal has to fit under 75% of ARV. 95% of the purchase plus the rehab has to land under 75% of the after repair value, or the difference comes out of your pocket. Run it before you write the offer.
- Texas title is priced by the state. Owner’s and lender’s policy premiums are promulgated, so the term sheet prices title from your contract and loan amount instead of guessing a percentage.
- Business purpose only. Investment property you plan to renovate and sell, not a home you plan to live in.
Price your flip right now
Prefilled with the example above. Change any number and it reprices on the same math the application’s term sheet uses.
Sizing your flip on the same terms as the application. Get the real term sheet →
Your first flip, on 5% down
Most people planning a first flip assume they need 20% down and a track record before a lender will fund the renovation. On the 5% Down program you need neither. The loan is sized on the deal: 95% of the purchase plus 100% of the rehab, up to 75% of what the house is worth when it’s done. You bring the 5%, the closing costs and proof of funds, and completed flips lower the rate from there. 5% Down is for properties inside a Texas metro area (MSA).
590 opens the 5% Down program. 100% financing has no credit minimum (11.5% at 650 and up), and 700 adds 10% to 12.5% Down at 9.75% and the Best Rate program.
The down payment, closing costs, and proof of funds for part of the rehab and six months of interest. The real numbers are on the term sheet above.
95% of the purchase plus the rehab has to land under 75% of the after repair value. Run it before you write the offer.
A first flip at 700+ credit prices at 11.74%. Completed flips lower the rate, to 9.99% at 760+ credit and 10.74% at 700-759.
Four mistakes first-time flippers make
- Putting 5% down on a deal that doesn’t fit. If 95% of the purchase plus the rehab is more than 75% of the after repair value, the loan is capped and the gap is cash you bring. Run the cap before you write the offer.
- Budgeting the down payment and forgetting proof of funds. Lenders verify part of the rehab budget and six months of interest on top of cash to close. On this example that’s $26,140 more in the bank.
- Handing the lender a lump-sum rehab budget. Draws are released line by line after inspection. An itemized scope of work gets approved faster and funds faster.
- Putting a 12-month project on a 6-month loan. Fastest Close runs 6 months. Contractors run late and houses sit, so if the timeline is tight, take a 12-month program.
What happens after you apply?
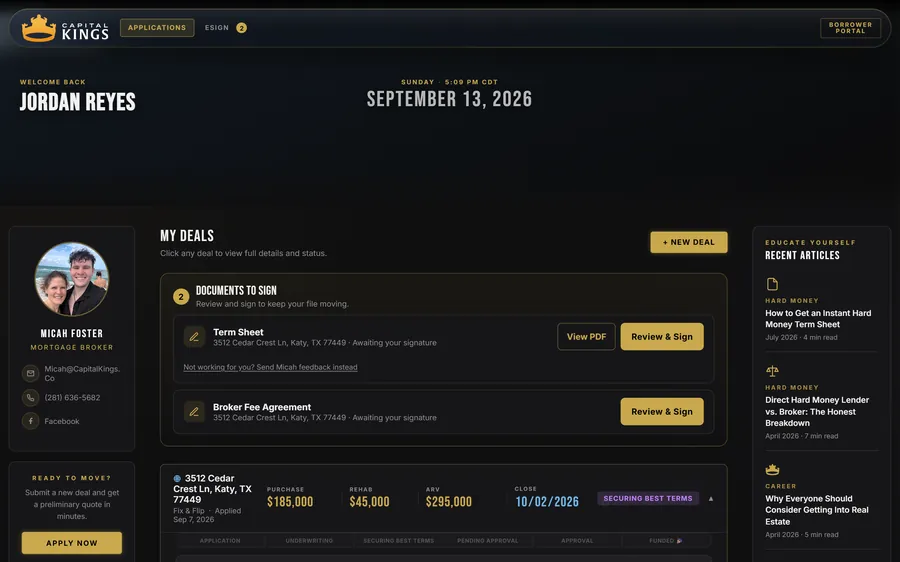
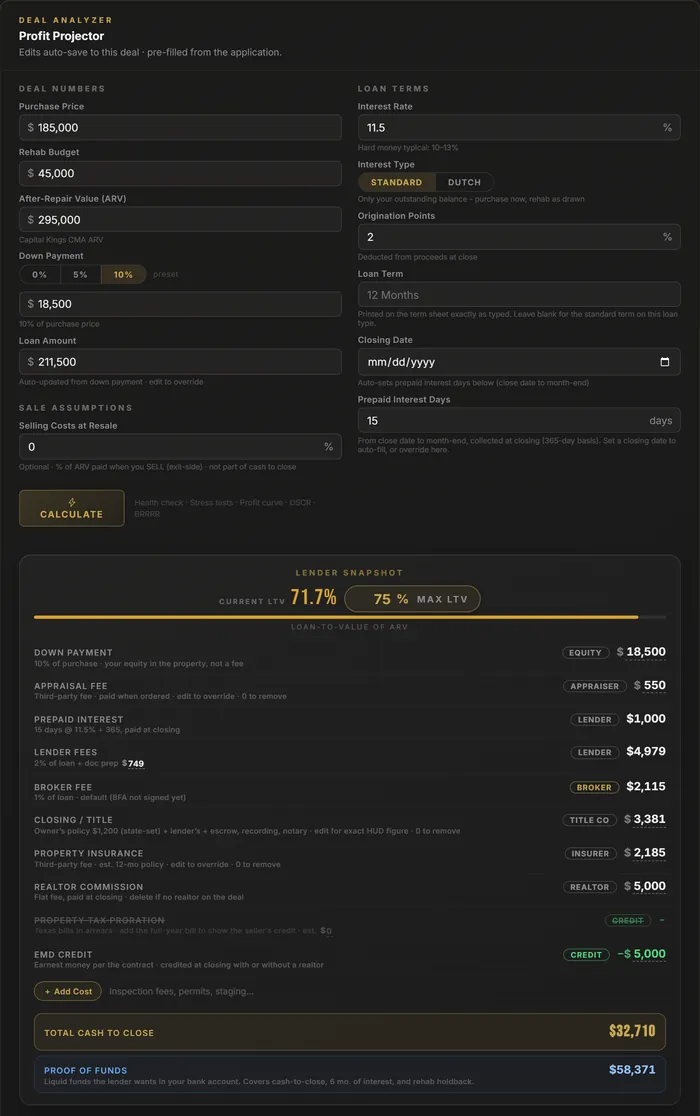
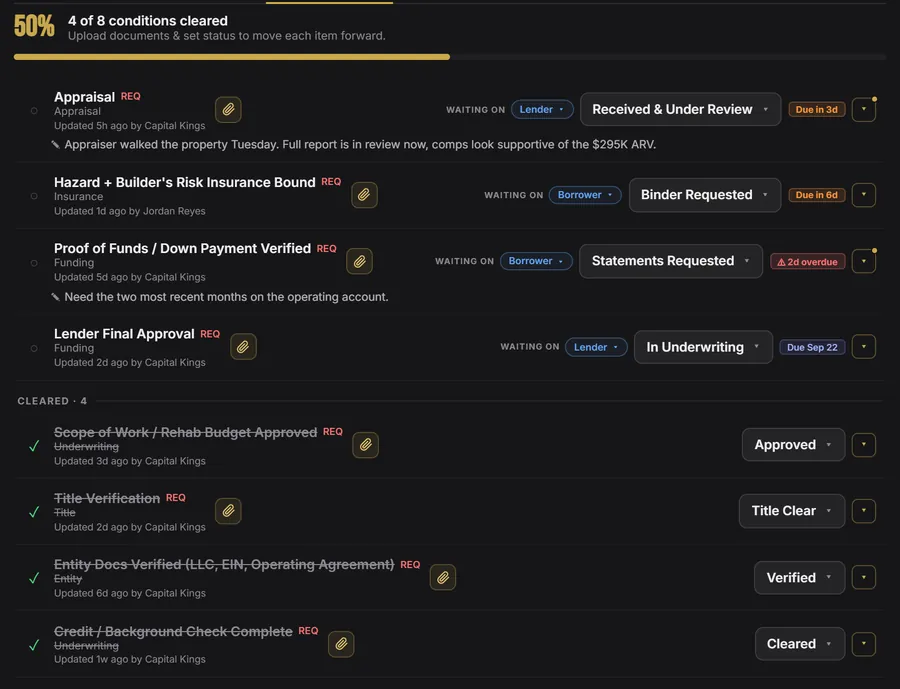
Apply once and the whole loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on.
How is a flip loan sized?
$160,000 −$8,000 +$48,000 =$200,000 loan
Purchase, minus 5% down, plus 100% of the rehab, under 75% of the $300,000 after repair value ($225,000).
You bring $21,423 at closing: the $8,000 down payment plus $13,423 of closing costs, and show $47,563 in the bank as proof of funds. No tax returns, W-2s or pay stubs.
The cap is 75% of the after repair value, or 70% on 100% financing, where proof of funds is your cash to close plus 15% of the loan. The rehab money isn’t wired at closing: the lender holds it and releases it in draws as each phase is inspected. Interest-only, 12 months on every program but Fastest Close.
What documents does the lender need?
- Purchase contract and the property address.
- Itemized scope of work and rehab budget, line by line, not a lump sum.
- LLC certificate of formation, EIN letter and operating agreement if you close in an entity.
- Government ID.
- Two months of bank statements showing cash to close and reserves.
- Insurance quote or binder.
- Settlement statements from completed flips, if you have them. They lower the rate.
Not on the list: tax returns, W-2s or pay stubs.
Which loan does your deal need?
Buying without a rehab to finance? See purchase-only loans in Texas, or read purchase-only vs fix and flip loans.
Where do flips pencil in Texas?
A flip loan works wherever the finished house resells for enough to cover the purchase, the rehab and the carry: the older neighborhoods of Houston, the Dallas-Fort Worth suburbs, San Antonio and the Austin metro. The number to run first is the 75% ARV cap. On a $300,000 after repair value the loan tops out at $225,000, so the purchase and the rehab have to fit under it before 5% down works. 5% down and 100% financing are metro programs: the property has to be inside a Texas metro area (MSA). A rural house can still get a loan, on different underwriting and usually with more down.
How long does it take to close?
Send the deal in about five minutes with no credit pull, we shop it to the lenders whose programs fit, the appraiser confirms the after repair value and the lender reviews the scope. Closing takes 5-14 days typical, as little as 72 hours on Fastest Close. The purchase funds at the table and the rehab comes back to you in draws.
Texas fix and flip loan FAQ
What is a fix and flip loan?
How much do I need to put down on a fix and flip loan in Texas?
Can a first-time investor get a fix and flip loan with 5% down?
Does the loan pay for the rehab?
How much cash do I need to close on a fix and flip in Texas?
What credit score do I need for a fix and flip loan?
What does 75% of ARV mean on a flip loan?
How fast can a fix and flip loan close in Texas?
Is 100% financing on a flip real?
Is the $5,000 realtor finder’s fee on every term sheet?
Which questions have worked examples?
Before you make the offer
Ready to price your Texas flip?
About five minutes to an instant fix and flip term sheet. No credit pull, every fee on the page, the rehab funded in draws.