 Capital Kings LLC
Purchase-Only Loans in Texas.From 9.75%, no appraisal fee.
A short-term bridge loan for buying a house you don’t need a renovation loan on. It funds up to 87.5% of the purchase at closing on a first deal, and 90% at 700+ credit after four completed deals, with no rehab holdback, no draws and no inspections between draws, and the lender values the property in-house, so there’s no appraisal fee. Your term sheet lists every fee and who it goes to.
- No credit pull
- No appraisal fee
- Every fee on the sheet
- First purchase welcome
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Mini Term SheetCapital Kings LLCLiveOne Texas purchase, priced by credit
A $200,000 purchase of a house worth $265,000 today, no renovation financed, first deal. The same purchase at every credit band the instant term sheet prices, run through the term sheet the application generates.
| Credit | Down payment | Loan | Rate | Cash to close | Proof of funds |
|---|---|---|---|---|---|
| 700 and up12.5% down · 1% origination · 12 monthsProof of funds $44,205 | $25,000 | $175,000 | 9.75% | $35,674 | $44,205 |
| 700 and up, 4+ deals10% down · 1% origination · 12 monthsProof of funds $39,469 | $20,000 | $180,000 | 9.75% | $30,694 | $39,469 |
| 680-69915% down · 1% origination · 12 monthsProof of funds $48,942 | $30,000 | $170,000 | 9.75% | $40,654 | $48,942 |
| 620-67930% down · 1% origination · 12 monthsProof of funds $78,306 | $60,000 | $140,000 | 11% | $70,606 | $78,306 |
| Under 62035% down · 1% origination · 12 monthsProof of funds $87,711 | $70,000 | $130,000 | 11% | $80,561 | $87,711 |
Credit sets the leverage: 700 and up closes at 9.75% on 12.5% down, and under 620 the down payment steps up to 35%, $44,887 more at closing. Four completed deals at 700 and up drops the down payment to 10%, $4,980 less. Every figure includes the $5,000 realtor finder’s fee line and the $5,000 earnest money credit, which offset, and the appraisal line shows as waived.
The real term sheet for this purchase
The same $200,000 purchase at 700 and up credit, on a first deal and after four completed deals. Every fee is on the sheet, and every line says who gets paid: your equity, the lender, the title company, the insurer, the realtor, or the broker.
- Down paymentEquity$25,000
- Appraisal fee, waivedAppraiser$0
- Prepaid interestLender$701
- Lender fees, origination and doc prepLender$2,749
- Broker feeBroker$2,000
- Closing / titleTitle co$3,324
- Property insuranceInsurer$1,900
- Realtor finder’s feeRealtor$5,000
- Earnest money creditCredit−$5,000
The gold broker line is the only money Capital Kings earns. The appraisal line is waived because the lender values the property in-house. The $5,000 realtor line is the agent’s own finder’s fee, paid by you and set between you and your agent, and comes off if nobody brought the deal, and your earnest money comes back as the credit under it. Proof of funds adds $8,531 of interest that stays in your account.
- Down paymentEquity$20,000
- Appraisal fee, waivedAppraiser$0
- Prepaid interestLender$721
- Lender fees, origination and doc prepLender$2,749
- Broker feeBroker$2,000
- Closing / titleTitle co$3,324
- Property insuranceInsurer$1,900
- Realtor finder’s feeRealtor$5,000
- Earnest money creditCredit−$5,000
Four completed deals at 700 and up moves the same purchase to 10% down: $20,000 instead of $25,000, and $4,980 less cash to close at the same 9.75%.
These are sample sheets for a made-up borrower, built by the same engine that builds yours. Yours takes about five minutes and doesn’t pull your credit.
Rate, down payment and every fee
| Credit | Rate | Down, first purchase | Down, 4+ deals | Origination |
|---|---|---|---|---|
| 700 and up credit | 9.75% | 12.5% | 10% | 1% |
| 680-699 credit | 9.75% | 15% | 15% | 1% |
| 620-679 credit | 11% | 30% | 20% | 1% |
| Under 620 credit | 11% | 35% | 25% | 1% |
Interest-only for 12 months, funded in full at closing, never more than 90% of the purchase or 75% of the market value. Origination has a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026, and we shop every purchase against the whole network before it’s signed.
Every fee on the term sheet
| Broker fee | 1% of the loan, $2,000 minimum, $10,000 maximum. The only money Capital Kings earns |
| Lender origination | 1% of the loan, $2,000 minimum |
| Lender doc prep | $749 |
| Appraisal | Waived, the lender values the property in-house |
| Title and closing | Texas owner’s and lender’s policy plus escrow, recording and notary |
| Property insurance | About 0.95% of the purchase, $800 minimum, est. |
| Prepaid interest | From the closing date to the end of the month |
| Realtor finder’s fee | Your agent’s fee, paid by you, $5,000 by default and set to what your agent charges, off when no agent |
| Earnest money | Credited back to you at closing |
| Reserves verified | Six months of interest |
Price your purchase right now
Prefilled with the example above. Change any number and it reprices on the same math the application’s term sheet uses.
Sizing your purchase on the same terms as the application. Get the real term sheet →
Renovating? A fix and flip loan funds 100% of the rehab in draws.
Can I buy my first investment property with one?
Most people buying a first investment property assume a lender wants a track record and a big down payment before it will fund one. On a purchase-only loan you need neither. A first purchase gets the same rate as a tenth: the loan is sized on the price you pay and what the house is worth today, and what the lender checks is your credit and the cash in your account.
700 and up gets 9.75% with 12.5% down, 680-699 gets 9.75% with 15% down, 620-679 gets 11% with 30% down, and under 620 gets 11% with 35% down on a first deal.
On the example that’s $25,000 down, $35,674 cash to close with every fee in, and $44,205 in the bank to show the lender.
The loan can’t pass 75% of what the house is worth today. Buy at a discount and it never comes up. Pay close to retail and you bring the gap in cash.
A first purchase prices the same as a tenth. Four completed deals at 700 and up drops the down payment to 10%, and experience raises leverage under 700 too.
Four mistakes first-time buyers make
- Paying close to retail. The loan is capped at 75% of the market value. On a $250,000 purchase of a $265,000 house that holds the loan to $198,750, so the down payment is $51,250 instead of $31,250.
- Using purchase-only for a real renovation. The loan funds no repairs. If the work adds square footage or is structural, lenders want it financed as a rehab or size the loan down. A fix and flip loan funds 100% of the rehab in draws.
- Budgeting cash to close and forgetting reserves. Lenders verify six months of interest on top of cash to close. On the example that’s $8,531 more in the bank.
- Waiting on paperwork. There’s no appraisal to wait on, so the closing date is set by your documents: the contract, two months of bank statements, LLC documents, ID and an insurance binder. Have them ready before you go under contract.
What happens after you apply?
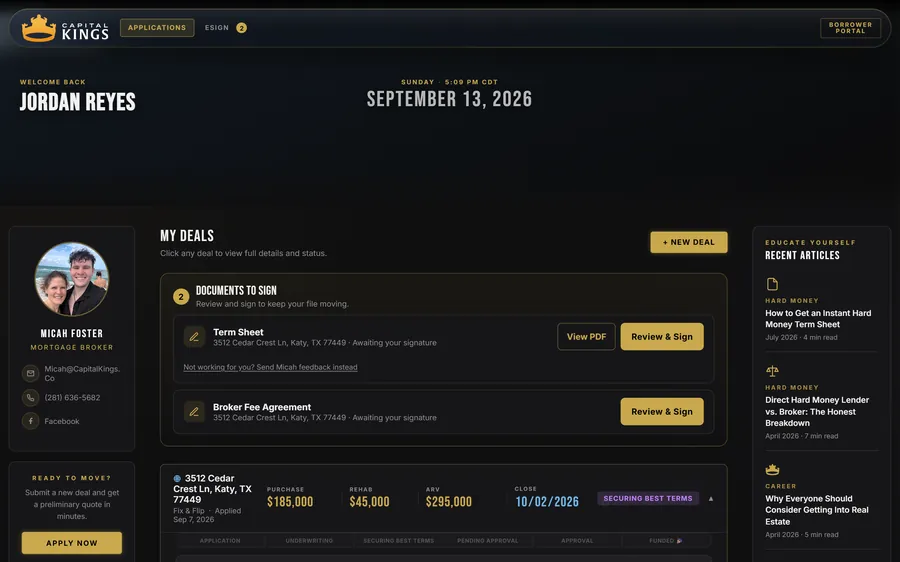
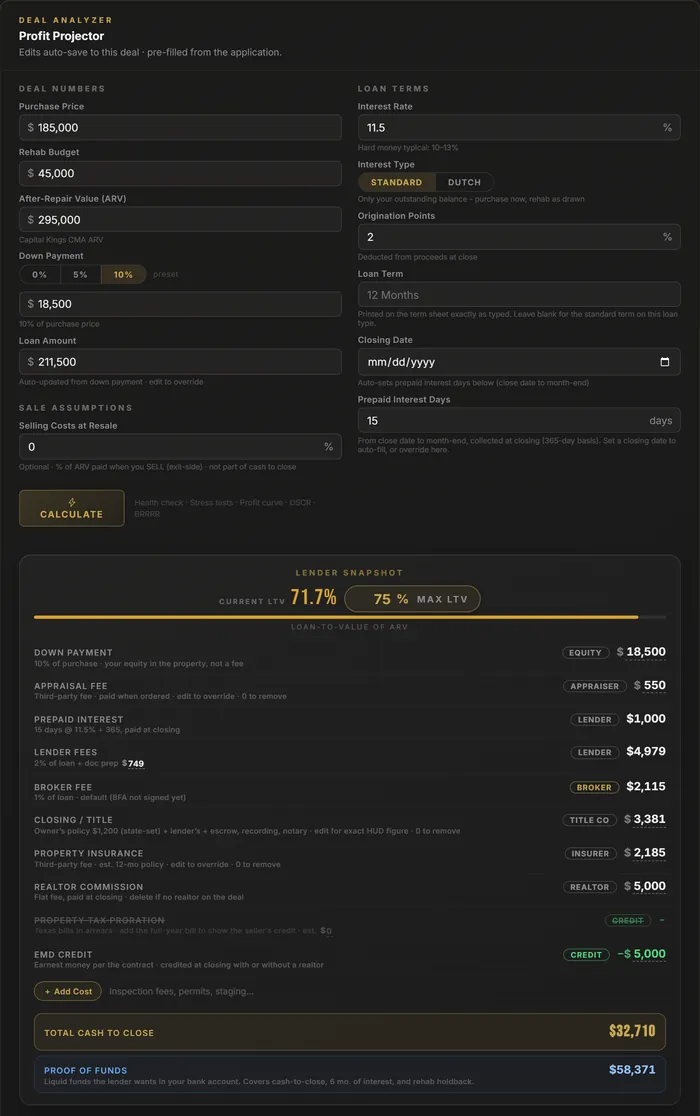
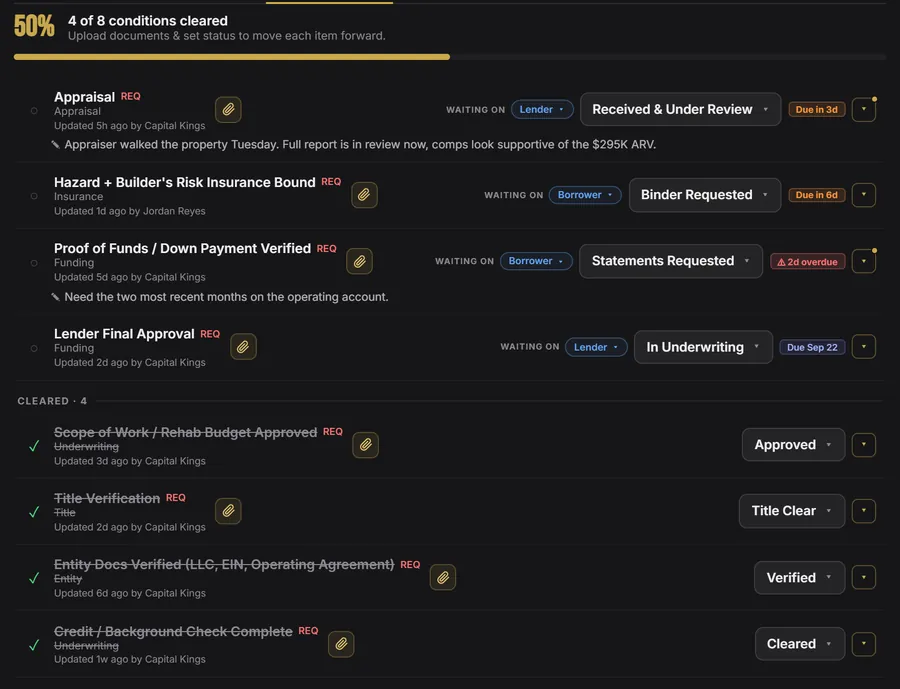
Apply once and the whole loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on.
How is a purchase-only loan sized?
$200,000 −$25,000 down =$175,000 loan
87.5% of the purchase at 700 and up on a first deal, under 75% of the $265,000 market value ($198,750).
You bring $35,674 at closing with every fee in, and show $44,205 in the bank, which covers six months of interest. No tax returns, W-2s or pay stubs.
90% after four completed deals, 65% under 620 on a first deal, and never more than 90% of the purchase. Funded in full at closing: no rehab holdback, no draw schedule. Interest-only for 12 months.
What documents does the lender need?
- Purchase contract and the property address.
- Two months of bank statements showing cash to close and reserves.
- LLC certificate of formation, EIN letter and operating agreement if you close in an entity.
- Government ID.
- Insurance quote or binder.
- Settlement statements from completed deals, if you have them. Four or more lower the down payment at any credit.
Not on the list: an appraisal, a scope of work, tax returns, W-2s or pay stubs.
Which loan does your deal need?
Renovating? See fix and flip loans in Texas, or read purchase-only vs fix and flip loans.
How long does it take to close?
Send the deal in about five minutes with no credit pull, we shop it to the lenders whose programs fit your credit, and the lender values the property while title, insurance and your documents clear. There’s no appraisal to wait on, so the closing date is set by your paperwork, and the loan funds in full at the table.
Which Texas cities have a guide?
Each city guide covers the local market, property taxes and a worked example.
Texas purchase-only loan FAQ
What is a purchase-only loan?
How much do I need to put down on a purchase-only loan in Texas?
What credit score do I need for a purchase-only loan?
Is there an appraisal on a purchase-only loan?
Can I renovate the house with a purchase-only loan?
How much cash do I need to close on a purchase-only loan?
How fast can a purchase-only loan close in Texas?
Purchase-only or fix and flip: which loan do I need?
What does Capital Kings charge on a purchase-only loan?
Which questions have worked examples?
Before you make the offer
Ready to price your Texas purchase?
About five minutes to an instant purchase-only term sheet. No credit pull, no appraisal fee, every fee on the page.