Pre-Approval Letter
Real Estate Investors
Send two months of bank statements and the name you buy under. Micah confirms you have the liquidity for the project and sends back a letter you can attach to the offer today. No credit pull, no cost, no application required.
No credit pull · Free · Issued in your LLC or your personal name · Valid 30 days · Business purpose loans only
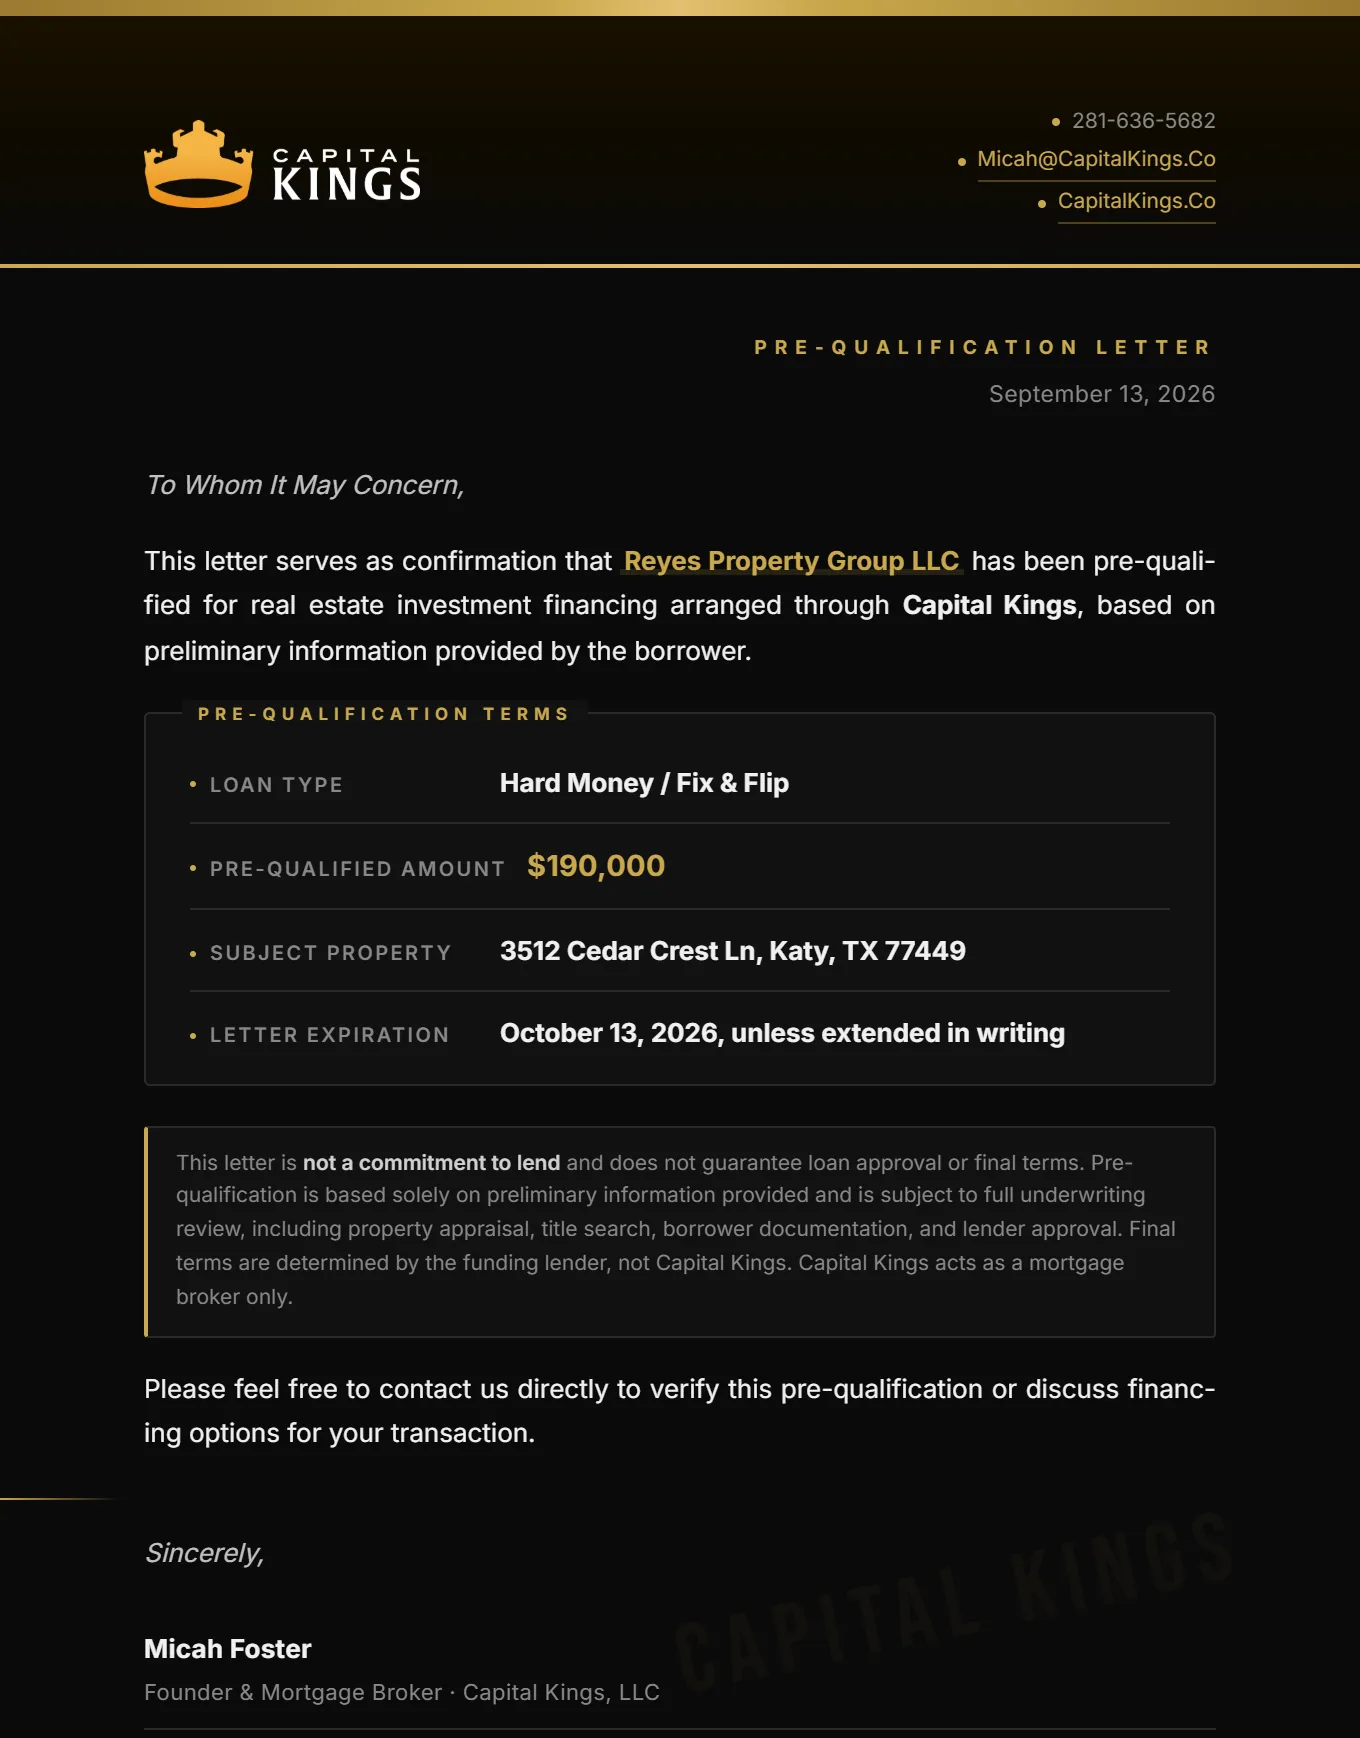
A bank will make you fill out a mortgage application to get a pre-approval. We are not a bank, and this is not a consumer mortgage. Getting an investor pre-approved comes down to one question: can you fund your side of the deal? So that is the only thing we ask you to prove.
Your two most recent bank statements, for the account the down payment comes from. Text them, email them, or upload them in the portal. Stuck somewhere without them? A screenshot of your balance from your bank's website works in a pinch.
The LLC you will buy under, or your personal name if the entity is not set up yet. The purchase price you have in mind, and roughly how much rehab you plan to do.
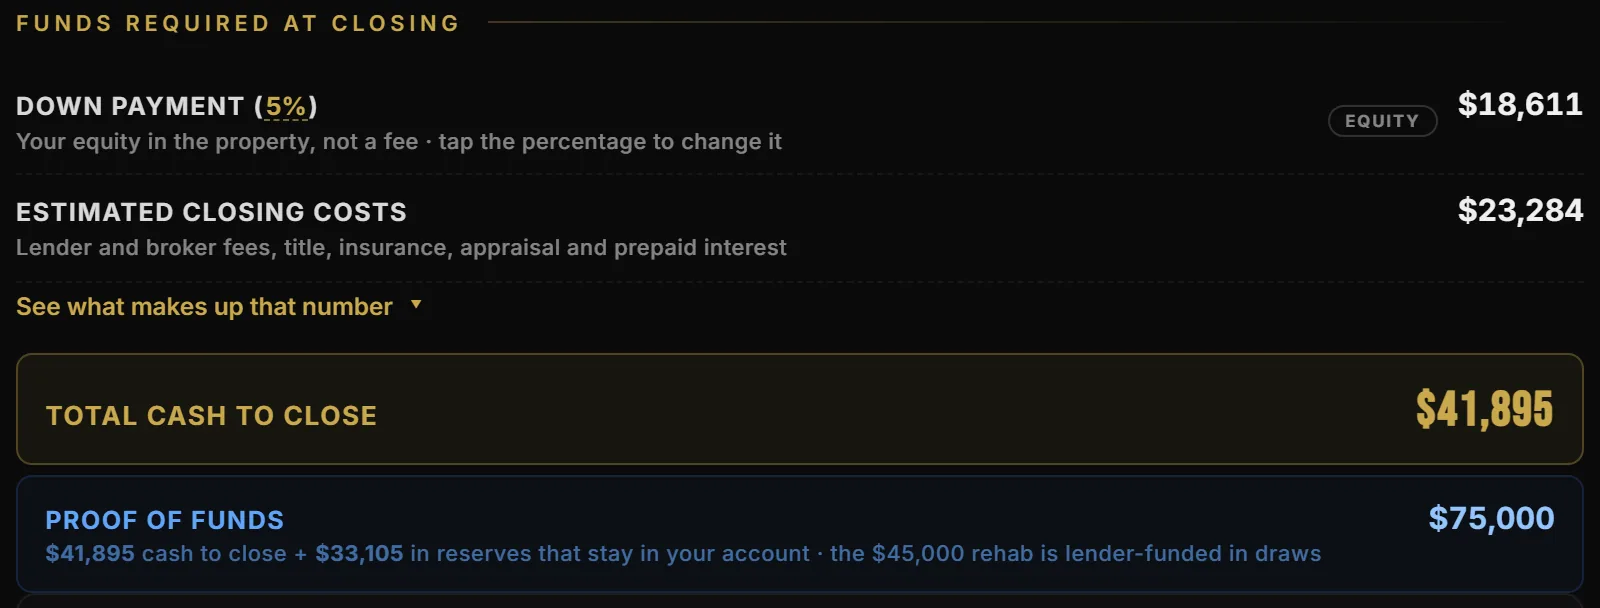
Down payment, closing costs, and the reserves a lender wants to see against the rehab. If your statements cover it, you are pre-approved. Credit is taken at your word at this stage. Nothing gets pulled.
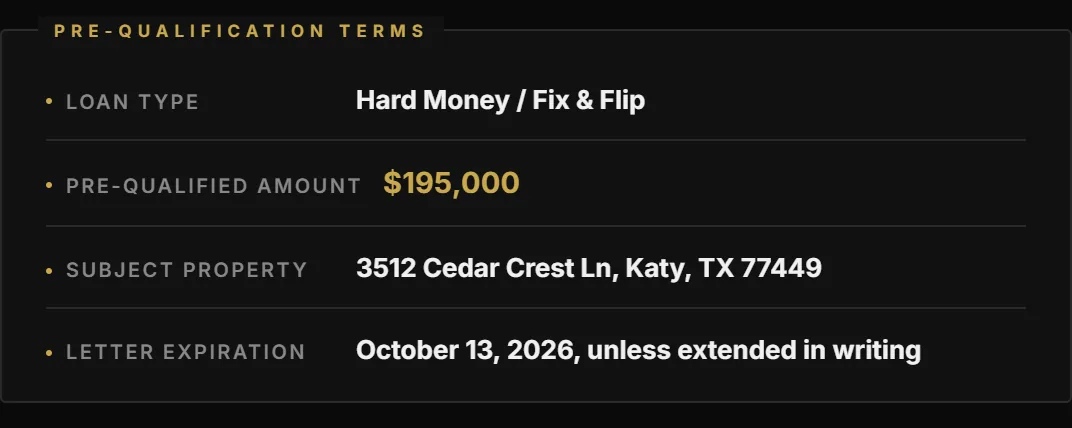
A branded PDF with the amount, the loan type, the property if you have one, and Micah's direct line for the listing agent to verify. Attach it to the offer.
Tell Micah the number you want to offer and the letter is issued at that amount. Offering under asking, then countering higher? Ask for a new letter at the new price and it comes right back. As many as you need, no fee.
Once the offer is accepted, the same file becomes a loan in your borrower portal: see every closing condition and who it is waiting on, upload your documents, sign the agreements in the browser, and run the deal through the analyzer.
Sellers and their agents see a lot of pre-approvals. Yours says exactly what they want to know: who is buying, how much they are approved for, what kind of financing it is, and a phone number that picks up. If the property is already picked out, it is on the letter. If you are still shopping, it reads as an open letter you can use on any offer.
It is dated, it expires in 30 days unless extended, and it is signed by the broker who will actually place the loan. When the agent calls to verify, they get Micah, not a call center.
It also says plainly that it is not a commitment to lend and that the funding lender sets final terms. Agents respect a letter that does not overpromise.
The pre-approval is quick because it only verifies what actually decides whether a hard money loan closes. Everything else is confirmed later, in underwriting, after you are under contract.
Two months of statements on the account the money comes from. Micah adds up the down payment, the closing costs and the reserves a lender wants against your rehab budget, and checks that your balance covers it. This is the whole test.
Tell Micah your score and he prices off it. No soft pull, no hard pull, nothing on your report for a letter. The lender pulls credit once, at underwriting, and that step shows up on your conditions checklist so it never surprises you.
Already have the LLC? The letter goes out in its name. Not yet? It goes out in your personal name and you can make offers with it today. The loan itself closes in an LLC, so you will set one up before closing, and Micah can point you to how.
You do not need this step to get a letter. But if you want to know your ceiling before you go shopping, run it right here: the kind of deal, your credit, how many deals you have done, the rehab you plan, and the liquid capital you have. It returns your total pre-approved amount, split into the maximum purchase price and the rehab the lender funds in draws, then the cash you would bring to closing. Tap the down payment percentage to reprice. Nothing here needs an email or an account, and none of it pulls credit.
The letter carries the purchase amount. What decides whether you can actually close is the cash you bring: the down payment, the closing costs, and the reserves that stay in your account. The calculator above shows all three under your estimate, so there is no surprise later.
Proof of funds is the line lenders care about. It is cash to close plus reserves, and it is what your two months of statements have to support. If you are a few dollars short, a co-borrower or guarantor's liquidity stacks with yours.
A pre-approval letter does more than prove you are financed. It anchors the number. If you want to come in under asking, a letter that says $190,000 tells the seller that is what you are approved for, and it makes the offer feel like a ceiling instead of a lowball.
So ask for the letter at the number you want to offer. If they counter, ask for another one at $195,000. Writing on three houses this weekend? Three letters. Micah generates them in about a minute each, and there is no limit, no fee, and no new paperwork after the first one.
One thing to know. The amount on the letter is what Micah has verified you can fund, not a made-up number. He will happily write it lower than your ceiling to fit an offer. He will not write it higher than your statements support, because the first time an agent calls to verify a letter that does not hold up is the last time that agent trusts one.
Fix and flip, DSCR rental, bridge, new construction. If the loan is on investment property, the letter works the same way.
Get an open letter with no property on it and carry it to showings. Agents take you seriously, and you find out your real ceiling before you fall in love with a house you cannot fund.
One text with the address and the number, letter back in minutes, offer out the door. Countering? Another letter. The file stays open, so the second one is faster than the first.
A buyer with a letter in hand is a buyer who performs. Send your investor to this page, or text Micah the intro yourself, and the letter comes back to both of you.
The letter is backed by a lender network that covers 37 states, with the deepest roots in Texas investor markets. Buying across a state line changes nothing about how fast you get it.
I can usually get a borrower pre-approved in minutes, and the reason is simple. I am not pretending the letter is something it is not. It says you have the money to do the deal, because I looked at your statements and you do.
That is also why I will write you three of them at three different numbers without blinking. The letter is a tool for winning the house. Use it that way.
A pre-approval is only as good as the loan behind it. Every letter is priced off the same shelf we shop across our lender network.
It is not a commitment to lend, and it says so on its face. Capital Kings is a broker. The letter confirms that you have the liquidity to fund your side of a deal like the one you described. The loan itself is approved by the funding lender after an appraisal, title work and a full file review, and that lender sets the final terms.
It is also based on what you tell us about your credit. If the score you gave turns out to be far from the one the lender pulls, the pricing changes and the loan may too. Give the real number and the letter holds.
How we get paid. Not on the letter. Capital Kings earns one broker fee, 1% of the loan amount with a $2,000 minimum, when a loan closes, and it is printed on the term sheet you see before you sign anything. A letter that never turns into a closing costs you nothing.
Usually within minutes of Micah receiving your bank statements. There is no application to process and no committee. He confirms your liquidity covers the deal, fills in the letter, and sends the PDF. Evenings and weekends can take a little longer, but same day is the norm.
Your two most recent bank statements for the account the down payment comes from, the name you will buy under (your LLC or your personal name), the purchase price you have in mind, and a rough rehab budget if the deal has one. That is the whole list.
If you are in a pinch, a screenshot of your account balance from your bank's website or app will do for the letter. Micah will still need the actual statements before the loan goes to a lender, but they do not have to hold up your offer.
No. Micah takes your credit score at your word to issue the letter. There is no soft pull and no hard pull. The lender pulls credit once, later, when your file is in underwriting, and that step appears on your conditions checklist in the portal.
Yes. If you already know which LLC you will use, the letter is issued in its name. If not, it goes out in your personal name and you can make offers with it right away. The loan itself will close in an LLC, so plan to have one set up before closing.
Yes, as many as you need. If you want to offer $190,000 on a $200,000 listing, ask for the letter at $190,000. If they counter, ask for one at $195,000. Micah can adjust the amount and re-issue in about a minute, and there is no fee for additional letters.
30 days from the date it is issued, unless extended in writing. If your search runs longer, ask for a fresh one. Micah may want an updated statement if your balance has changed.
No. There is no fee for the letter, for additional letters, or for the calculator. Capital Kings earns a broker fee only when a loan closes, and that fee is printed on the term sheet before you sign anything.
No, and it says so on the letter. It confirms that you have the liquidity to fund your side of a deal like the one you described. The funding lender approves the loan and sets final terms after an appraisal, title work and a full file review. Capital Kings acts as a mortgage broker.
Yes. Micah's direct phone number and email are on the letter, and he answers. Agents can call to confirm the letter is real and that the amount is what he verified.
Start on the apply page and choose Quick Pre-Approval to see your number and send your file, or skip the screen entirely and text Micah your statements.
Already under contract? Skip the letter and get an instant term sheet instead.