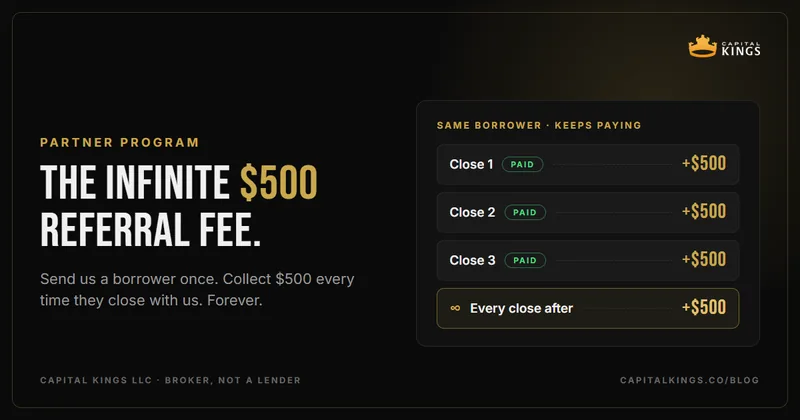
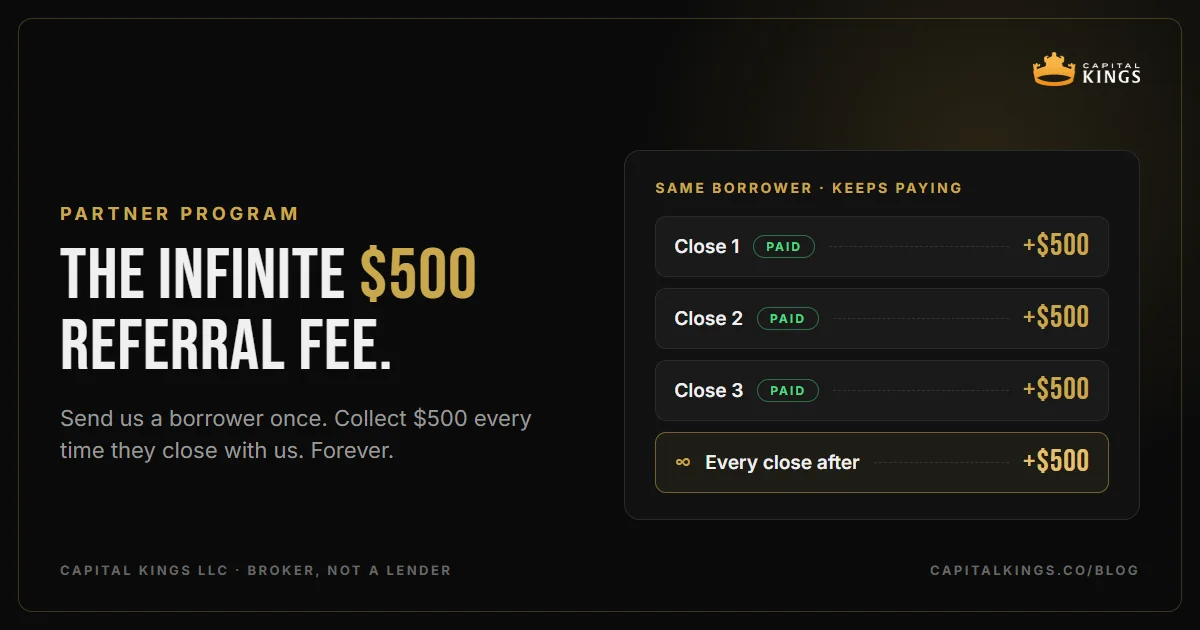
You send us a borrower. Every loan they ever close with us pays you a $500 referral fee. Not just the first one. If that same investor closes their fourth flip with me, you still get paid on deal four. Inside my system, every one of these fees carries a tag that reads 5 For Life, and that's the whole program in three words: five hundred, for life.
If you've never heard of a lender doing this, that's because most of them legally can't. I'll get to why in a minute. First, here's how it works.
How the $500 Referral Fee Works
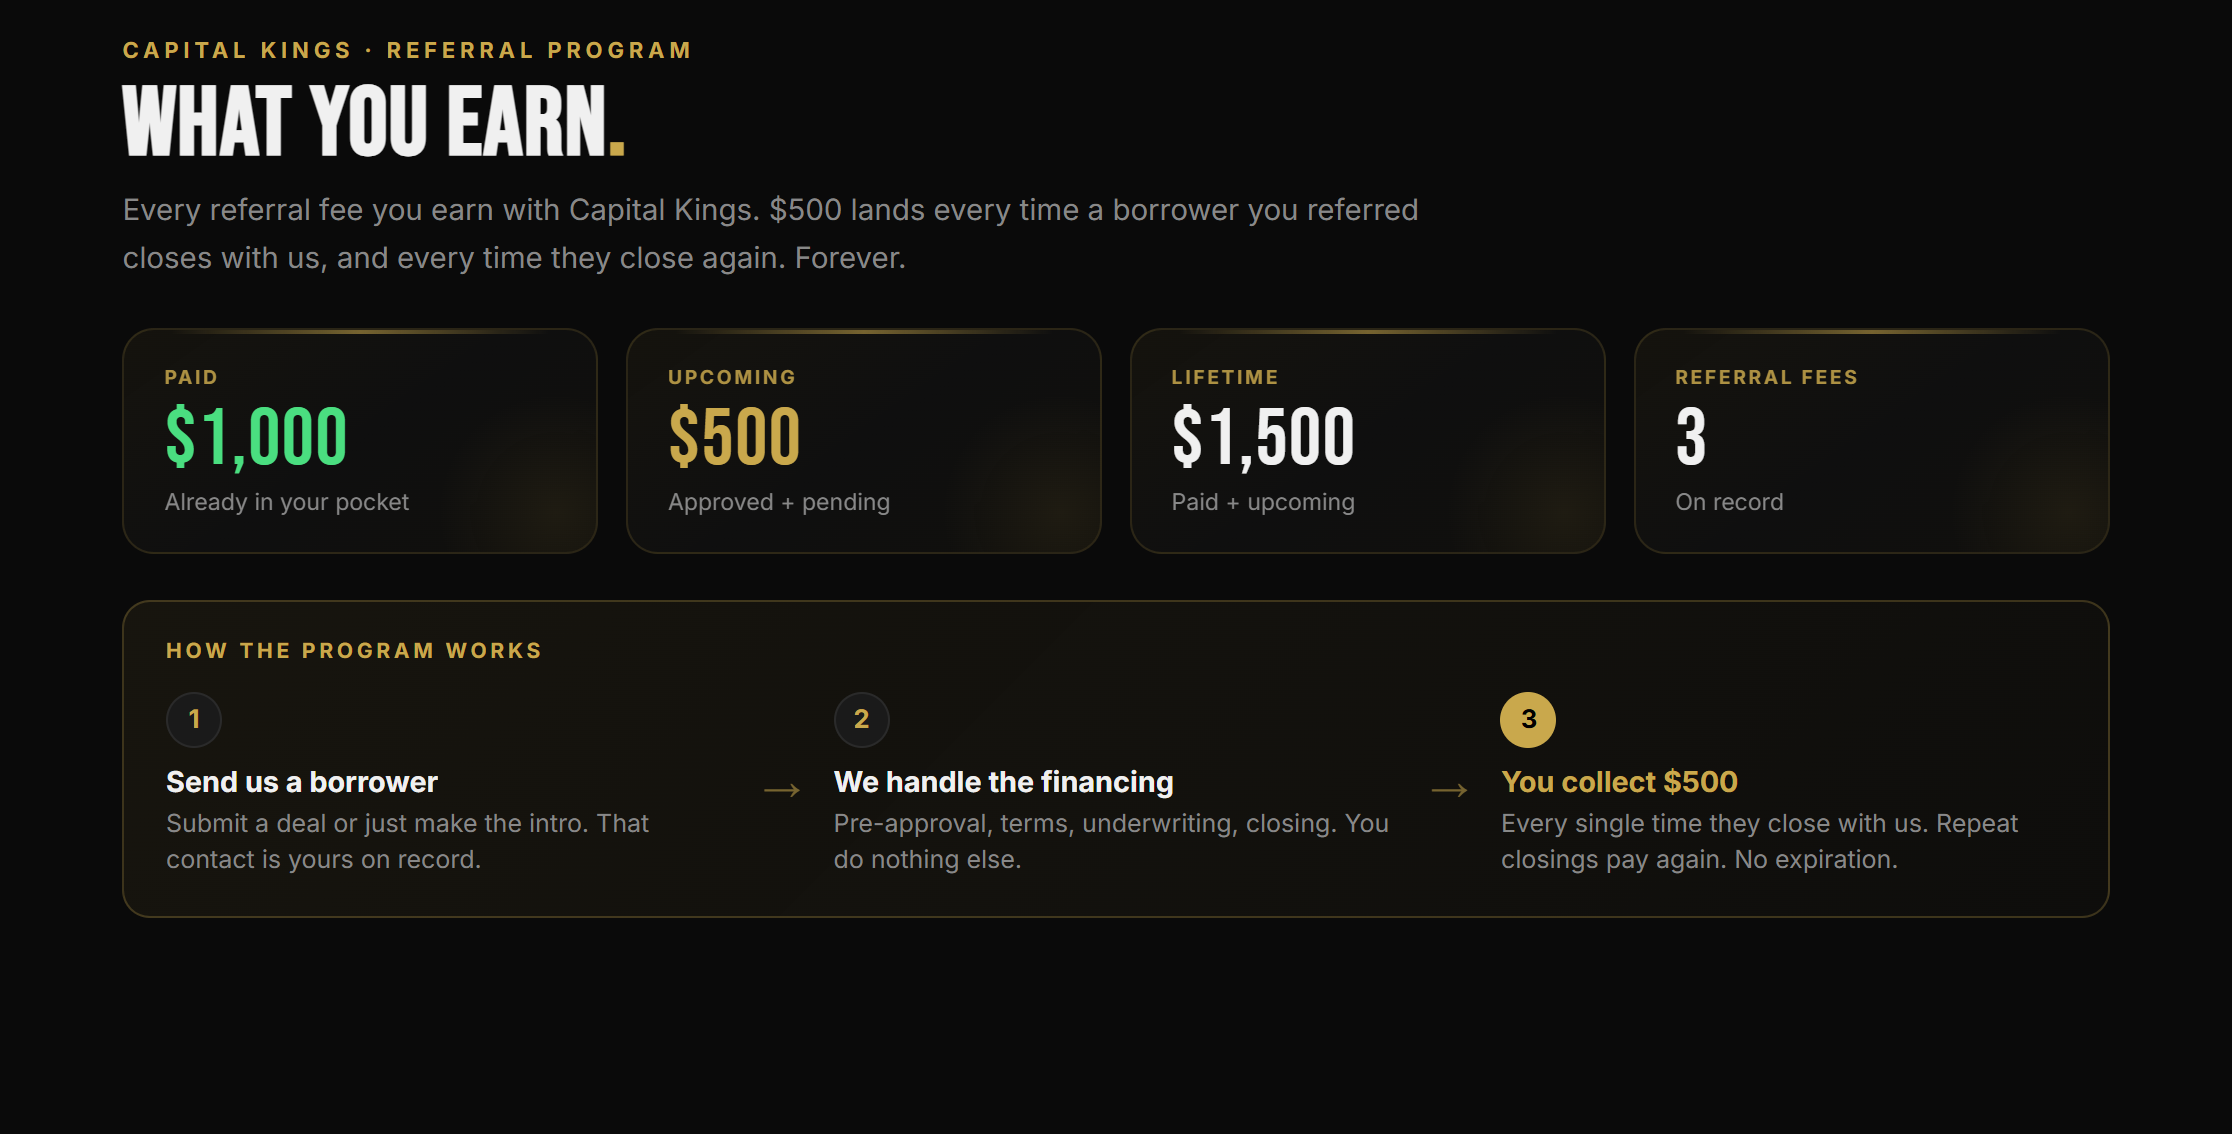
There's no contract to negotiate and no minimum volume to hit. It's three steps:
- Send me a borrower. Text or email me an introduction with their name and number, or just give me a heads-up that they're coming. My personal cell is (281) 636-5682. You can also create a free partner account, submit the deal in the portal, and follow every stage from your referral tracker. Either way, that contact is on record as yours in my CRM.
- We handle the financing. We get your investor pre-approved, then handle the term sheet, underwriting, and closing documents. You're not processing paperwork or chasing conditions. Your part ended with the introduction.
- You collect $500 when it closes. The moment the deal funds, my system creates the fee record automatically. The money goes out by Zelle or wire, whichever you prefer, as fast as the same day. When that borrower closes again, you get paid again.
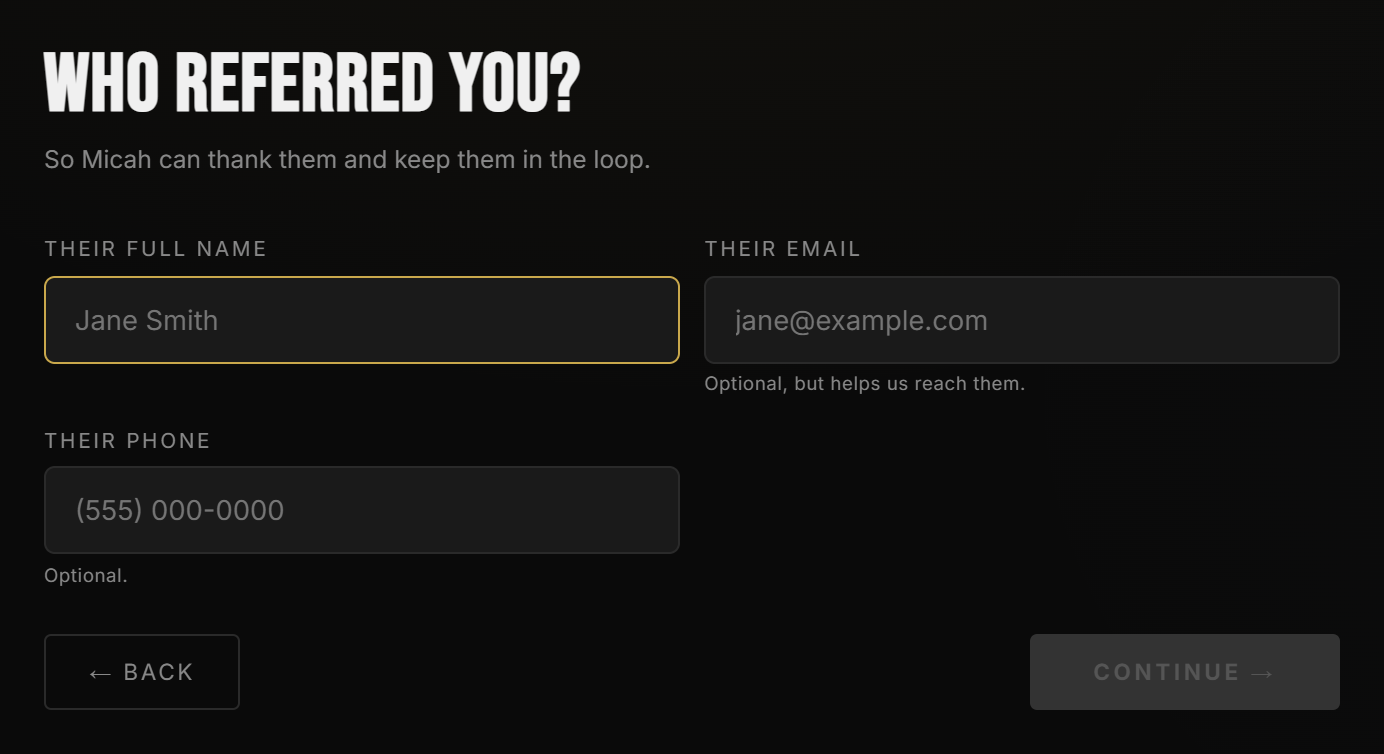
The Application Asks Who Sent Them
"Did I actually get credit?" is the question that kills most referral arrangements, so I built the answer into the application itself. When your investor applies, one of the steps asks how they heard about Capital Kings. If they answer "Referral," it asks who sent them, right there in the flow. You don't have to log anything for your intro to count.
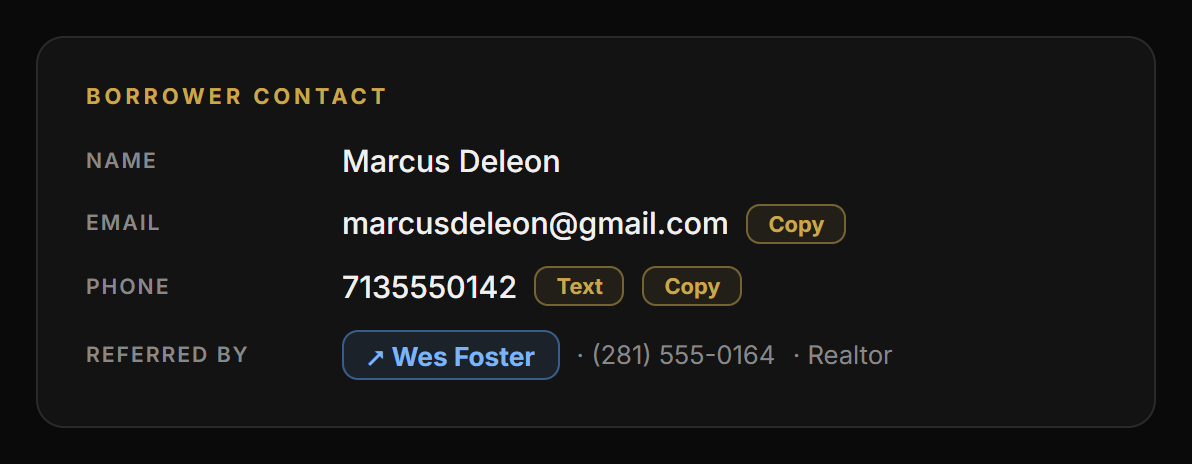
Their answer is saved to the deal on my side and stays there through closing. And if your investor blanks on your name in the middle of the application, nothing is lost. Shoot me a text and I'll add you to the deal after they apply.
Why Most Lenders Can't Pay You (and Why I Can)
Most agents have never had this part explained to them, and it's simpler than it sounds. Consumer mortgages (the loan someone takes to buy the house they live in) fall under a federal law called RESPA. Section 8 of RESPA bans referral fees on those loans outright. No lender, loan officer, or title company can pay you for sending them a homebuyer, and the penalties are steep enough that nobody tries.
That ban is the reason a lender offering referral fees sounds made up. For most of the mortgage world, it is.
But RESPA's ban covers consumer purpose loans. A business purpose loan, meaning money lent to an investor for an investment property, sits outside it, and that's all I do: fix and flip loans, DSCR rental loans, bridge loans, and new construction. On those loans a referral fee is legal and normal. I also think it's the right way to treat the person who made the deal happen.
So Who Actually Pays the $500?
Me. When a loan closes, I earn a broker fee for placing it, and the $500 comes out of that. Your client's rate, origination, and cash to close are the same whether they came through you or found me on the website. If sending me business made your client's loan more expensive, you'd stop sending it, and you'd be right to.
Most of our business comes from realtors and the people they introduce. That's the real reason this program exists. I think the people who built this brokerage should share in it.
The Infinite Part Is the Whole Point
Forget the $500 for a second and look at how often a real investor closes. The average homeowner buys a house once every seven years. An active flipper can close several loans a year, and you get paid on every one of them.
You See Everything
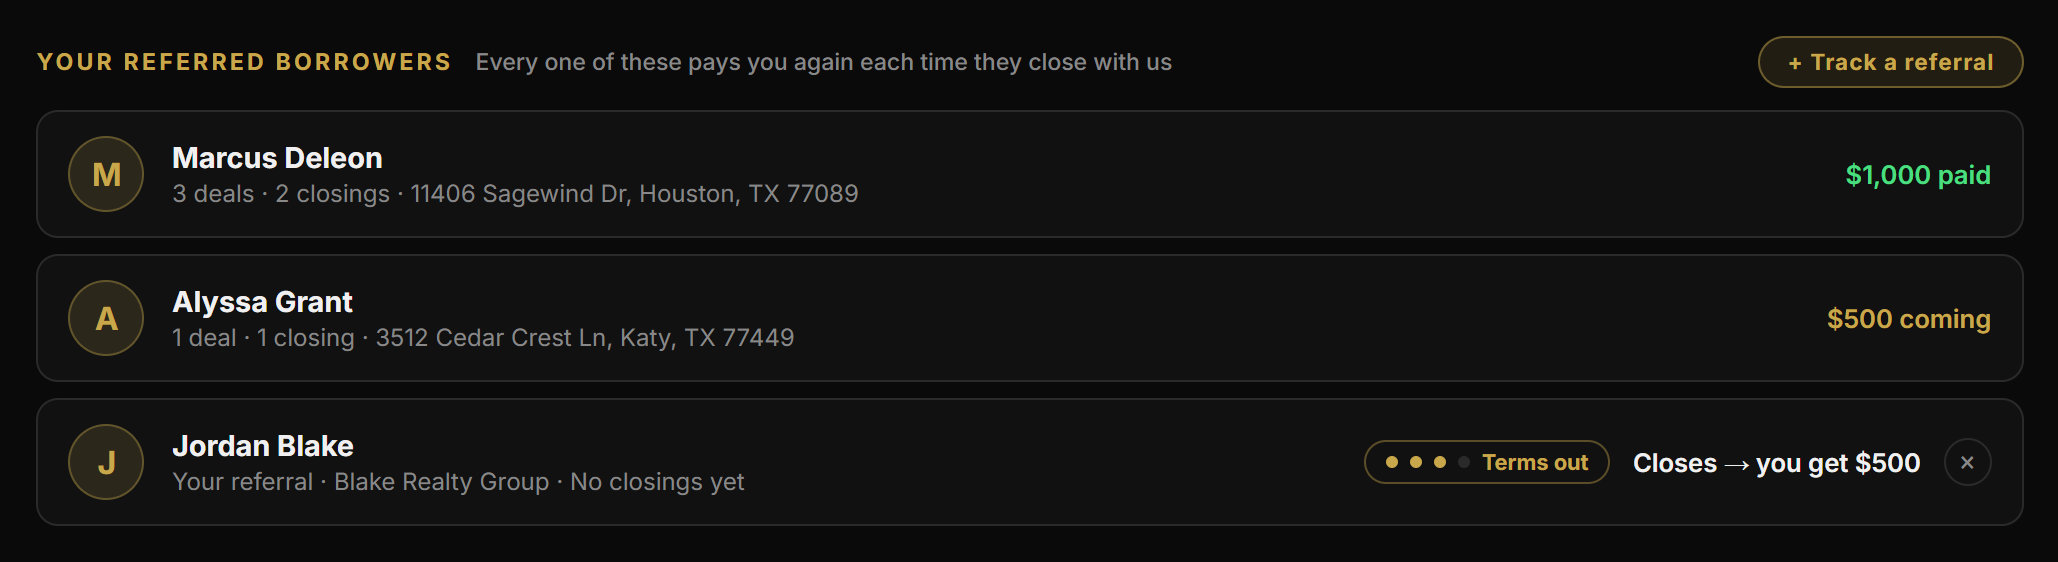
The partner portal gives you a live tracker of every borrower you've sent, how many times each one has closed, and what they've earned you. Every fee shows as pending, approved, or paid, and the status changes as the deal moves.
The Fine Print, In Plain English
- Fees pay on funded closings only. An introduction that never closes pays nothing. I only make money when a loan closes, and your fee follows the same rule.
- It's taxable income. Once your fees for the year pass the IRS reporting threshold, I'll need a completed W-9 from you before the next payout goes out, and you'll get a 1099 from me at tax time.
- Licensed agents: check your brokerage's policy on outside referral income. Most are fine with it on business purpose loans. Ask anyway.
- No cap, no expiration. These terms are current as of August 2026. If the program ever changes, the fees you've already earned stay yours.
Frequently Asked Questions
How much is the Capital Kings referral fee?
Is it legal for a realtor to accept a referral fee from a hard money broker?
When do I actually get paid?
Does the referral fee cost my client anything?
Does this stack with my commission if I am the agent on the deal?
What kinds of loans qualify?
Do I have to be a realtor or a wholesaler?
Know One Investor? That's a Referral.
Create a free partner account, add them to your tracker, and watch every stage from application to the day your $500 lands. Prefer to skip the portal? Text me the intro at (281) 636-5682 and I'll log it on my side. The fee is the same either way. You can see the full program, including the free deal toolkit that comes with it, on the partner program page.
Open the Partner Portal →