 Broker, not a lender
Hard Money Lenders inSan Antonio, Texas
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for San Antonio investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a San Antonio deal right now
Prefilled with a realistic San Antonio deal. Change any number and it reprices instantly on the lanes licensed in Texas, using the same engine behind our term sheets.
Financing a deal in San Antonio
San Antonio is the best entry-price flip market of the big four Texas metros. A large share of the housing stock inside Loop 410 was built before 1980, a lot of it before 1960, and those 1920s to 1950s bungalows and post-war ranches in 78201, 78210 and 78228 are what a first flip looks like here. The buyer pool is steady because Joint Base San Antonio and the medical center keep people arriving, and a big share of them buy with VA loans, which shapes both the finish level and the appraisal.
Two things decide a San Antonio flip. First, the historic overlay. The city has more than thirty local historic districts, including Dignowity Hill, Government Hill, Tobin Hill and Monte Vista, and inside them every exterior change needs a certificate of appropriateness before work starts, with a penalty fee if you start early. Second, the VA buyer. A lot of finished houses here sell to a service member with zero down, and a VA appraiser will flag peeling paint on a pre-1978 house, a soft roof or a dead HVAC before the deal closes. Finish the house so a VA appraisal passes the first time and the exit is faster than the comps suggest.
What a San Antonio deal looks like on paper
San Antonio example: $150,000 purchase, $45,000 rehab, $260,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1940s bungalow in Los Angeles Heights: roof, foundation piers, kitchen and baths, finished for a VA buyer. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$22,500
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,188
- Prepaid interest (15 days)Lender$673
- Property insuranceInsurer$1,853
- AppraisalAppraiser$550
Interest while you rehab: $1,008 a month on the $127,500 funded at closing, $1,364 once every draw is out. Proof of funds is cash to close plus $13,500 of rehab reserve and $8,185 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in San Antonio
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| Best Value | 5% | 590+ | First flip OK | 9.99% to 12.99% | 2% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Lowest Down (100% financing) | 0% (100% financing) | 650+ | First flip OK | 11.75% | 3% | 70% of ARV | 12 months | 14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the San Antonio comps say
Redfin puts the San Antonio median sale price at $265,000 for the three months ending August 2026, about 2% below a year earlier, with homes going pending in 58 days. Zillow’s home value index for the city is $247,453, and the flip ZIPs inside Loop 410 sit well under that: 78201, 78210 and 78228 all index between $166,000 and $172,000.
| Median sale price, San Antonio (Redfin, 3 months to Aug 2026) | $265,000 |
| Days on market, San Antonio (Redfin) | 58 |
| Zillow home value index, San Antonio (Aug 2026) | $247,453 |
| Zillow home value index, 78201 Los Angeles Heights | $171,926 |
| Zillow home value index, 78210 Denver Heights | $166,977 |
| Zillow home value index, 78228 West Side | $169,996 |
Sources: Redfin, San Antonio housing market · Zillow, San Antonio home values · Zillow, 78201 home values · City of San Antonio, historic districts · City of San Antonio, BuildSA portal
How a San Antonio file actually gets priced
San Antonio ARVs are usually conservative rather than aggressive, and the miss we see is the opposite of Austin: investors comp a Beacon Hill bungalow against Monte Vista and set the number too high. We pull closed sales inside the same historic district or the same side of the freeway, and we check the days on market on those comps, because a comp that sat 90 days and took a concession is telling you the ceiling. Foundation is the other line. Expansive clay on the south and east sides moves slabs and pier-and-beam alike, and an engineer’s letter on the foundation is often the difference between a clean appraisal and a repair condition.
Salado Creek, Leon Creek and the Olmos basin are the flood names to check, and the city has been remapping floodplains as rainfall totals get revised upward, so a property that was outside the zone on the old map may not be on the new one. Insurance runs higher than most of Texas on older stock. Inside the historic districts, budget time for the certificate of appropriateness on anything visible from the street. And in the 78201 and 78210 pockets, unpermitted additions from decades ago are common; the BuildSA record shows what is legal, and the appraiser only counts what is permitted.
Who buys your finished San Antonio deal
The finished San Antonio house under about 300 thousand sells to a first-time buyer, often military, often VA, which means the appraisal has to clear a stricter inspection than a conventional one. Those houses move fast when they are priced against the block. Above 400 thousand on the far north side the market is slower and builders are offering incentives, so a resale flip up there needs a real reason to win. The rental exit is strong here: rents cover the DSCR test on a lot of 78228 and 78223 addresses, and a good share of what we see out of San Antonio ends up a hold, not a flip.
Your whole loan, in one portal
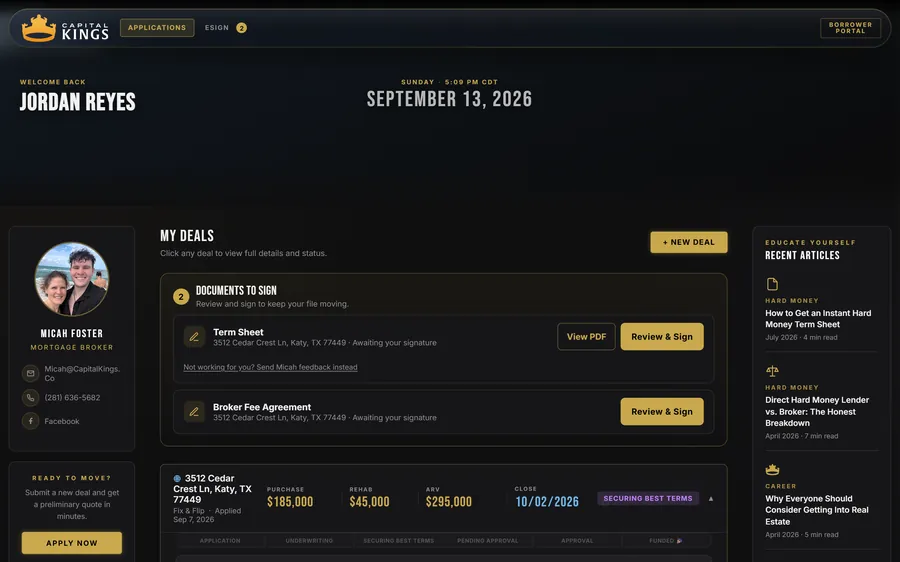
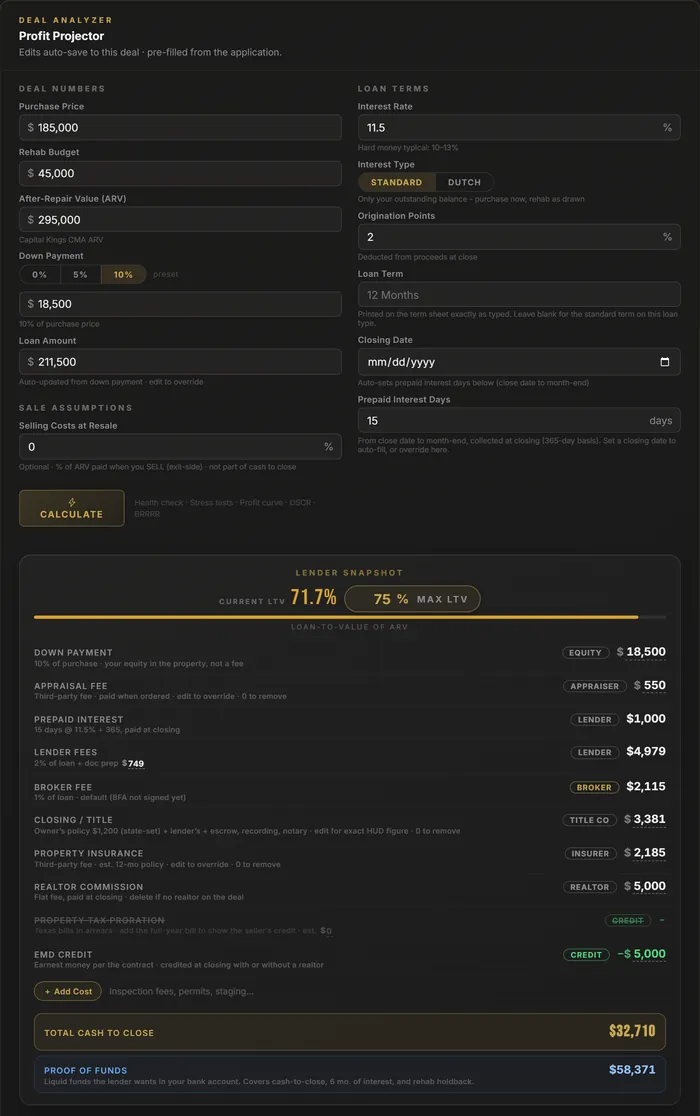
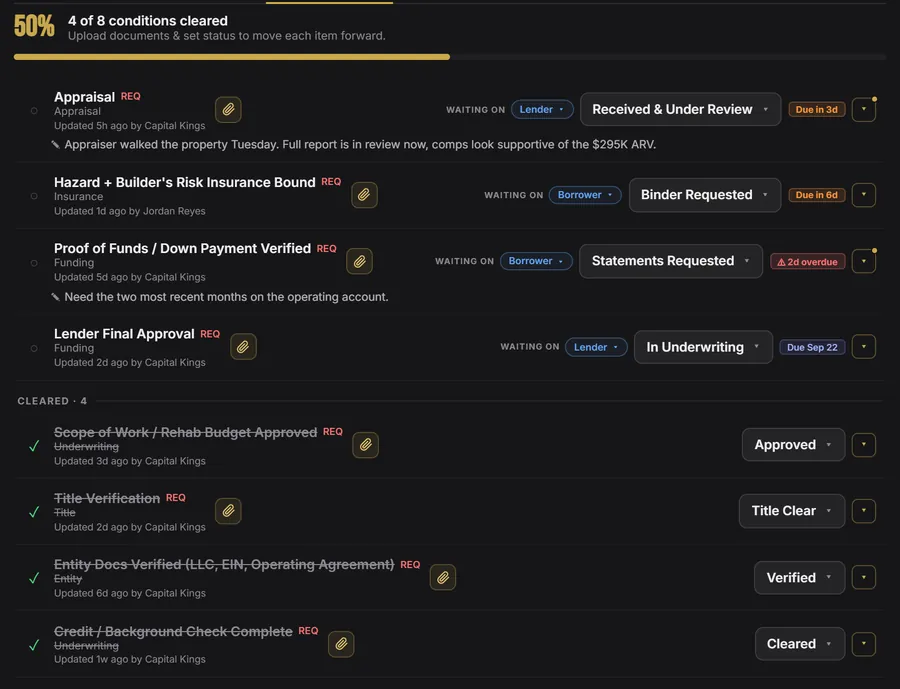
Apply once and the whole San Antonio loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in San Antonio
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in San Antonio.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in San Antonio
We broker deals across the whole San Antonio market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Texas, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
San Antonio hard money FAQ
Do you lend hard money in San Antonio?
Which fix and flip programs apply in San Antonio?
How fast can a San Antonio hard money loan close?
How much do I need to bring to close on a San Antonio flip?
Do you fund the rehab budget in San Antonio?
What credit score do I need for a San Antonio fix and flip loan?
Can I refinance a San Antonio flip into a rental loan?
Does a historic district stop me from flipping in San Antonio?
Should I finish a San Antonio flip for a VA buyer?

Before you sign anything
Ready to fund your San Antonio deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.