 Broker, not a lender
Hard Money Lenders inMcKinney, Texas
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for McKinney investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a McKinney deal right now
Prefilled with a realistic McKinney deal. Change any number and it reprices instantly on the lanes licensed in Texas, using the same engine behind our term sheets.
Financing a deal in McKinney
McKinney is two flip markets with one name. East of Highway 75 is the original town: a 1920s to 1950s downtown grid with a historic overlay, 1980s and 1990s subdivisions south of Eldorado, and the only distressed inventory in the city. West of 75 is Stonebridge Ranch, Craig Ranch and the newer master-planned sections, where a 2010s house rarely needs more than paint and where builders are still selling next door. Flips happen on the east side. The west side is a hold-or-pass market for us.
The McKinney deal is decided by the calendar as much as the numbers. Collin County has been a buyer’s market since early 2026, inventory is up sharply, and most houses sell under list, so a McKinney flip needs a real discount on the buy and a finish that sells in the first three weeks. Then there is the overlay. Inside the two downtown historic districts, any exterior change visible from the street needs a certificate of appropriateness, windows and siding included, and in-kind repairs are the only thing exempt. Buy inside the district for the premium and budget the review; buy south of Eldorado for the speed.
What a McKinney deal looks like on paper
McKinney example: $290,000 purchase, $70,000 rehab, $480,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1980s slab house south of Eldorado: piers, roof, a full interior turn, priced to beat the quick-move-in homes up north. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$43,500
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$3,165
- Title and closingTitle$3,900
- Prepaid interest (15 days)Lender$1,234
- Property insuranceInsurer$3,420
- AppraisalAppraiser$550
Interest while you rehab: $1,949 a month on the $246,500 funded at closing, $2,503 once every draw is out. Proof of funds is cash to close plus $18,900 of rehab reserve and $15,018 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in McKinney
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| Best Value | 5% | 590+ | First flip OK | 9.99% to 12.99% | 2% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Lowest Down (100% financing) | 0% (100% financing) | 650+ | First flip OK | 11.75% | 3% | 70% of ARV | 12 months | 14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the McKinney comps say
Redfin puts the McKinney median sale price at $510,000 for the three months ending August 2026, about 4% below a year earlier, with homes going pending in 49 days. Zillow’s home value index for the city is $472,118, down 5.6% year over year. The east and south ZIPs sit close to the city median: 75069 at $475,000 and 75070 at $471,000, while 75071 on the north side is $436,000 with 68 days on market.
| Median sale price, McKinney (Redfin, 3 months to Aug 2026) | $510,000 |
| Days on market, McKinney (Redfin) | 49 |
| Zillow home value index, McKinney (Aug 2026) | $472,118 |
| Median sale price, 75069 Downtown / East (Redfin) | $475,000 |
| Median sale price, 75070 Central / South (Redfin) | $471,000 |
| Median sale price, 75071 North (Redfin) | $436,000 |
Sources: Redfin, McKinney housing market · Zillow, McKinney home values · Redfin, 75069 housing market · City of McKinney, historic preservation FAQ · City of McKinney, floodplain management
How a McKinney file actually gets priced
A McKinney ARV gets set against a moving target, because 75069 sales volume has dropped by about a third in a year and 75071 sits at more than two months on market. We use closed sales from the last 90 days inside the same subdivision, we treat a comp that took a price cut as the honest one, and we do not let a Stonebridge Ranch sale price a house south of Eldorado. The historic core carries a premium, and it is real, but the appraiser only pays it for a house whose exterior work was approved and permitted.
Wilson Creek runs through the middle of the city to the East Fork, and the flood study covers Wilson, Franklin Branch, Stover and Honey Creek. The city runs flood sensors at the Valley Creek trail and the Park View crossing by Towne Lake for a reason. Everything outside the downtown grid is slab on Collin County clay, which shrinks and swells hard, so piers are a normal line item. Newer sections outside the city limits, Trinity Falls and Painted Tree among them, sit in municipal utility or public improvement districts that add real dollars to the tax bill and change who can qualify for your finished house. Tree removal needs a permit through the city portal. Short-term rentals require registration since March 2026.
Who buys your finished McKinney deal
The finished east McKinney house exits to a family buyer who wants McKinney ISD at a price under the west side, and that buyer is comparing your house to a builder’s quick-move-in home a few miles north with incentives attached. Price the exit against that, not against last year’s comps. Downtown-adjacent houses exit to a buyer paying for the walkable square, and they pay for character, not for a generic gray finish. Rents here are strong enough that a DSCR refinance works on a lot of 75069 and 75070 addresses, which is worth pricing before you list.
Your whole loan, in one portal
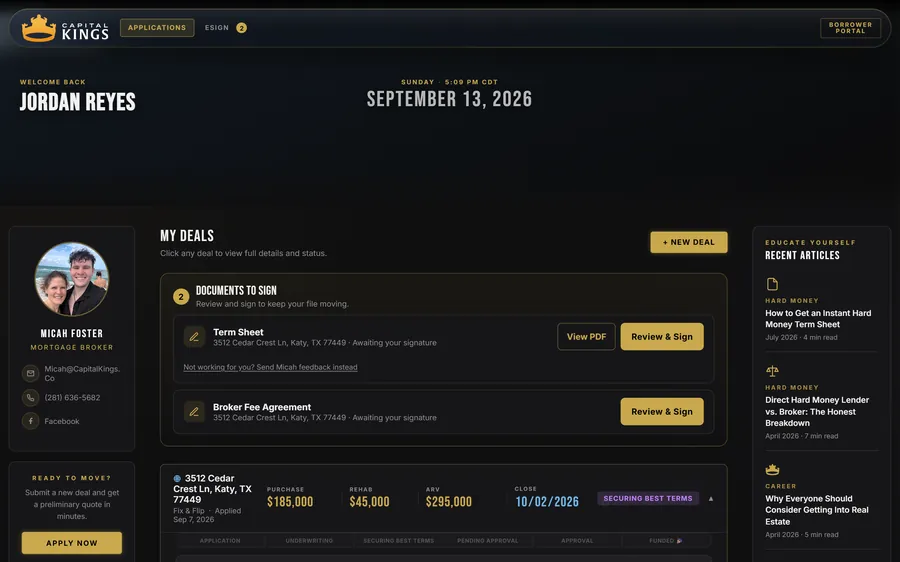
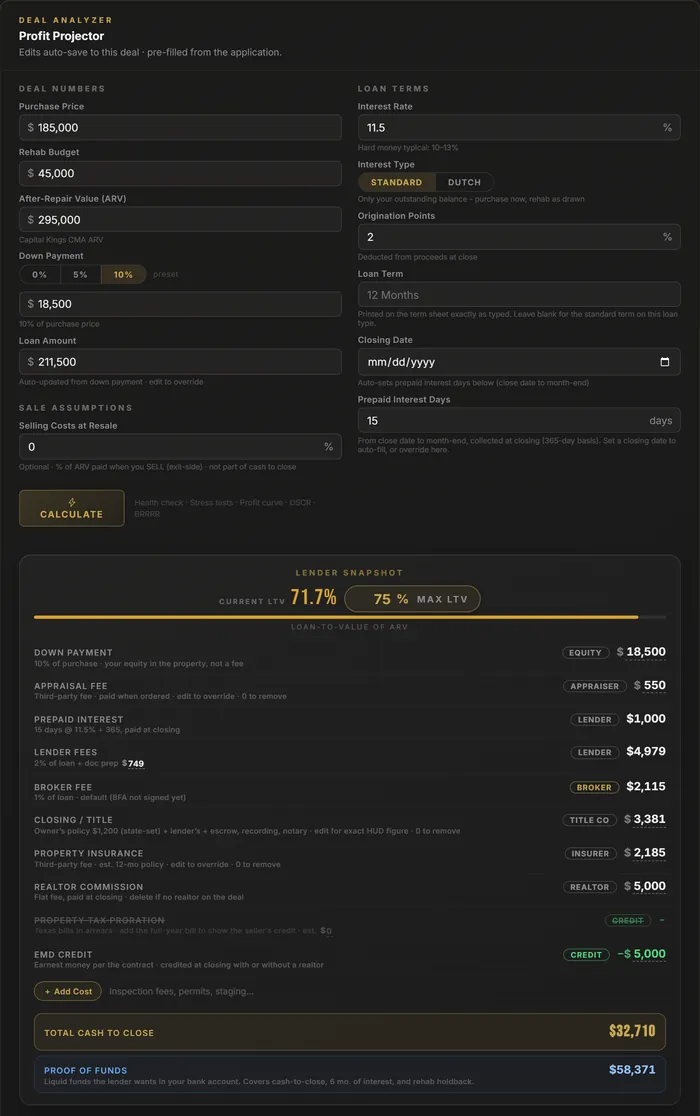
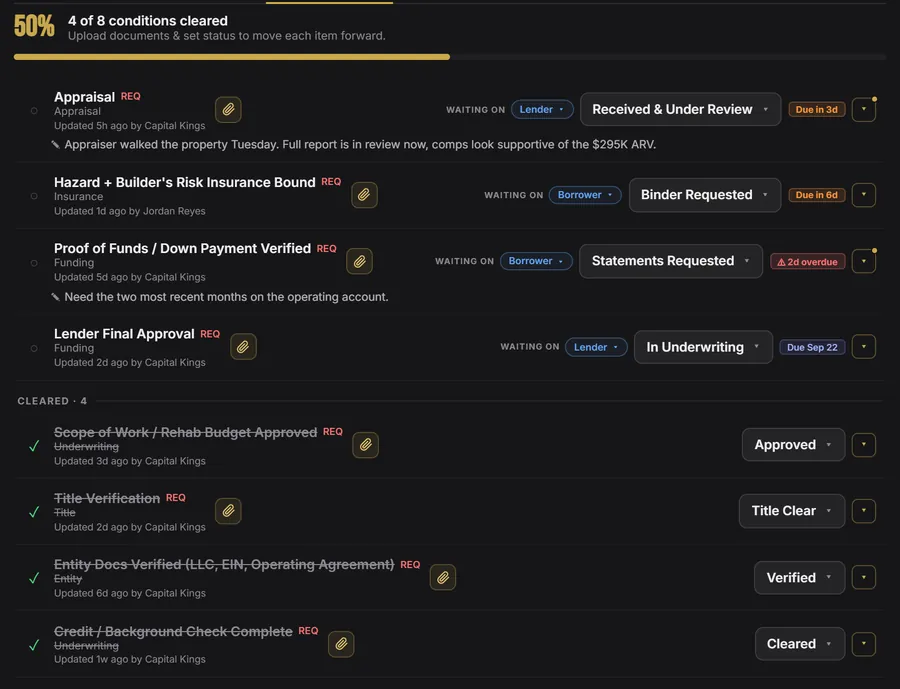
Apply once and the whole McKinney loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in McKinney
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in McKinney.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in McKinney
We broker deals across the whole McKinney market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Texas, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
McKinney hard money FAQ
Do you lend hard money in McKinney?
Which fix and flip programs apply in McKinney?
How fast can a McKinney hard money loan close?
How much do I need to bring to close on a McKinney flip?
Do you fund the rehab budget in McKinney?
What credit score do I need for a McKinney fix and flip loan?
Can I refinance a McKinney flip into a rental loan?
Is a McKinney flip fighting new construction?
What does the McKinney historic overlay actually restrict?

Ready to fund your McKinney deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.