 Broker, not a lender
Hard Money Lenders inGreenville, South Carolina
Fix and flip, DSCR rental and new construction financing for Greenville investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Greenville deal right now
Prefilled with a realistic Greenville deal. Change any number and it reprices instantly on the lanes licensed in South Carolina, using the same engine behind our term sheets.
Financing a deal in Greenville
Greenville grew up as a textile town, and its flip stock still looks like it. The mill villages that ring downtown, Judson, Brandon, Poe, Monaghan and Woodside among them, are rows of small 1900s to 1920s frame houses on piers. Downtown’s Main Street and the Swamp Rabbit Trail made those villages desirable again, and BMW, Michelin and Prisma Health keep buyers coming.
The Greenville deal starts with which Greenville. The city limits are small, and most “Greenville” addresses are in unincorporated Greenville County, with different permits, inspectors and taxes. Then there’s the mill house itself: two bedrooms, one bath, small rooms. The flips that sell add a bath or open the plan inside the footprint, and the ones that struggle try to make a mill house into something it isn’t.
What a Greenville deal looks like on paper
Greenville example: $175,000 purchase, $60,000 rehab, $330,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1920s mill house in Judson on brick piers, with a rotted back porch, original wiring and a single bath to rework. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$26,250
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,088
- Title and closing (estimate at Texas rates)Title$3,367
- Prepaid interest (15 days)Lender$814
- Property insuranceInsurer$2,233
- AppraisalAppraiser$550
Interest while you rehab: $1,176 a month on the $148,750 funded at closing, $1,651 once every draw is out. Proof of funds is cash to close plus $16,200 of rehab reserve and $9,905 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Greenville
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 5-14 days |
| First Flip, 10% Down1 | 10% | 680+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 680+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips4 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Loans of $150,000 and up. Smaller loans are priced per file. Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Loans of $150,000 and up. Smaller loans are priced per file. Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% and 2 to 3 points, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Greenville prices sit right now
Before we price a Greenville flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the City of Greenville median sale price at $492K for the three months ending September 2026, down 8.8% on a year earlier, with homes selling in around 71 days; that number is pulled up by downtown and Augusta Road. Zillow’s average home value for the city is $328,460, up 1.6%. In 29611, which covers Judson and the western mill villages, Redfin’s median is $289K.
| Median sale price (Redfin) | $492K |
| Days on market (Redfin) | 71 |
| Typical home value (Zillow) | $328,460 |
| 29611 median sale (Redfin) | $289K |
Sources: Redfin, Greenville housing market · Zillow, Greenville home values · Redfin, 29611 housing market
How a Greenville file actually gets priced
Greenville’s city median is pulled up by downtown and the Augusta Road area, so we never price a mill house off it. We set the after repair value on renovated mill houses in the same village or the next one over, matched on bath count and square footage. Selling times have stretched this year, so we check how long the comps sat. On pier foundations, we want the crawl space, the piers and the sill plates looked at before the budget is final.
The Reedy River, Brushy Creek and Richland Creek all run near the flip neighborhoods, and the Reedy floods after heavy rain, so pull the flood zone first. Mill houses bring termite damage, settled piers, old wiring and lead paint. And plan for the tax bill if you might hold. South Carolina assesses a legal residence at 4% of value but a rental or second home at 6%, so a house you rent pays half again as much in property tax as the owner-occupant next door.
Who buys your finished Greenville deal
The finished Greenville mill house sells to a young buyer who wants to walk to the trail or downtown, or to someone relocating for a job at BMW, Michelin or the hospital system. They pay for character and a second bath. Watch the new construction in Berea and the county, which competes for the same buyer at a similar price. If the sale is slow, a long-term rental on a DSCR loan works, with the higher rental tax in the numbers.
Your whole loan, in one portal
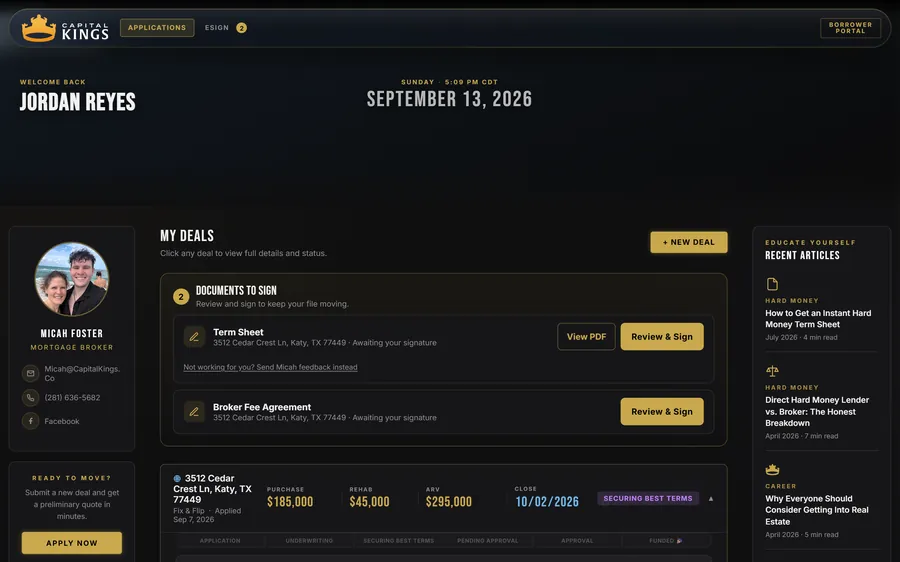
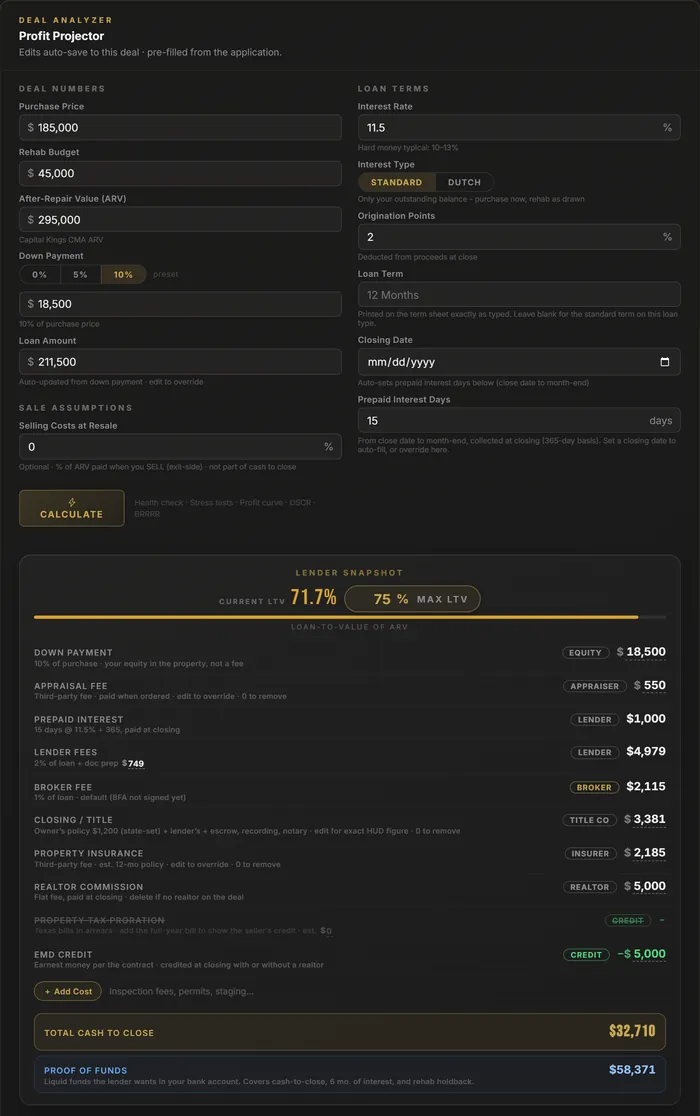
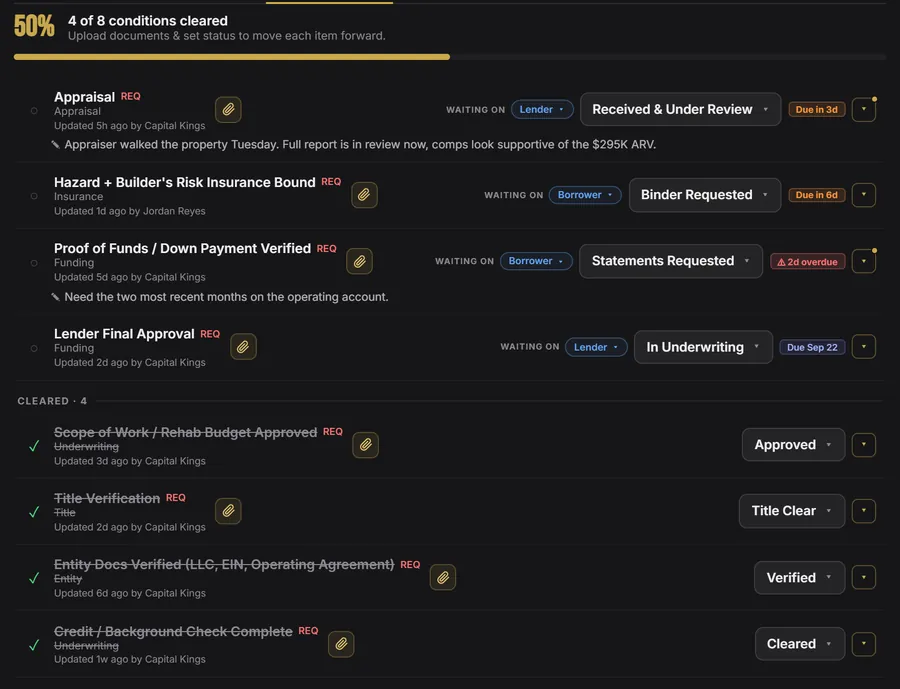
Apply once and the whole Greenville loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Greenville
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Greenville.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Greenville
We broker deals across the whole Greenville market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in South Carolina, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Greenville hard money FAQ
Do you lend hard money in Greenville?
Which fix and flip programs apply in Greenville?
How fast can a Greenville hard money loan close?
How much do I need to bring to close on a Greenville flip?
Do you fund the rehab budget in Greenville?
What credit score do I need for a Greenville fix and flip loan?
Can I refinance a Greenville flip into a rental loan?
Does a South Carolina closing need an attorney?
Why does a rental in Greenville pay more property tax?

Before you sign anything
Ready to fund your Greenville deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.