 Broker, not a lender
Hard Money Lenders inHilton Head Island, South Carolina
Fix and flip, DSCR rental and new construction financing for Hilton Head Island investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Hilton Head Island deal right now
Prefilled with a realistic Hilton Head Island deal. Change any number and it reprices on the programs that lend in South Carolina, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Hilton Head Island
Hilton Head Island is a resort island where most houses sit inside gated communities the locals still call plantations, each with its own property owners association. The flip stock is 1970s and 1980s cedar and stucco contemporaries, golf course homes and villas, often owned for decades and never updated. Buyers are mostly retirees and second-home owners, and a lot of them pay cash.
Two rulebooks sit on top of every Hilton Head deal. The first is the community’s: gated communities have architectural review boards that approve exterior colors, roofs, decks and landscaping, and contractors need gate passes to get in. The second is flood: if the house is in a flood zone and your renovation costs more than half the value of the structure, FEMA’s substantial improvement rule can require you to bring the whole house up to current flood elevation. Get both answers before you set the scope.
What a Hilton Head Island deal looks like on paper
Hilton Head Island example: $500,000 purchase, $100,000 rehab, $850,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1980s cedar-sided contemporary on the north end: rotted trim and decks replaced, new roof, kitchen, baths and new flooring throughout. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$75,000
- Origination (0.5%)Lender$2,625
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$5,125
- Title and closing (estimate at Texas rates)Title$4,930
- Prepaid interest (15 days)Lender$1,658
- Property insuranceInsurer$5,700
- AppraisalAppraiser$550
Interest while you rehab: $3,361 a month on the $425,000 funded at closing, $4,152 once every draw is out. Proof of funds is cash to close plus $25,000 of rehab reserve and $24,911 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Hilton Head Island
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| First Flip, 10% Down1 | 10% | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips4 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% and 2 to 3 points, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Hilton Head Island prices sit right now
Before we price a Hilton Head Island flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Hilton Head Island median sale price at $815K for the three months ending September 2026, up 9.1% from a year earlier, with homes selling after about 54 days on the market, compared with 63 days a year earlier.
| Median sale price, Hilton Head Island (Redfin, 3 months to Sep 2026) | $815K |
| Days on market, Hilton Head Island (Redfin) | 54 |
| Year over year change in median (Redfin) | +9.1% |
How a Hilton Head Island file actually gets priced
Appraisers compare inside the same community and the same product type: a Sea Pines house against Sea Pines, a villa against villas, oceanside against oceanside. Condos and villas add a layer, because many of the island’s complexes are rented out as vacation units, and a lender has to check whether the project meets its condo rules. A non-warrantable complex can still be financed, just with fewer lenders and different terms.
Salt air, humidity and termites go after wood trim, decks and siding, so look under the house and behind the cedar. Much of the island sits in a mapped flood zone, and both flood and wind insurance can be a large line in the carry, so price them before you buy. Hurricane season runs June through November. The Town of Hilton Head Island requires a short-term rental permit, and community rules can add their own limits.
Who buys your finished Hilton Head Island deal
The finished house sells to a retiree from the Northeast or Midwest, a second-home buyer or a buyer who will rent it part of the year, and many pay cash. They want low maintenance: composite decks, new roof, impact-rated or well-protected windows, an updated kitchen. Price against closed sales in the same community. A DSCR loan on a long-term or vacation rental is a common hold, sized on the rent the lender will count.
Your whole loan, in one portal
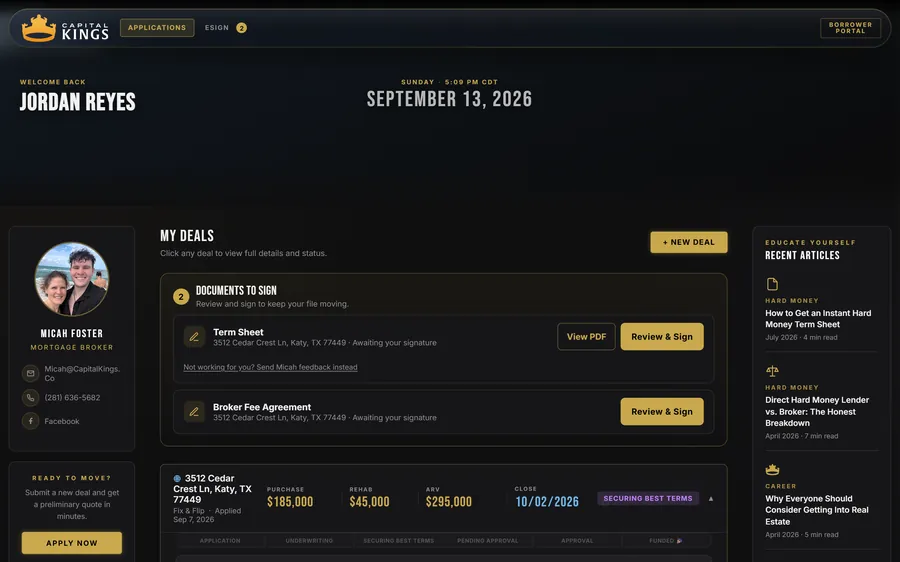
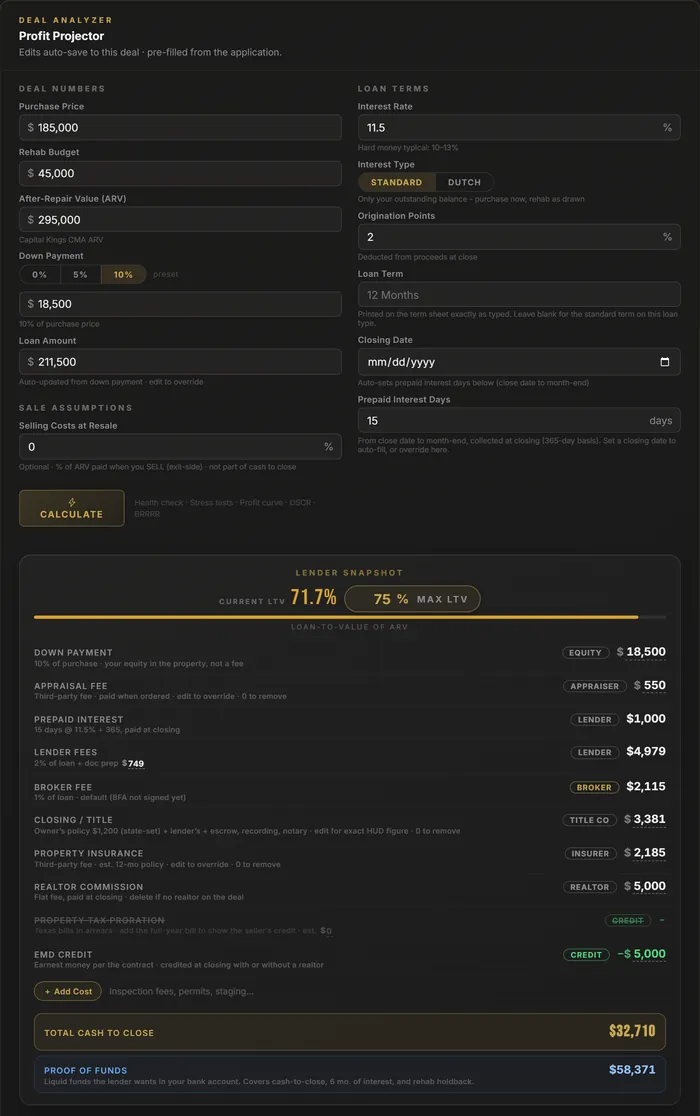
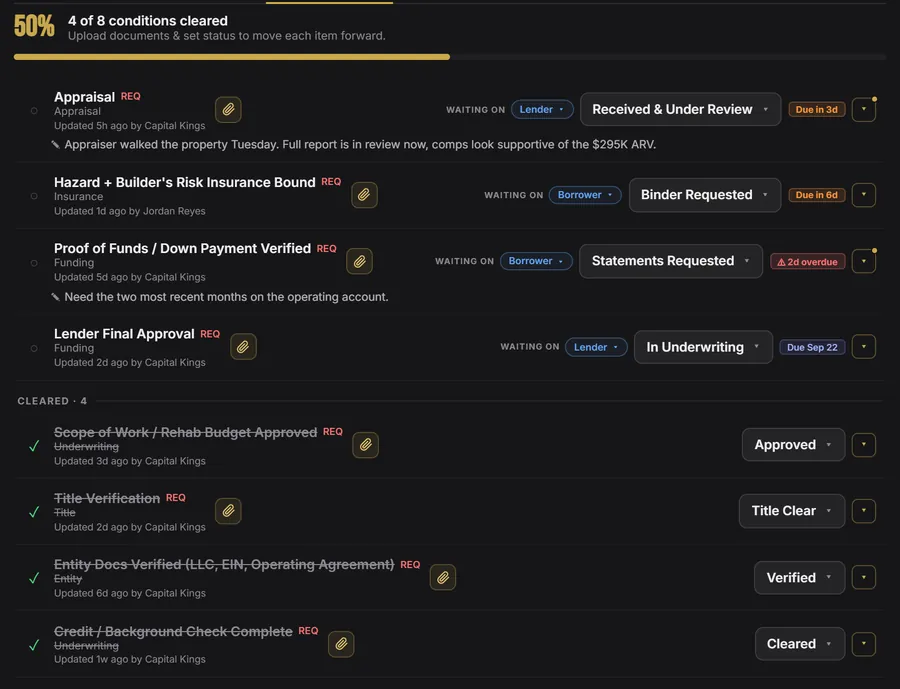
Apply once and the whole Hilton Head Island loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Hilton Head Island
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Hilton Head Island.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Hilton Head Island
We broker deals across the whole Hilton Head Island market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. About five minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in South Carolina, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Hilton Head Island hard money FAQ
Do you lend hard money in Hilton Head Island?
Which fix and flip programs apply in Hilton Head Island?
How fast can a Hilton Head Island hard money loan close?
How much do I need to bring to close on a Hilton Head Island flip?
Do you fund the rehab budget in Hilton Head Island?
What credit score do I need for a Hilton Head Island fix and flip loan?
Can I refinance a Hilton Head Island flip into a rental loan?
Can I get a DSCR loan on a Hilton Head Island rental?
Can I get a fast bridge loan on Hilton Head Island?
Before you sign anything
More South Carolina city guides
Ready to fund your Hilton Head Island deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.