 Broker, not a lender
Hard Money Lenders inFlorence, South Carolina
Fix and flip, DSCR rental and new construction financing for Florence investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Florence deal right now
Prefilled with a realistic Florence deal. Change any number and it reprices on the programs that lend in South Carolina, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Florence
Florence is the hub of the Pee Dee, where I-95 meets I-20, and its economy runs on two big hospital systems, Francis Marion University, distribution centers and manufacturing in the county. Entry prices are low next to the coast and Columbia, and the flip stock is mostly 1950s to 1970s brick ranches with hardwood under the carpet. It is a value market where the numbers work on modest rehabs.
The hospitals are the anchor. Doctors, nurses and staff are a big share of buyers and renters, so houses with an easy drive to the medical district do best. Keep the scope practical: a roof, a dry crawl space, updated kitchen and bath, and the original hardwoods refinished. Buyers here compare price first, and an over-built Florence flip sits.
What a Florence deal looks like on paper
Florence example: $135,000 purchase, $45,000 rehab, $255,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1960s brick ranch near the hospitals: new roof, a crawl space vapor barrier, kitchen, bath, paint and refinished hardwoods. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$20,250
- Origination (0.5%)Lender$2,000
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$2,000
- Title and closing (estimate at Texas rates)Title$3,125
- Prepaid interest (15 days)Lender$448
- Property insuranceInsurer$1,710
- AppraisalAppraiser$550
Interest while you rehab: $907 a month on the $114,750 funded at closing, $1,263 once every draw is out. Proof of funds is cash to close plus $13,500 of rehab reserve and $7,580 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Florence
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| First Flip, 10% Down1 | 10% | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips4 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% and 2 to 3 points, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Florence prices sit right now
Before we price a Florence flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Florence median sale price at $266K for the three months ending September 2026, up 1.1% from a year earlier, with homes selling after about 76 days on the market, compared with 86 days a year earlier.
| Median sale price, Florence (Redfin, 3 months to Sep 2026) | $266K |
| Days on market, Florence (Redfin) | 76 |
| Year over year change in median (Redfin) | +1.1% |
Sources: Redfin, Florence housing market
How a Florence file actually gets priced
With a smaller comp pool, appraisers in Florence lean on recent closed sales in the same part of town and the same build era, and they will not use a West Florence sale to value a house in East Florence. Days on market run long here, so we build a realistic hold into the loan term rather than a best case. Keep the example loan above the program’s minimum, which can matter on a low purchase price.
Most older Florence houses sit on crawl spaces, and in this humid climate moisture, sagging floor joists and termites are the common findings. Budget for a vapor barrier and treatment. Low ground near the creeks that run through town, like Jeffries Creek, can be in a mapped flood zone, so check the FEMA map. Permits run through the City of Florence inside city limits and Florence County outside them.
Who buys your finished Florence deal
The finished house sells to a hospital employee, a teacher or a first-time buyer, often with FHA, VA or a USDA loan in the outer parts of the county. Those programs bring a condition review, so finish the house cleanly. Rents are steady thanks to the medical workforce, which makes a DSCR refinance a sensible Plan B on a house close to the hospitals.
Your whole loan, in one portal
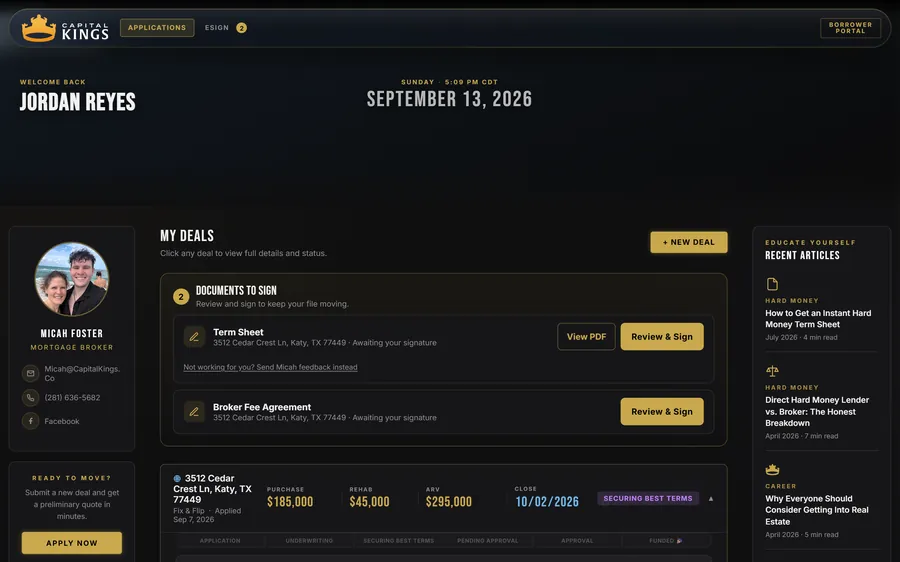
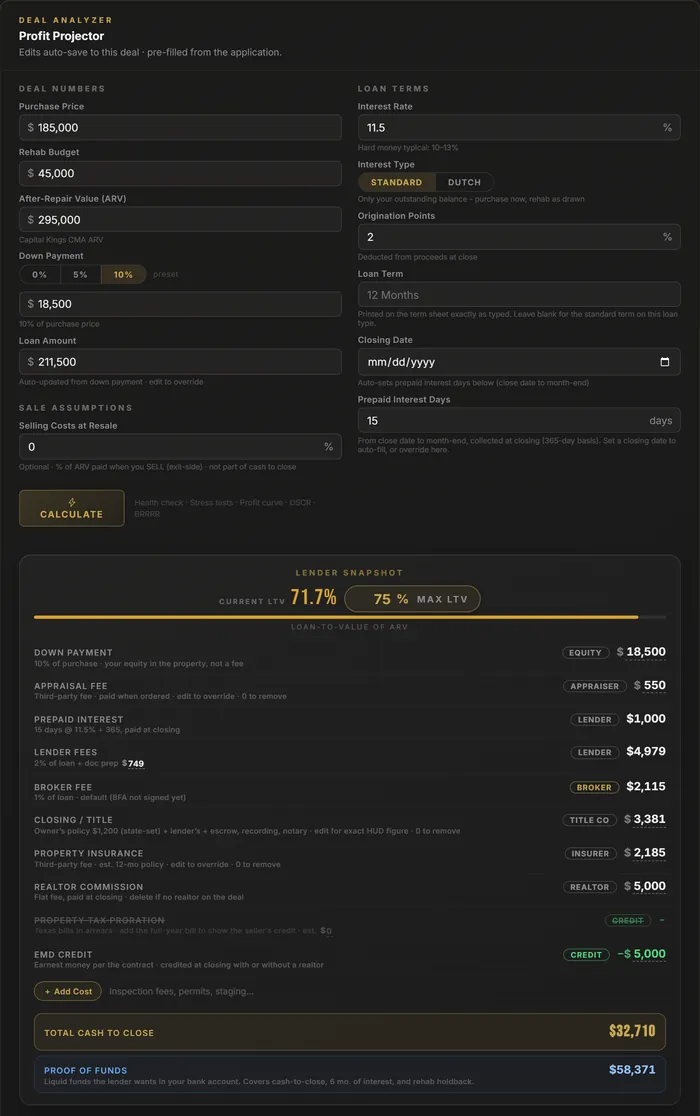
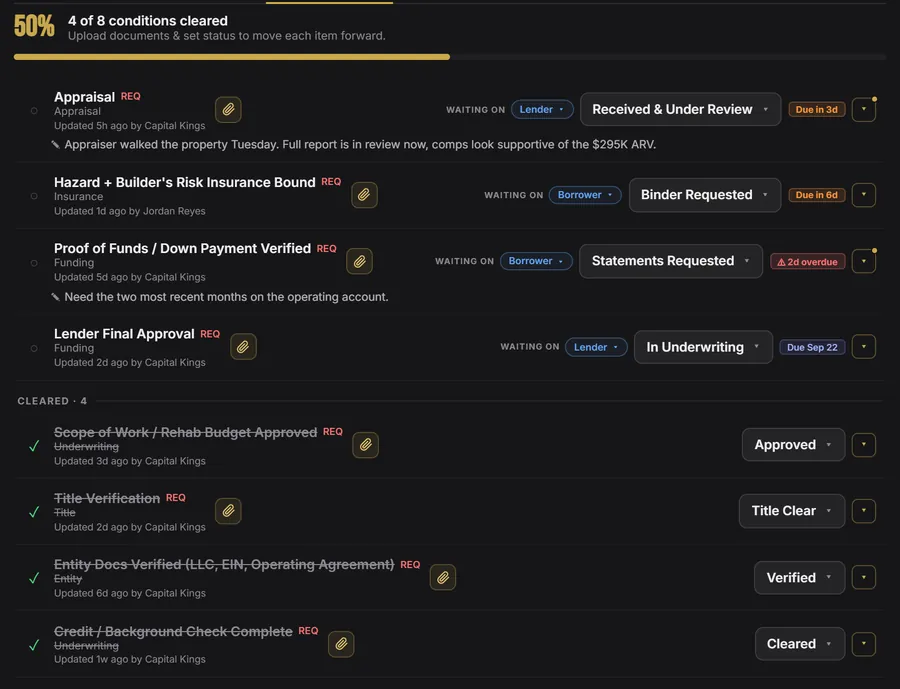
Apply once and the whole Florence loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Florence
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Florence.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Florence
We broker deals across the whole Florence market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. About five minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in South Carolina, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Florence hard money FAQ
Do you lend hard money in Florence?
Which fix and flip programs apply in Florence?
How fast can a Florence hard money loan close?
How much do I need to bring to close on a Florence flip?
Do you fund the rehab budget in Florence?
What credit score do I need for a Florence fix and flip loan?
Can I refinance a Florence flip into a rental loan?
Can I get a hard money fix and flip loan in Florence, SC?
What should I budget for under the house on a Florence flip?
Before you sign anything
More South Carolina city guides
Ready to fund your Florence deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.