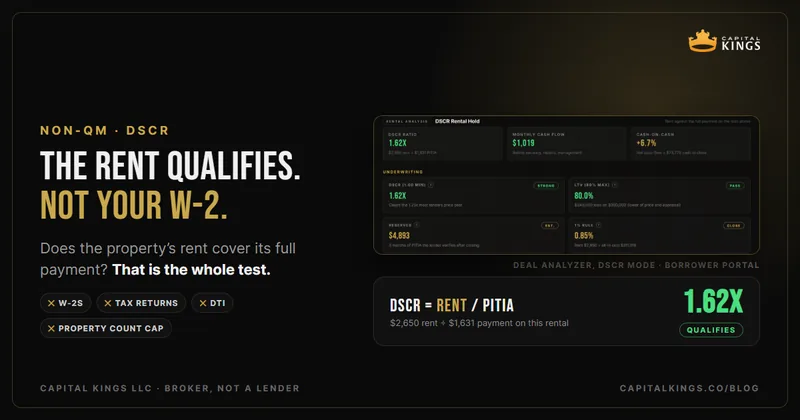
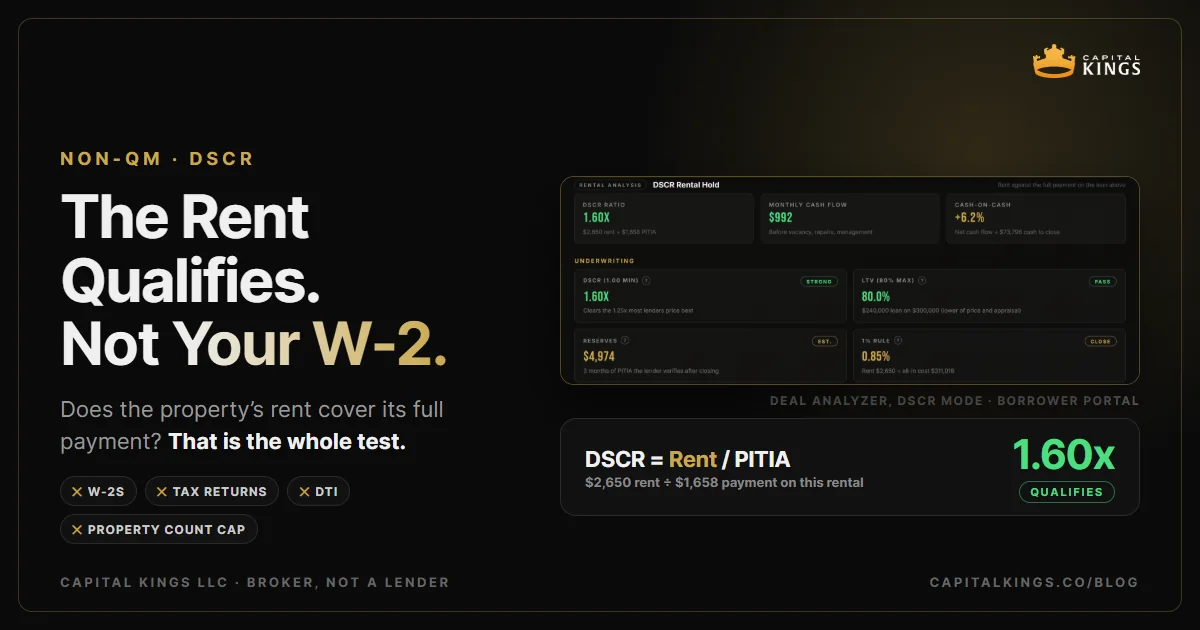
- DSCR looks at whether the property's rent covers its payment, so you don't have to hand over your personal income docs.
- If a deal comes in tight, interest-only payments, a longer amortization, or more money down can often push it over the line.
- Ask about the prepayment penalty before you sign, because it can cost you if you refinance or sell early.
DSCR stands for debt service coverage ratio, and it's one of the most investor-friendly loans in the non-QM world (investor loans that don't fit regular bank guidelines). The idea is simple. If the property pays for itself, you can qualify, and your personal income never comes up. You don't have to show tax returns or W-2s or prove your salary. For a lot of investors, especially self-employed people whose tax returns make them look broke on paper, that's a huge deal.
What DSCR Measures
The debt service coverage ratio compares the rent a property brings in to its full monthly payment. That includes principal, interest, taxes, insurance, and HOA dues, and lenders call that full payment PITIA.
So how do you read that number? A DSCR of 1.0 means the rent exactly covers the payment. The grid my instant term sheet prices from needs 1.00 or higher. At 1.25 or above the rent leaves a real cushion after the payment, and some lenders price that better, though my instant term sheet doesn't adjust the rate for it. Below 1.00, where the rent doesn't quite cover the payment, I'd have to shop the file, and a lender that takes it will charge a higher rate or ask for more down to make up the gap.
What the Lender Does Not Ask For
For investors, this is the part that matters most. On a DSCR loan, you don't have to deal with:
- W-2s
- Tax returns
- Employment verification
- Personal debt-to-income calculations
- Caps on how many properties you already own
How They Figure the Rent
If the property's already rented, the lender uses your existing lease. If it's vacant, they use a market rent analysis from the appraisal, often called a 1007 rent schedule. That's the appraiser's estimate of what the place should rent for, based on similar rentals nearby.
Short-term rental income, like Airbnb or VRBO, is handled case by case. Some lenders will use twelve months of past income from the hosting platform. Others use what the place would get as a regular long-term rental, and some won't count it at all. If you plan to run the property as a short-term rental, find out how the lender treats that income before you get too far along, because it can decide whether the deal qualifies.
What It Costs Compared to Conventional
DSCR usually costs a little more than conventional, often somewhere in the range of half a point to two points higher, depending on the loan, how much you borrow, and your file. To give you a real floor, a few lenders in my network price the strongest files from about six percent. That takes high credit, plenty of equity and rent that clearly covers the payment, and sometimes points to buy the rate down. Most programs start right around seven percent, and the grid my instant term sheet uses starts at 7.00% (760+ credit, 30% down, 5-year prepay). Your actual rate goes up from there based on your credit, how much you borrow, and how well the rent covers the payment. The current grid is in the rates guide.
You're paying a little extra so you don't have to document your income or worry about a cap on how many properties you own. For the right investor, that's well worth it.
The Levers That Make a Tight Deal Qualify
When a property comes in just under a 1.0 ratio, the deal isn't necessarily dead. There are a few common ways to get the math back in range, and they all do the same thing. They shrink the monthly payment so the rent covers more of it:
- Interest-only payments. Taking principal out of the payment for a set period at the start lowers what you pay each month and raises your DSCR.
- A longer amortization. Amortization is just how many years the loan gets paid off over. Some lenders offer a 40-year term, which gives you a lower payment than a 30-year.
- More money down. A smaller loan means a smaller payment, which directly improves the ratio.
DSCR just gives you more ways to adjust the loan than conventional does. A deal that looks borderline at first glance can often be set up in a way that gets approved, so run it past a broker before you assume it won't work.
One Thing to Check Before You Sign: The Prepayment Penalty
This one doesn't always get explained up front. Most DSCR loans carry a prepayment penalty (a fee for paying the loan off early). It's usually a step-down setup spread over the first three to five years, where the penalty gets smaller each year until it goes away.
This matters because of how investors really use these loans. If you refinance again or sell the property before the penalty runs out, that fee can take a real bite out of your return. That's no reason to avoid DSCR. Just ask how the penalty works before you sign, so your plan to sell or refinance lines up with when it goes away.
Where DSCR Fits: The Hold Exit
Most investors run into DSCR as their exit, meaning how they get out of a short-term loan. You buy a property with a hard money loan, fix it up, get a tenant in, and then refinance into a DSCR loan so you can hold it long term. That's the refinance step in the BRRRR strategy (buy, rehab, rent, refinance, repeat). DSCR is what makes it work, because you qualify on the rent the property now brings in instead of your personal income.
If you're running the numbers on a flip that you might keep instead of sell, check the DSCR refinance math before you buy. Know roughly what the property will rent for and what a DSCR payment would look like, so you're not guessing about your exit after you already own it.
Frequently Asked Questions
What is a DSCR loan?
What DSCR ratio do you need to qualify?
Do DSCR loans check your income or tax returns?
What credit score do you need for a DSCR loan?
Do DSCR loans have a prepayment penalty?
Current Texas pricing, leverage caps and the full program terms are on the DSCR loans in Texas page.
Thinking About a DSCR Loan?
Whether you're buying a rental or refinancing out of a hard money loan to keep it, I can run your numbers against my lender network and tell you what the deal actually qualifies for. You won't need income docs, and you won't be guessing.
Get Pre-Qualified →