
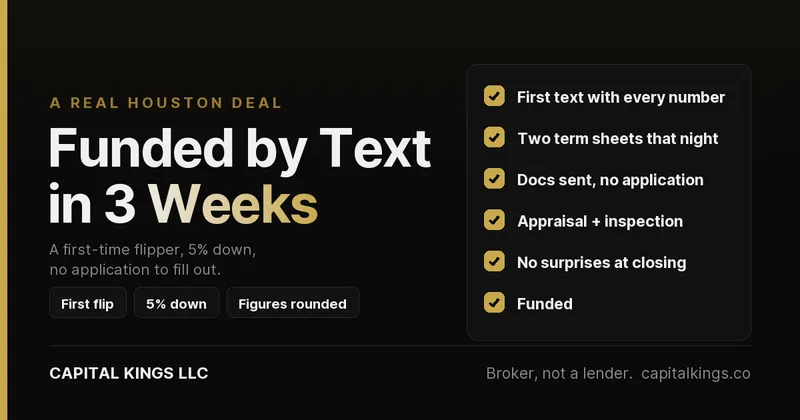
- His very first text had every number I needed, so he had two term sheets less than an hour later.
- He never filled out an application. I built it from his texts and his documents, and he signed a few things.
- He closed with no surprises, about three weeks from first text to funding. Anything that moved, he heard from me before he signed.
Based on a real deal we funded in the past week, figures rounded. I left out his name, the address and the dates.
A lot of people assume getting a fix and flip loan means a long application, a stack of forms and a bunch of phone calls. This deal didn't look anything like that. A first-time investor saw one of our Facebook ads, texted me late on a weeknight, and about three weeks later he was funded with no surprises at closing (we could have closed sooner). We talked on the phone maybe three times. Here's how it went, start to finish.
The First Text Had Everything I Needed
Here's his first text, with the address taken out and the numbers rounded:
 Micah · Capital KingsReal texts from the deal, figures rounded
Hey, saw your ad on Facebook for 5% down fix and flip funding
I have a townhome in Houston, address removed. Purchase price is about $215,000 and rehab is about $70,000, I have a contractor lined up. ARV is about $400,000.
My LLC is set up and the title company is on the contract. Closing deadline is in about 3 weeks.
I have a 700 credit score, this is my first deal and I've got about $18,000 I'm looking to bring to closing. Can you give me a term sheet on that? Is this something you can do?
That's the perfect first message. Property, price, rehab, ARV, entity, title company, deadline, credit, experience and cash. I didn't have to ask him a single question before I could price it.
Two Term Sheets That Same Night
About 40 minutes later he had two term sheets from me, each one showing the rate, every lender fee, my broker fee and the closing costs:
- 5% down. A loan of about $274,000 at about 11.5% for 12 months, 2 points of origination plus my 1% broker fee, and about $19,000 total cash to close.
- 100% financing. Less cash up front (about $12,500 to close), but 3 points, and the loan sat right at the lender's max. This program only works in major Texas metros when the price plus rehab fits under 70% of the ARV.
Micah · Capital KingsReal texts from the deal, figures roundedAbout 40 minutes later
Here's the 5% down option- total cash to close would be about $19K
What all do I need to provide? Can you send option 2 as well
2 months bank statements, LLC docs (filing, formation, EIN), the contract and your rehab budget
Let me know if you want to move forward and we can hop on a call tomorrow morning
Texts lightly trimmed, figures rounded.
For a first-timer I told him I'd go with 5% down. The fees are lower, it's a 12 month loan from the start instead of 6 months, and the 5% down lender lends up to 75% of the ARV instead of the 70% cap on the 0% down programs. I also flagged something most people don't hear until it's too late. The rehab money is paid out in draws after the work is done, so the lender wanted to see roughly $45,000 to $50,000 total in his accounts, not just the $18,000 he planned to bring to closing. He said he had it, and that settled the biggest question early.
He Never Filled Out an Application
A couple of days later he texted that he wanted to move forward with the 5% down option. I asked for four things: two months of bank statements, his LLC documents (formation and EIN), the contract and his rehab budget. He sent them that afternoon.
Then I sent one text with nine quick questions, things like whether he owns or rents where he lives, any other projects going, any large deposits, any judgments, who his insurance would be with, and how the inspector would get in. He answered all nine in a single reply. From there I put the application together myself, so he never filled out a form. He signed a few documents, and that was it.
I Told Him Exactly How Closing Would Go
Every lender's closing process is a little different, so I lay it out before it happens instead of letting it surprise anybody. On this one that meant:
- The lender would add a 10% contingency to his rehab budget, which I rebuilt in their format.
- The rate could move a little once the lender finished underwriting. I told him that on a call up front.
- Once underwriting approved it, I'd send their conditional terms next to my original term sheet so he could see exactly what changed before he signed.
- No prepayment penalty, a flat 12-month term, and no extension fees at 6 or 9 months.
- Each draw would cost about $175 plus a small wire fee.
- The appraisal and the inspection would be ordered once he signed, and someone needed to let the inspector in. His neighbor opened the door.
None of that is exciting, but it's the stuff that turns into a last-minute phone call when nobody explains it.
The Appraisal and the Final Numbers
The appraisal came back above his ARV estimate. The lender built a 10% contingency into his rehab budget, which his original numbers already had room for, and the rate came in right where I told him to expect. The final loan was about $281,000. Roughly $204,000 of it funded at closing, and about $77,000 was held back for the rehab, contingency included, to be paid out in draws as the work gets done. He signed off on the final terms and the closing documents went out.
Funded With No Surprises
The sellers signed in the afternoon and the lender wired the money the next morning. From his first text to funding was about three weeks, and nothing at closing was new to him. Every fee was on the term sheet from the first night, and anything that moved, he heard from me before he signed.
What Made This One So Smooth
- A complete first message. Every number I needed was in it, so the term sheets were real, not guesses.
- The cash question came up early. Talking about draws and reserves on night one meant nothing blew up later.
- Documents came in fast. The lender can only move as fast as your paperwork.
- No surprises. He knew every fee, including mine, that the rate could move a little, and how each step of closing would go before it happened.
If You're Doing Your First Flip
Text me the same things he did: the property, price, rehab budget, ARV, your LLC, your title company, your closing date, your credit score, how many flips you've done and how much cash you have. You'll get real numbers back, usually the same day.
If your deal is in Houston, the Houston hard money page has the programs and rates there. The 5% down cash to close breakdown walks through every line of a deal like this one, and the Texas fix and flip loan page has current pricing for every program. Just keep in mind that 5% down is for major Texas metros right now. In most other states a first flip starts around 10% down.
Frequently Asked Questions
Can I get a fix and flip loan without filling out a long application?
How long does it take a first-time flipper to get funded?
What should I send to get a term sheet fast?
Is 5% down available on a first flip outside of Texas?
Got a Deal? Text Me the Numbers
Send the property, price, rehab, ARV, credit and cash, and I'll send back a term sheet with every fee on it. Prefer to do it online? The application takes about five minutes and prices your term sheet the moment you finish.
Get My Term Sheet →