 Broker, not a lender
Hard Money Lenders inPeoria, Illinois
Fix and flip, DSCR rental and new construction financing for Peoria investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Peoria deal right now
Prefilled with a realistic Peoria deal. Change any number and it reprices instantly on the lanes licensed in Illinois, using the same engine behind our term sheets.
Financing a deal in Peoria
Peoria sits on bluffs above the Illinois River, and the city’s housing sorts itself by elevation and age. The river valley and the South Side are the oldest and cheapest, the East and West Bluff are early 1900s frame and brick houses around Bradley University and the hospitals, and North Peoria is post-war ranches and split-levels. Big employers anchor demand: OSF HealthCare, Carle and the medical district, Bradley, and Caterpillar, which kept a large Peoria presence after moving its headquarters to Texas. A first flip can be priced here.
The Peoria deal is really two markets. North Peoria ranches in 61614 and 61615 are the retail flips: predictable renovations, owner-occupant buyers, clean comps, and houses that have been going pending within a week. The bluffs are where the cheapest buys are, with large old houses at prices that look impossible from Chicago, but the finished-house ceiling is low and a lot of the buyers are landlords. Decide whether you’re building for a retail buyer or a renter before you set the scope, because a bluff house finished like a North Peoria ranch rarely gets its money back.
What a Peoria deal looks like on paper
Peoria example: $110,000 purchase, $42,000 rehab, $215,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1960s North Peoria ranch near Richwoods: roof, HVAC, a kitchen, two baths and flooring, finished for a hospital or Caterpillar buyer. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$16,500
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,005
- Prepaid interest (15 days)Lender$528
- Property insuranceInsurer$1,444
- AppraisalAppraiser$550
Interest while you rehab: $739 a month on the $93,500 funded at closing, $1,072 once every draw is out. Proof of funds is cash to close plus $12,600 of rehab reserve and $6,429 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Peoria
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Peoria comps say
Redfin puts the Peoria median sale price at $188,000 for the three months ending August 2026, about 7% above a year earlier, with homes selling in around 13 days. Zillow’s home value index for the city is $138,052, up 5.6% over the year, with homes going pending in about 7 days. The bluffs sit far under that: Zillow puts the East Bluff at $78,049 and the West Bluff at $84,067.
| Median sale price, Peoria (Redfin, 3 months to Aug 2026) | $188,000 |
| Days on market, Peoria (Redfin) | 13 |
| Zillow home value index, Peoria (Aug 2026) | $138,052 |
| Zillow home value index, East Bluff | $78,049 |
| Zillow home value index, West Bluff | $84,067 |
Sources: Redfin, Peoria housing market · Zillow, Peoria home values · City of Peoria, residential property registration
How a Peoria file actually gets priced
Peoria County appraisers comp inside tight lines, and the gap between areas is huge: Zillow puts the East Bluff and West Bluff at barely more than half the citywide index, while the North Peoria ranch streets sit above it. We set the ARV on closed sales from the same area over the last 90 days and treat a bluff comp and a North Peoria comp as different markets. On the older bluff houses, the foundation, the roof and the electrical get looked at before closing. Illinois taxes are paid a year behind, so the seller credits the buyer for them at closing, and that proration is part of your cash to close.
The Illinois River sets flood records here; the 2013 crest was the highest on record and put water into the riverfront and low parts of the city, so anything near the river or in the valley needs a flood check. Up on the bluffs, the ground slopes hard in places, so retaining walls, drainage and foundation movement are line items to price. Most of the bluff stock predates 1940, so lead paint, old wiring and galvanized plumbing are normal. Peoria requires residential rental properties to be registered with the city, which matters if the exit turns into a hold. Illinois is also a high-radon state, so test and budget mitigation.
Who buys your finished Peoria deal
North Peoria ranches exit to owner-occupants: nurses and doctors from the medical district, engineers and plant workers, and families moving up. Redfin shows Peoria homes selling in about two weeks, so a well-priced ranch doesn’t sit. Bluff houses exit more often to investors or as rentals, and with purchase prices this low the rent math is strong, which makes a DSCR refinance a real ending there. Peoria Heights and the suburbs to the north are the upper end of the market; a flip priced against them has to match their finish and schools.
Your whole loan, in one portal
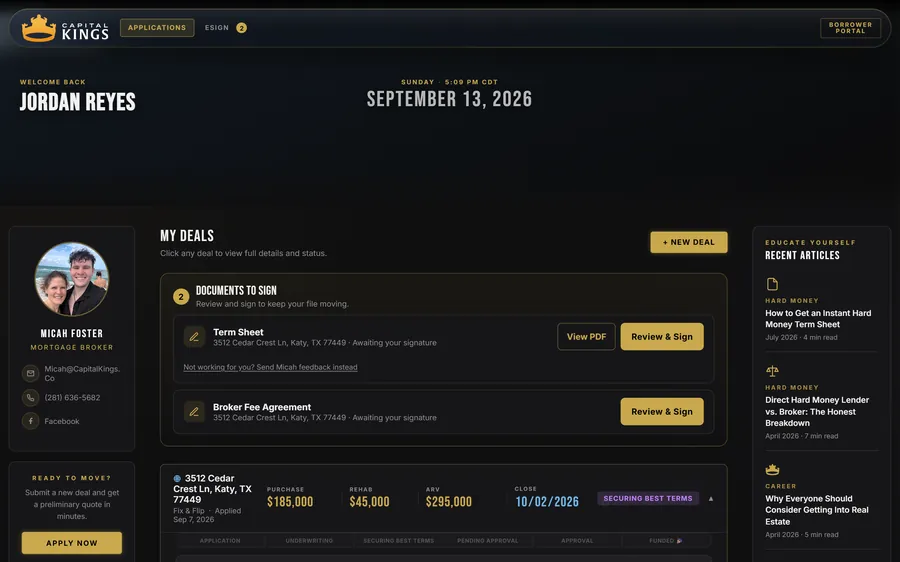
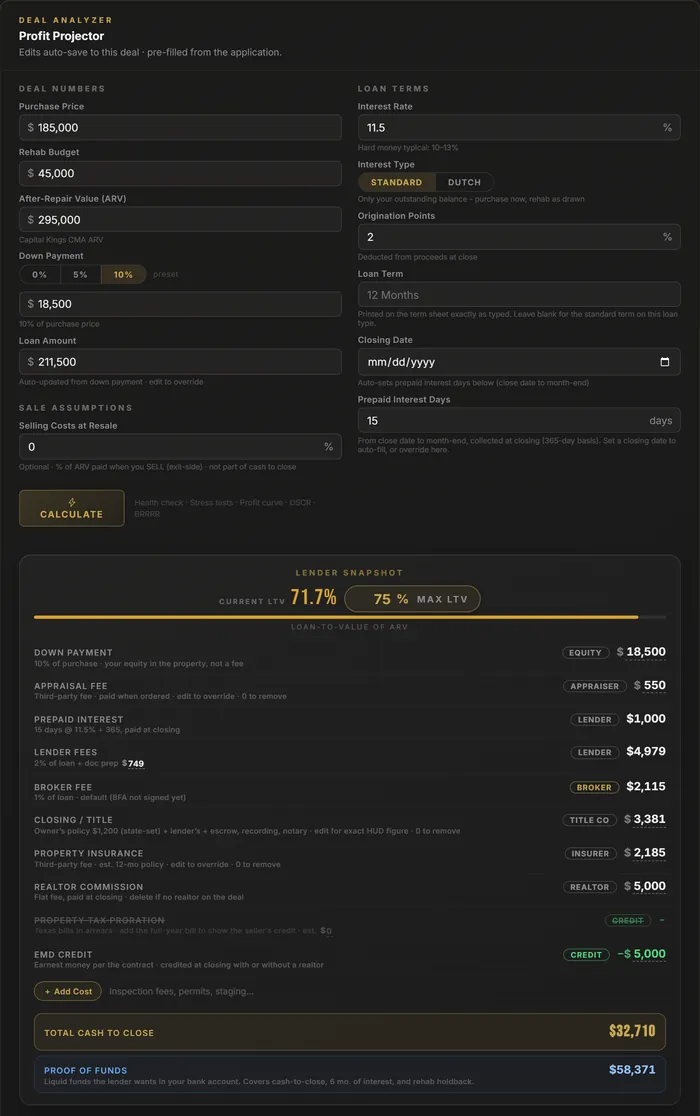
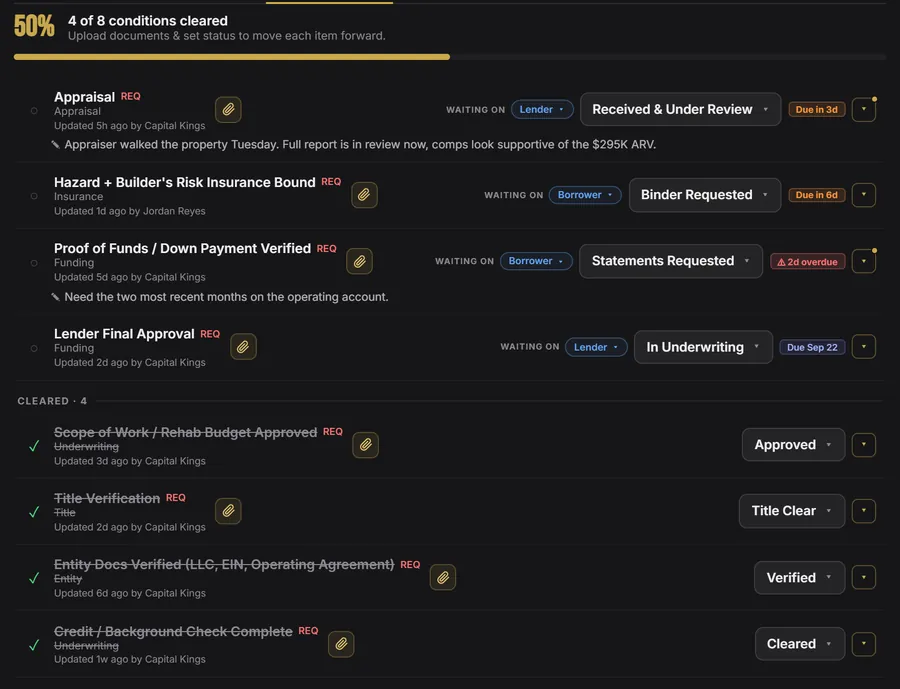
Apply once and the whole Peoria loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Peoria
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Peoria.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Peoria
We broker deals across the whole Peoria market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Illinois, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Peoria hard money FAQ
Do you lend hard money in Peoria?
Which fix and flip programs apply in Peoria?
How fast can a Peoria hard money loan close?
How much do I need to bring to close on a Peoria flip?
Do you fund the rehab budget in Peoria?
What credit score do I need for a Peoria fix and flip loan?
Can I refinance a Peoria flip into a rental loan?
Can I flip a house on Peoria’s East Bluff or West Bluff?
Does the Illinois River flood risk affect Peoria financing?

Before you sign anything
Ready to fund your Peoria deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.