 Broker, not a lender
Hard Money Lenders inMissoula, Montana
Fix and flip, DSCR rental and new construction financing for Missoula investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Missoula deal right now
Prefilled with a realistic Missoula deal. Change any number and it reprices instantly on the lanes licensed in Montana, using the same engine behind our term sheets.
Financing a deal in Missoula
Missoula is a university and outdoor town squeezed into a mountain valley, and the valley walls are the whole story: there isn't much room to build, so older houses near the river and the university carry prices that surprise people from out of state. The flip stock is the small early 1900s cottages on the Northside and Westside, the post-war houses in Franklin to the Fort, and the occasional estate sale in the University District. South Hills and Linda Vista are newer and mostly need cosmetics.
Missoula prices have come off their peak, and that changes the flip. Buyers here are careful and homes sit longer than they did a couple of years ago, so the purchase price has to account for a softer exit. The houses themselves are old. Stone and brick foundations, knob and tube wiring, galvanized plumbing and one-bath layouts are normal near downtown, and a real Missoula scope usually adds a bath or rebuilds the systems rather than just painting.
What a Missoula deal looks like on paper
Missoula example: $340,000 purchase, $70,000 rehab, $560,000 after repair value, 730 credit, 4 to 10 flips completed. The engine puts that borrower on the 5% Down, 3+ Flips program at 11.00%. Say a 1920s Northside cottage with a stone foundation, knob and tube wiring, one bath and a kitchen nobody has touched in decades. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (5%)You$17,000
- Origination (2%)Lender$7,860
- Doc prepLender$749
- Broker fee (1%)Broker$3,930
- Title and closingTitle$4,277
- Prepaid interest (15 days)Lender$1,777
- Property insuranceInsurer$3,895
- AppraisalAppraiser$550
Interest while you rehab: $2,961 a month on the $323,000 funded at closing, $3,603 once every draw is out. Proof of funds is cash to close plus $18,900 of rehab reserve and $21,615 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Missoula
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Experienced Investor Rate1 | 15% | 680+ | 2+ completed flips | 9.00% | 0.75% | 75% of ARV | 12-24 months | 7-14 days |
| 5% Down, 3+ Flips2 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips3 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Rate and origination are the program floor; two completed projects in the last 36 months preferred.
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Missoula comps say
Redfin puts the Missoula median sale price at $525,000 for the three months ending August 2026, down 10.3% from a year earlier. Homes sold after 62 days on average, compared to 54 days a year before.
| Median sale price, Missoula (Redfin, 3 months to Aug 2026) | $525,000 |
| Change from a year earlier (Redfin) | -10.3% |
| Average days on market, Missoula (Redfin) | 62 |
Sources: Redfin, Missoula housing market
How a Missoula file actually gets priced
Missoula ARVs get set inside tight neighborhoods because the premium for walking distance to downtown, the river or campus is large. A Lower Rattlesnake sale won't carry a house in Franklin to the Fort, and a South Hills comp doesn't belong in a Northside file. With prices down from a year ago, we lean on the most recent closings and discount older ones. If the number only works with a comp from the peak, you'll hear that before the term sheet goes out.
The Clark Fork and Rattlesnake Creek both have mapped floodplains, and the Clark Fork has flooded neighborhoods in big snowmelt years, so check the map on anything low in the valley. Wildfire smoke settles into the valley most summers, which slows crews and showings for a few weeks. Winter inversions and older wood stoves bring air quality rules into some remodels. Montana's 2023 housing bills pushed cities this size to allow accessory dwellings, which can change what a lot is worth, but those rules have been challenged in court, so confirm the current zoning with Development Services before you pay for it.
Who buys your finished Missoula deal
The finished Missoula house sells to university staff, health care workers and people moving from bigger Western cities, and that last group pays for character and walkability more than square footage. The exit is slower than it was, so price for a longer listing and expect some negotiation. A lot with room for an accessory unit can sell to a different buyer entirely. Rents are strong because of the university and the tight supply, so holding the house on a DSCR loan is a fair backup.
Your whole loan, in one portal
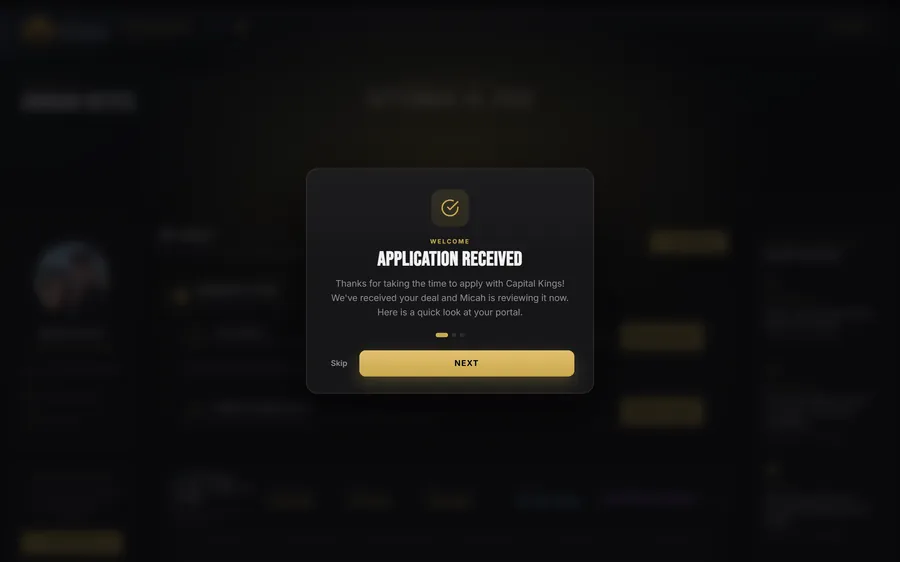
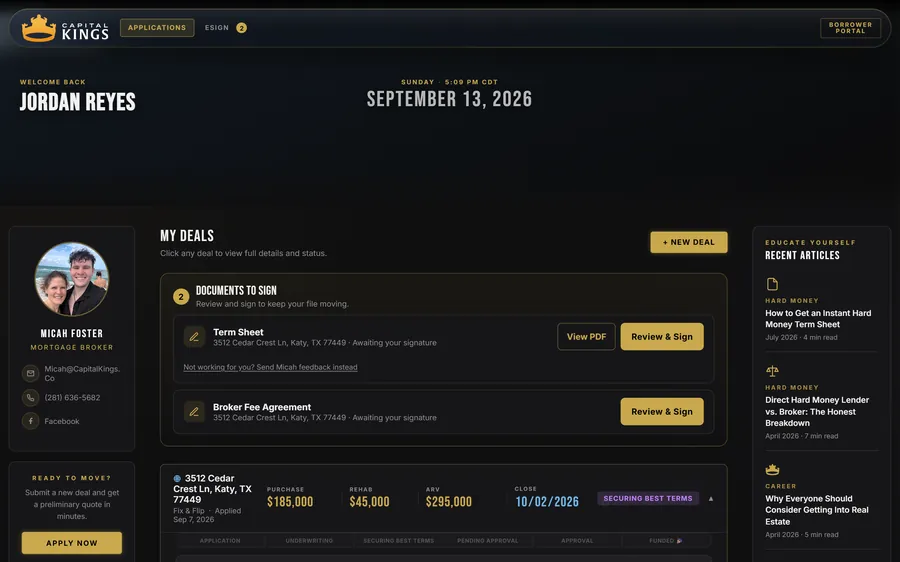
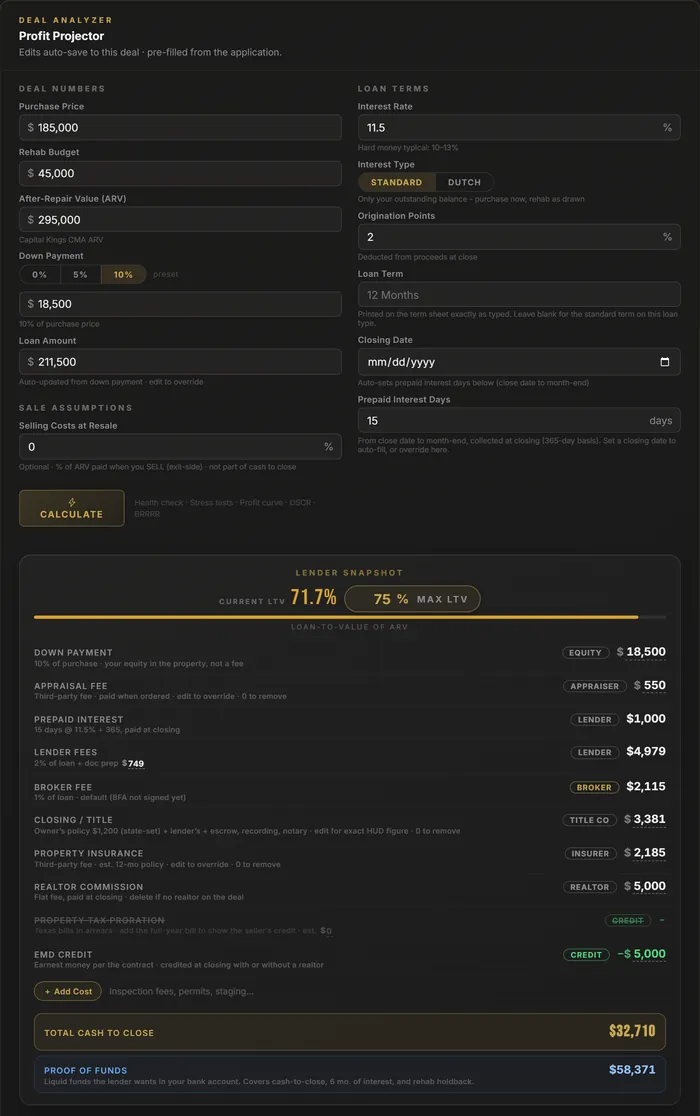
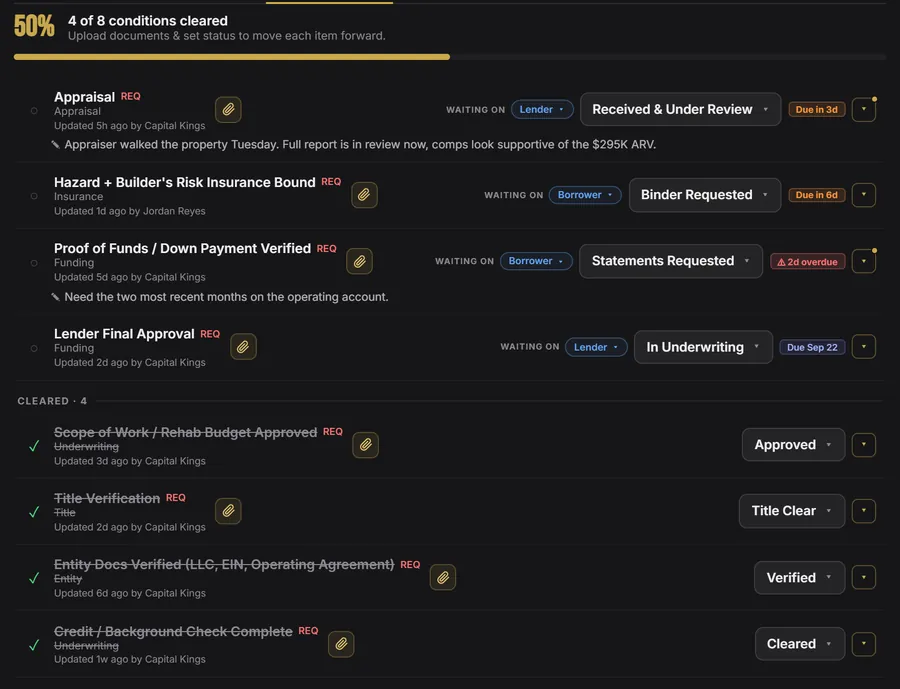
Apply once and the whole Missoula loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Missoula
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Missoula.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Missoula
We broker deals across the whole Missoula market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Montana, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Missoula hard money FAQ
Do you lend hard money in Missoula?
Which fix and flip programs apply in Missoula?
How fast can a Missoula hard money loan close?
How much do I need to bring to close on a Missoula flip?
Do you fund the rehab budget in Missoula?
What credit score do I need for a Missoula fix and flip loan?
Can I refinance a Missoula flip into a rental loan?
Is Missoula too expensive to flip?
Can I use a fix and flip loan in Missoula on my first deal?

Ready to fund your Missoula deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.