 Broker, not a lender
Hard Money Lenders inKansas City, Missouri
Fix and flip, DSCR rental and new construction financing for Kansas City investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Kansas City deal right now
Prefilled with a realistic Kansas City deal. Change any number and it reprices instantly on the lanes licensed in Missouri, using the same engine behind our term sheets.
Financing a deal in Kansas City
Kansas City, Missouri is one of the easiest big-city flip markets in the country to get a handle on: brick and frame houses from the 1910s through the 1950s, basements almost everywhere, and a buyer pool that has kept finished homes moving quickly even as prices flattened elsewhere. The city is also split by a state line, and that matters for financing. This page covers the Missouri side, where a first flip can be priced; the Kansas side of State Line Road runs on different programs.
The Kansas City deal turns on where you are relative to Troost and the river. South of Brush Creek, Waldo and the streets around Brookside carry the prices that make a full renovation pay, and a clean bungalow there sells to a young professional in days. The historic Northeast is where the cheap buys and the big old houses are, with real upside and real variance block by block. North of the river, the Northland is 1950s and 60s ranches and split-levels, simpler to renovate and easier to comp. Pick the sub-market first, then the house, because the same rehab budget produces very different ARVs a few miles apart.
What a Kansas City deal looks like on paper
Kansas City example: $170,000 purchase, $55,000 rehab, $310,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1940s Waldo bungalow: tuckpointing and a new roof, a kitchen, a second bath, a sewer lateral scope and a basement that stays dry. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$25,500
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,322
- Prepaid interest (15 days)Lender$778
- Property insuranceInsurer$2,138
- AppraisalAppraiser$550
Interest while you rehab: $1,143 a month on the $144,500 funded at closing, $1,578 once every draw is out. Proof of funds is cash to close plus $14,850 of rehab reserve and $9,466 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Kansas City
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Kansas City comps say
Redfin puts the Kansas City, Missouri median sale price at $310,000 for the three months ending August 2026, about 3% above a year earlier, with homes selling in around 19 days. Zillow’s home value index for the city is $253,549, up 1.7% over the year, with homes going pending in about 10 days. The Northeast shows the spread inside the city: Zillow puts Pendleton Heights at $236,771 and Scarritt Point at $147,772, while Columbus Park runs $326,274.
| Median sale price, Kansas City MO (Redfin, 3 months to Aug 2026) | $310,000 |
| Days on market, Kansas City MO (Redfin) | 19 |
| Zillow home value index, Kansas City MO (Aug 2026) | $253,549 |
| Zillow home value index, Pendleton Heights | $236,771 |
| Zillow home value index, Scarritt Point | $147,772 |
| Zillow home value index, Columbus Park | $326,274 |
Sources: Redfin, Kansas City MO housing market · Zillow, Kansas City MO home values · City of Kansas City, Healthy Homes Rental Inspection Program
How a Kansas City file actually gets priced
Appraisers in Jackson and Clay counties comp on closed sales inside the neighborhood and are skeptical of anything that jumps a known boundary, so a Brookside comp doesn’t carry a Marlborough house and a Northland ranch won’t borrow from Waldo. We set the ARV on sales from the last 90 days on the same side of the river, and we check days on market on each comp, because a comp that sat for two months tells you something about the ceiling. On the older brick stock we want the foundation, the sewer lateral and the electrical looked at before you close; clay-tile laterals and knob-and-tube wiring show up constantly in pre-war Kansas City houses.
Flooding follows the creeks here: Brush Creek, Indian Creek, the Blue River and Turkey Creek have all flooded neighborhoods in living memory, so pull the flood layer on anything low. The bigger practical issue is the city’s Healthy Homes Rental Inspection Program, in place since 2018, which requires every rental in Kansas City, Missouri to be registered and lets the city inspect and suspend a landlord’s permit over unresolved violations; if your flip ends as a rental, budget for that standard. Permits run through the city’s online permit system, and work inside a historic district needs landmarks review for exterior changes. Hail is the insurance story, so the roof age matters on every file.
Who buys your finished Kansas City deal
Most finished Kansas City houses sell to owner-occupants: young professionals and families in Waldo, Brookside-adjacent streets and Midtown, first-time buyers in the Northland and South KC, plus a steady flow of relocating buyers from Los Angeles, Denver and Chicago who think local prices are a bargain. Those buyers are active, so a well-priced house doesn’t wait long. The other exit is the rental. Kansas City rents hold up well against purchase prices, which is why so many investors hold here, and a DSCR refinance is a practical plan B on a Northeast or South KC house when the sale number comes in light.
Your whole loan, in one portal
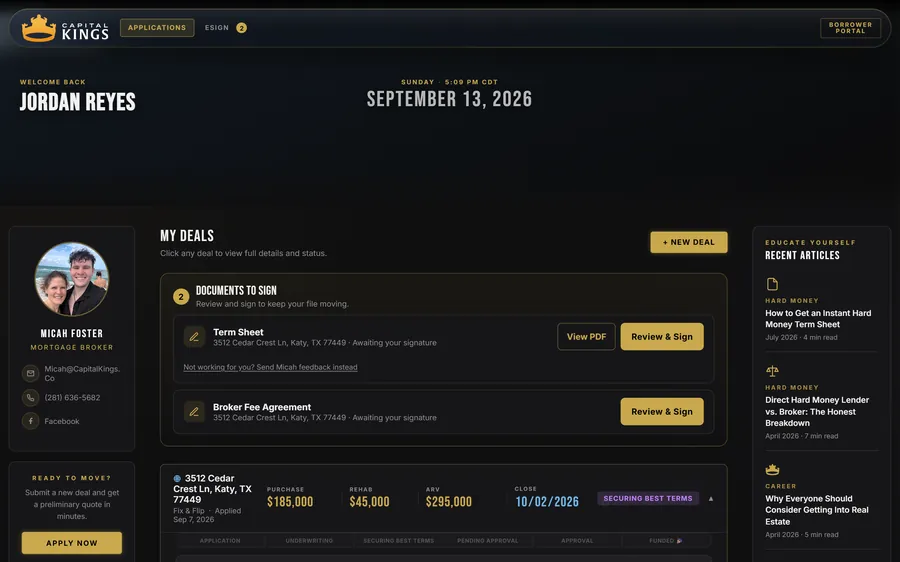
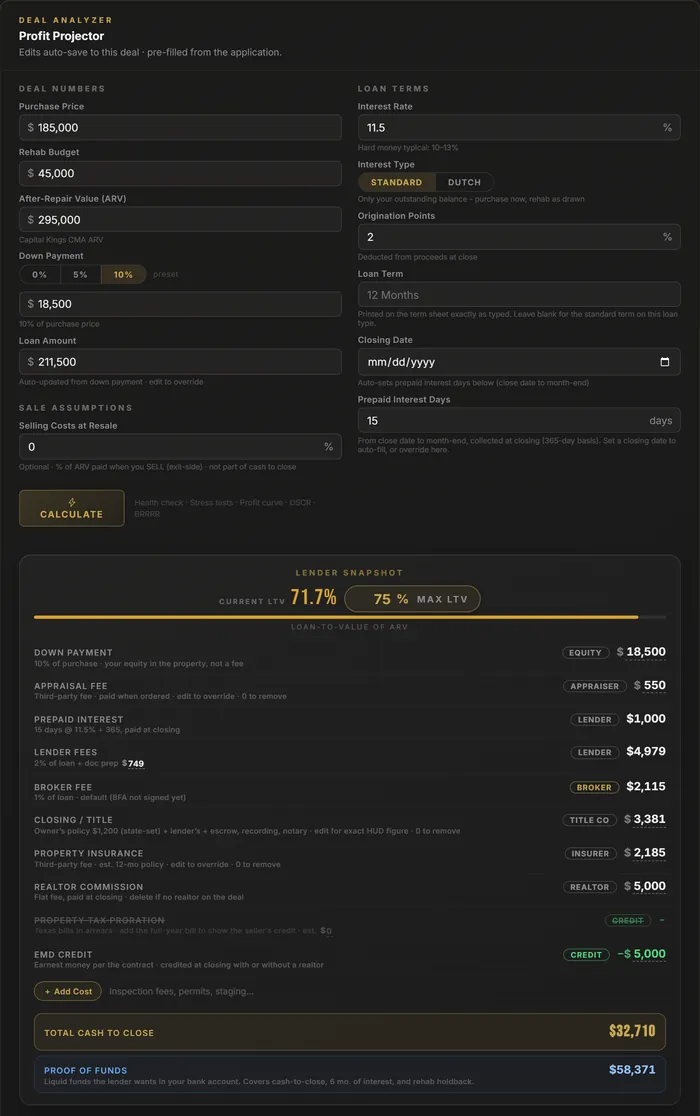
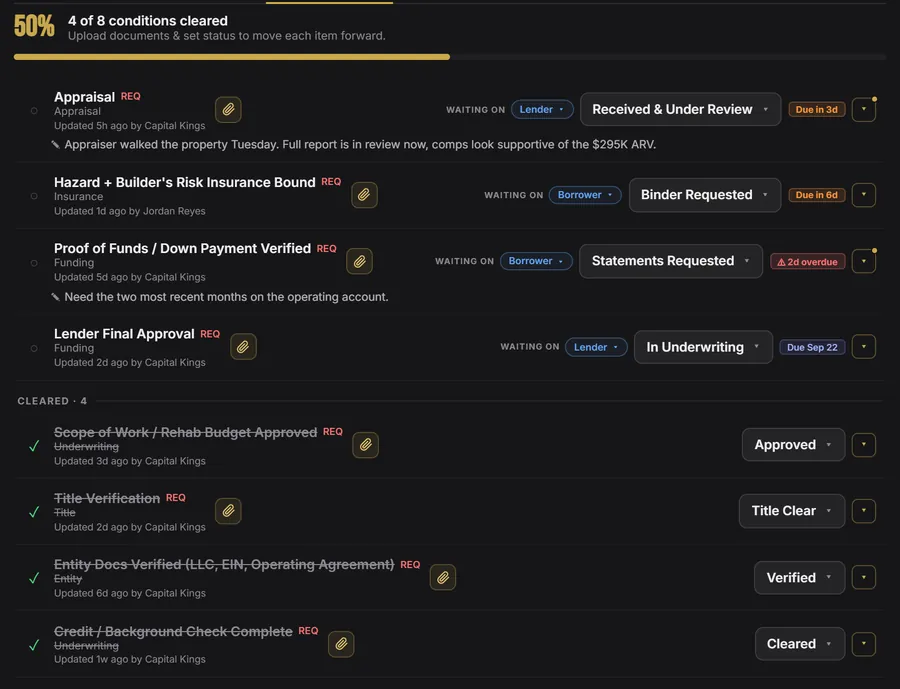
Apply once and the whole Kansas City loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Kansas City
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Kansas City.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Kansas City
We broker deals across the whole Kansas City market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Missouri, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Kansas City hard money FAQ
Do you lend hard money in Kansas City?
Which fix and flip programs apply in Kansas City?
How fast can a Kansas City hard money loan close?
How much do I need to bring to close on a Kansas City flip?
Do you fund the rehab budget in Kansas City?
What credit score do I need for a Kansas City fix and flip loan?
Can I refinance a Kansas City flip into a rental loan?
Can I finance a first flip in Kansas City, Missouri?
Does it matter whether the house is on the Missouri or Kansas side?
Do Kansas City rental rules affect a flip?

Before you sign anything
Ready to fund your Kansas City deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.