 Broker, not a lender
Hard Money Lenders inBoston, Massachusetts
Fix and flip, DSCR rental and new construction financing for Boston investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Boston deal right now
Prefilled with a realistic Boston deal. Change any number and it reprices instantly on the lanes licensed in Massachusetts, using the same engine behind our term sheets.
Financing a deal in Boston
Boston is an expensive place to flip, and that cuts both ways. Entry prices here would buy three houses in most of the country, so every month of carry costs real money, but the finished product sells into one of the deepest buyer pools in the Northeast. The single family flips we see sit on the southern edge of the city, in Hyde Park, Roslindale, Mattapan and West Roxbury, where the stock is 1900s to 1950s colonials and capes on small lots. Closer in, Dorchester and East Boston are mostly two and three family houses, and those deals are as often a hold as a sale.
What decides a Boston deal is the scope you are allowed to do, not the scope you want to do. A huge share of lots in the neighborhoods are nonconforming under the zoning code, so a dormer, a rear addition, a finished basement with a new egress or converting a two family to a single can mean a trip to the Zoning Board of Appeal, and that hearing calendar runs on months. Cosmetic and systems work goes through Inspectional Services on a short form permit and moves. If your profit needs added square footage, we price the file as if the relief takes a long time, because it usually does.
What a Boston deal looks like on paper
Boston example: $470,000 purchase, $95,000 rehab, $800,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1920s colonial in Hyde Park with the original kitchen, knob and tube in the attic and a tired porch, bought from an estate. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$70,500
- Origination (0.5%)Lender$2,473
- Doc prepLender$749
- Broker fee (1%)Broker$4,945
- Title and closingTitle$4,779
- Prepaid interest (15 days)Lender$1,929
- Property insuranceInsurer$5,368
- AppraisalAppraiser$550
Interest while you rehab: $3,159 a month on the $399,500 funded at closing, $3,911 once every draw is out. Proof of funds is cash to close plus $23,750 of rehab reserve and $23,464 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Boston
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Boston comps say
Redfin puts the Boston median sale price at $859,000 over the three months through August 2026, up 3.4% from a year earlier, with homes selling in about 26 days. Zillow’s typical home value for the city is $774,723 as of August 31, 2026, down 1.4% over the year. Redfin’s climate data, from First Street, rates Boston’s flood risk as severe: 14,691 properties, about 21% of the city, are likely to be severely affected over the next 30 years.
| Median sale price, Boston (Redfin, 3 months to Aug 2026) | $859,000 |
| Days on market, Boston (Redfin) | 26 |
| Homes sold in August 2026 (Redfin) | 1,613 |
| Zillow home value index, Boston (Aug 2026) | $774,723 |
| Share of properties at severe 30-year flood risk (First Street via Redfin) | 21% |
Sources: Redfin, Boston housing market · Zillow, Boston home values · Analyze Boston, Coastal Flood Resilience Overlay District · Mass.gov, smoke and CO requirements when selling a home
How a Boston file actually gets priced
Boston appraisals are comp dense, which helps. There are enough sales that an appraiser can stay inside the same neighborhood and the same style, so a Hyde Park colonial gets compared to Hyde Park colonials, not to a Roslindale Victorian or a West Roxbury split. Where files go wrong is the unit count: a two family priced like a condo conversion, or a single priced off the renovated condos two streets over. We set the value on the property as it will legally exist when you sell, with the permits you can actually pull, and we want the recent closed sales for that exact configuration.
Flood is a bigger Boston issue than out of town buyers expect. First Street data on Redfin puts about a fifth of the city’s properties at risk of severe flooding over the next 30 years, concentrated in East Boston, South Boston, Charlestown and the Dorchester waterfront, and the city’s Coastal Flood Resilience Overlay District adds review for work inside the mapped area. Then the paperwork: a rental needs to be registered with the city, a house built before 1978 with a child under six in it falls under the state lead law, and no Massachusetts sale closes without the fire department’s smoke and carbon monoxide certificate.
Who buys your finished Boston deal
A finished single family on the south side of the city sells to an owner occupant, usually a dual income household priced out of the inner neighborhoods and using a conventional or jumbo loan. That buyer is picky about condition and quick when a house is right. Two and three family houses in Dorchester and Mattapan sell to house hackers and small landlords, who pay for rent rolls and new systems more than for finishes, and a DSCR refinance is a real exit on those when the rents cover the note.
Your whole loan, in one portal
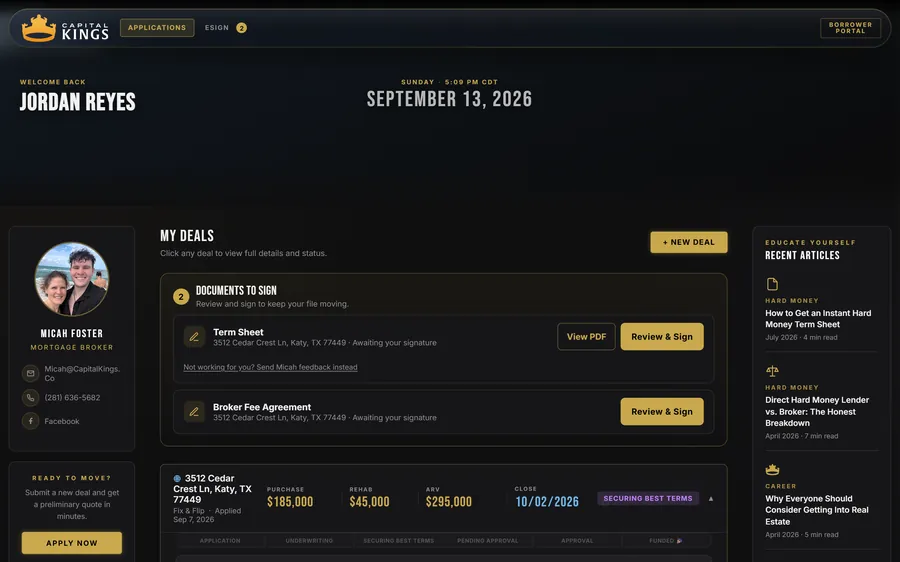
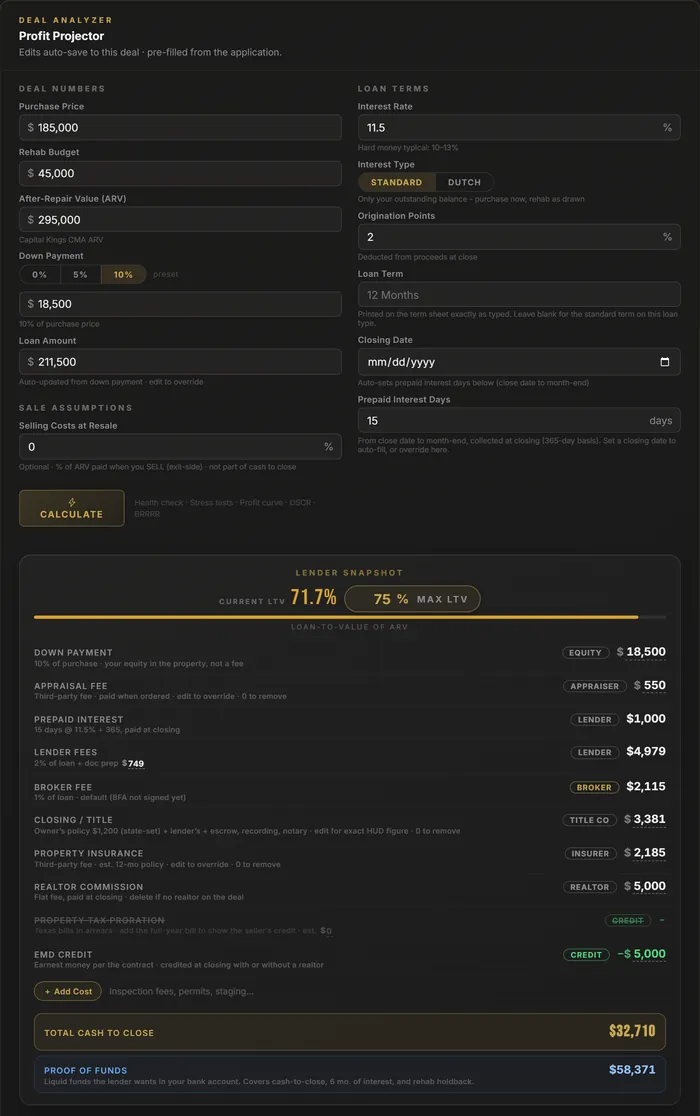
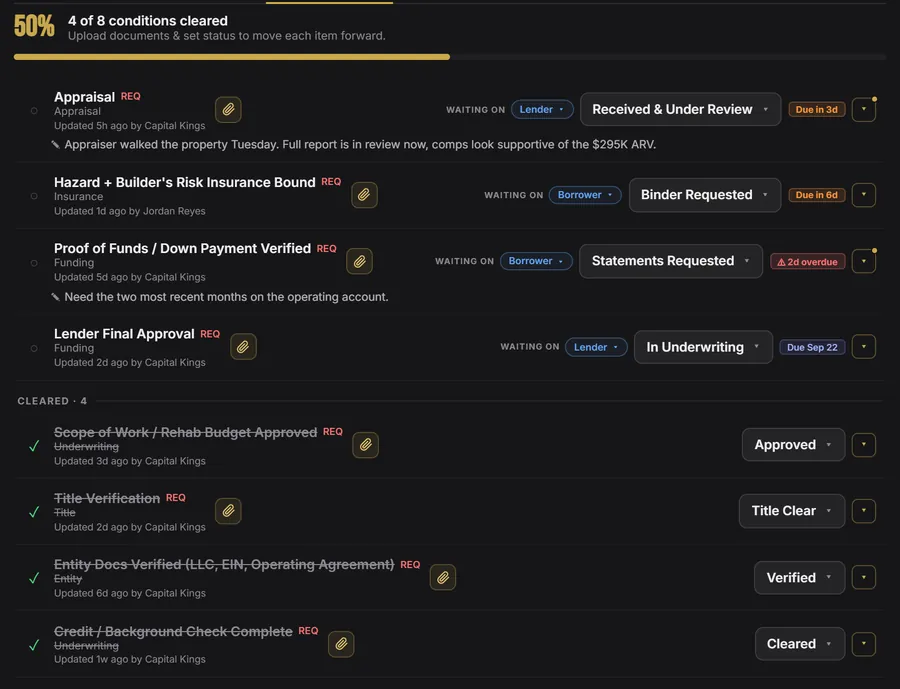
Apply once and the whole Boston loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Boston
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Boston.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Boston
We broker deals across the whole Boston market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Massachusetts, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Boston hard money FAQ
Do you lend hard money in Boston?
Which fix and flip programs apply in Boston?
How fast can a Boston hard money loan close?
How much do I need to bring to close on a Boston flip?
Do you fund the rehab budget in Boston?
What credit score do I need for a Boston fix and flip loan?
Can I refinance a Boston flip into a rental loan?
Can a first time flipper get a hard money loan in Boston?
Do I need Zoning Board of Appeal relief to renovate a Boston house?

Before you sign anything
Ready to fund your Boston deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.