 Broker, not a lender
Hard Money Lenders inDenver, Colorado
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Denver investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Denver deal right now
Prefilled with a realistic Denver deal. Change any number and it reprices instantly on the lanes licensed in Colorado, using the same engine behind our term sheets.
Financing a deal in Denver
Denver is an expensive city where the flips that still pencil live on the west and far northeast sides. Westwood, Barnum, Harvey Park and Mar Lee are full of 1950s brick ranches with basements, and Montbello is mostly 1970s and 80s tract houses. You won’t find cheap entry prices here, so the spread comes from buying a tired house well below the block and finishing it to what the street actually supports.
What decides a Denver deal is the basement and the sewer line. Most of the west side ranches sit on a full or garden-level basement, and finishing it (egress window, bedroom, bath) is where the square footage and the ARV jump. Just as often, the clay tile or Orangeburg sewer lateral under the yard is cracked or full of roots, and a scope before closing tells you whether you’re paying for a spot repair or a full replacement out to the main. Put both in the budget on day one and you’ll know if the deal works before you’re committed.
What a Denver deal looks like on paper
Denver example: $355,000 purchase, $65,000 rehab, $560,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1950s brick ranch in Harvey Park with an unfinished basement, original galley kitchen, a panel swap and a sewer line repair. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$53,250
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$3,668
- Title and closingTitle$4,148
- Prepaid interest (15 days)Lender$1,430
- Property insuranceInsurer$3,990
- AppraisalAppraiser$550
Interest while you rehab: $2,386 a month on the $301,750 funded at closing, $2,900 once every draw is out. Proof of funds is cash to close plus $17,550 of rehab reserve and $17,402 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Denver
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Denver comps say
Redfin puts the Denver median sale price at $619K for the three months ending August 2026, up 4.9% from a year earlier, with homes selling in about 28 days. Zillow’s average home value for Denver is $524,695, down 2.1% over the past year.
| Median sale price, Denver (Redfin, 3 months to Aug 2026) | $619K |
| Days on market, Denver (Redfin) | 28 |
| Zillow average home value, Denver (Aug 2026) | $524,695 |
Sources: Redfin, Denver housing market · Zillow, Denver home values · City and County of Denver, residential rental property license
How a Denver file actually gets priced
Denver ARVs are set block by block. A Harvey Park ranch and a Bear Valley ranch a mile apart can land in very different places, and an appraiser won’t pull a Sloan’s Lake comp into Barnum however close it looks on the map. We use closed sales from the same neighborhood inside roughly three months and pay attention to whether the basement in each comp was finished and permitted, because an unpermitted basement bedroom usually doesn’t count toward the room count. If the number needs the finished basement to hit, the permit has to be in the plan.
Three Front Range realities show up on Denver files. Expansive clay under a lot of the city heaves slabs and cracks basement walls, so a structural look at older foundations is worth the money. Colorado radon levels run high, and buyers here routinely test for it, so a mitigation system is a cheap line to include. And hail season hits roofs hard, which means insurers look closely at roof age. On the paperwork side, Denver has required a residential rental license since a 2021 ordinance, with an inspection to certify the house, so a hold plan needs that inspection on the calendar. Structural, electrical and basement work runs through the city’s Community Planning and Development permit process, which isn’t fast.
Who buys your finished Denver deal
The finished Denver ranch goes to a first-time or move-up buyer who’s priced out of the central neighborhoods and wants a yard and a garage. They’re comparing your house with suburban new builds in Aurora and Thornton, so the finish needs to look current and the mechanicals need to be clean on the inspection report. Price it against what closed on your street, not what’s listed. If you’d rather hold, Montbello and Westwood are where the rent gets closest to covering the payment, but the license and inspection are part of that plan.
Your whole loan, in one portal
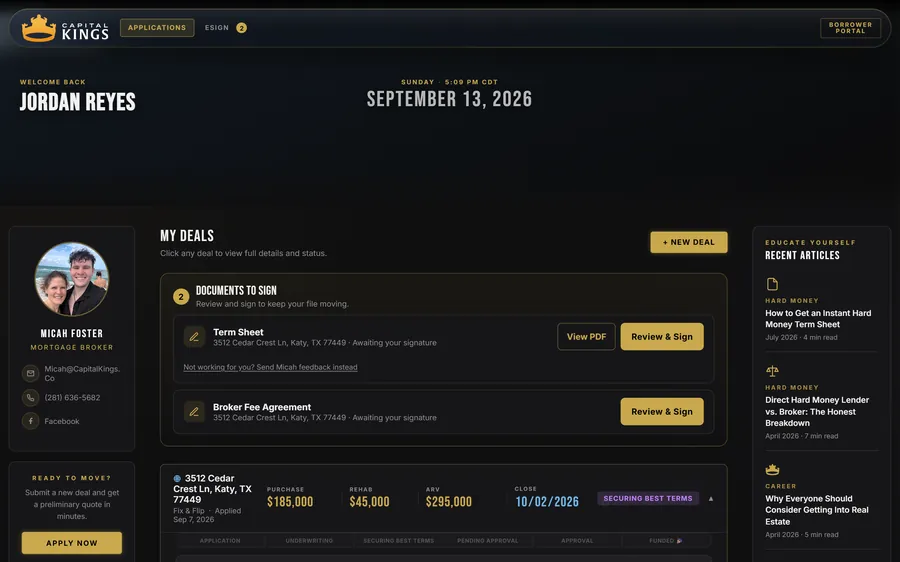
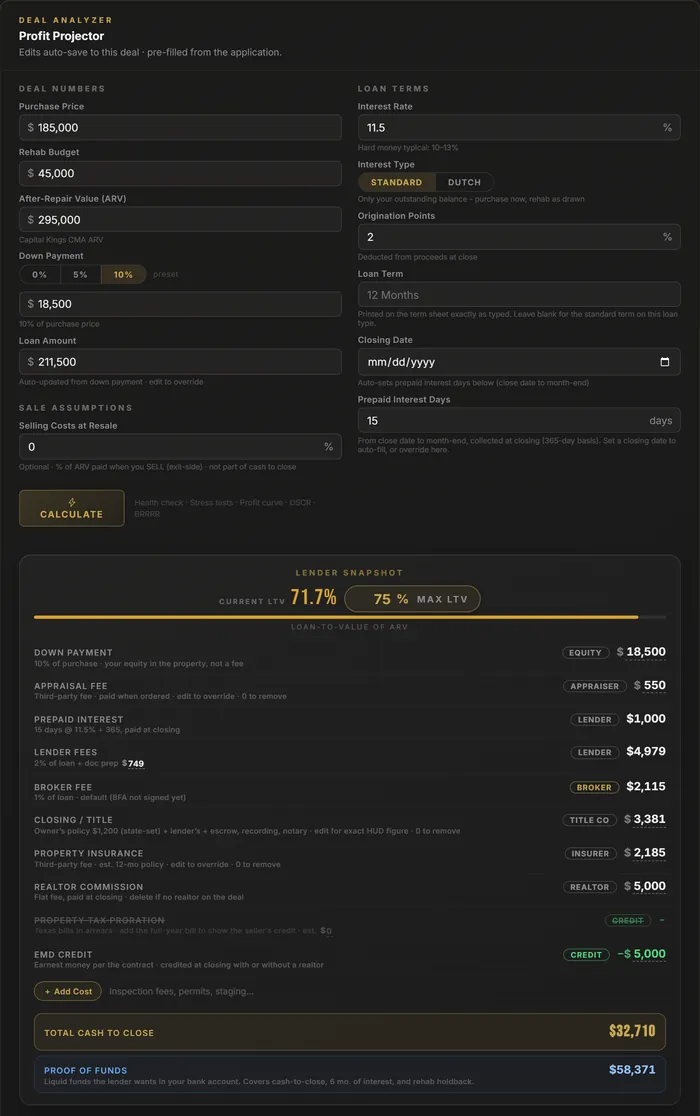
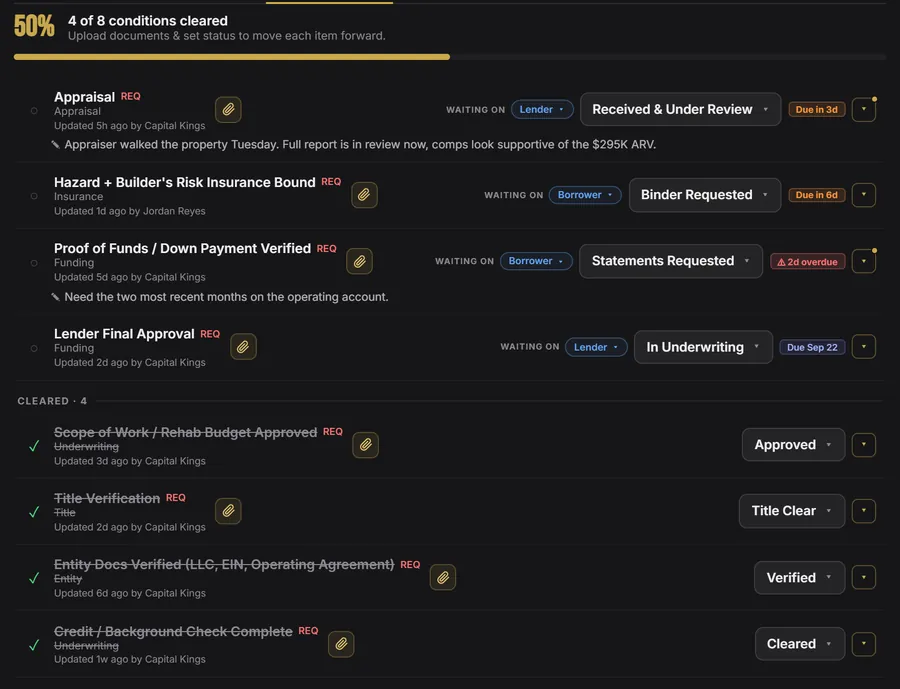
Apply once and the whole Denver loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Denver
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Denver.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Denver
We broker deals across the whole Denver market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Colorado, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Denver hard money FAQ
Do you lend hard money in Denver?
Which fix and flip programs apply in Denver?
How fast can a Denver hard money loan close?
How much do I need to bring to close on a Denver flip?
Do you fund the rehab budget in Denver?
What credit score do I need for a Denver fix and flip loan?
Can I refinance a Denver flip into a rental loan?
Should I finish the basement on a Denver flip?
Do I need a rental license if I hold a Denver flip instead of selling?

Before you sign anything
Ready to fund your Denver deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.