 Broker, not a lender
Hard Money Lenders inAurora, Colorado
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Aurora investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price an Aurora deal right now
Prefilled with a realistic Aurora deal. Change any number and it reprices instantly on the lanes licensed in Colorado, using the same engine behind our term sheets.
Financing a deal in Aurora
Aurora is the Denver metro’s value side, and the flips cluster in the oldest part of it. Original Aurora along East Colfax and Hoffman Heights, a neighborhood built in the early 1950s right off I-225, are small ranches on modest lots, a short drive from the CU Anschutz Medical Campus and Children’s Hospital. South and east, the 1970s and 80s subdivisions around Village East and Meadowood are split-levels and two-stories that need updating more than rescuing.
The Aurora deal comes down to which Aurora you’re in. Original Aurora and Hoffman Heights trade as entry-level houses, and the buyer is often a hospital worker or someone priced out of Denver proper, so a clean, efficient finish sells better than a luxury one. The 70s and 80s suburbs to the south are a different product: bigger houses, HOAs in places, and buyers who compare you to the new builds going up on the east edge of the city. Pick the right finish for the right side of town before you pick the countertops.
What an Aurora deal looks like on paper
Aurora example: $300,000 purchase, $55,000 rehab, $480,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a post-war Hoffman Heights ranch near the Anschutz campus: new roof, electrical, kitchen, bath and a finished addition that gets permitted properly. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$45,000
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$3,100
- Title and closingTitle$3,867
- Prepaid interest (15 days)Lender$1,209
- Property insuranceInsurer$3,373
- AppraisalAppraiser$550
Interest while you rehab: $2,017 a month on the $255,000 funded at closing, $2,452 once every draw is out. Proof of funds is cash to close plus $14,850 of rehab reserve and $14,710 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Aurora
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Aurora comps say
Redfin puts the Aurora median sale price at $450K for the three months ending August 2026, down 4.3% from a year earlier, with homes selling in about 32 days.
| Median sale price, Aurora (Redfin, 3 months to Aug 2026) | $450K |
| Days on market, Aurora (Redfin) | 32 |
| Year over year change in median (Redfin) | -4.3% |
Sources: Redfin, Aurora housing market · 9News, Hoffman Heights history
How an Aurora file actually gets priced
We comp Aurora houses inside their own subdivision and vintage, and an appraiser will do the same. A 1950s Hoffman Heights ranch doesn’t comp against a 1980s Meadowood two-story even if the square footage matches, and Denver sales across Yosemite don’t carry over either. Many of the older houses have had additions and garage conversions over the decades, so we check the permit history, since unpermitted square footage gets left out of the value. Closed sales from the last three months set the number.
Aurora shares the Front Range problems: clay soils that crack foundations and flatwork, high radon, and hail that shortens roof life. In older Original Aurora houses, expect outdated wiring, galvanized supply lines and sewer laterals that need scoping. In the newer subdivisions, HOA covenants can control exterior paint, fencing and roofing materials, so read the rules before you plan the exterior. Aurora has its own building division and its own water utility, separate from Denver, so budget for its permit timing and fees, not Denver’s.
Who buys your finished Aurora deal
The finished Aurora flip sells to a first-time buyer, a medical campus employee or a military family from Buckley Space Force Base, often with FHA or VA financing. That makes a clean inspection report and a sound roof non-negotiable. Out east, builders are selling new homes with rate buydowns, which caps what a resale flip can ask in the 80s subdivisions. Closer in, the Anschutz campus keeps rental demand steady, so a DSCR refinance is a practical Plan B on a Hoffman Heights or Original Aurora house.
Your whole loan, in one portal
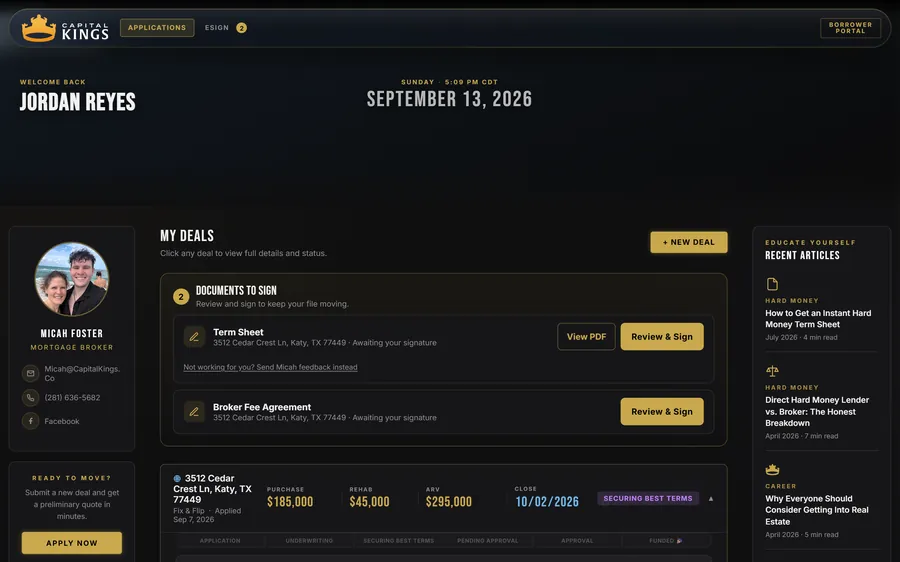
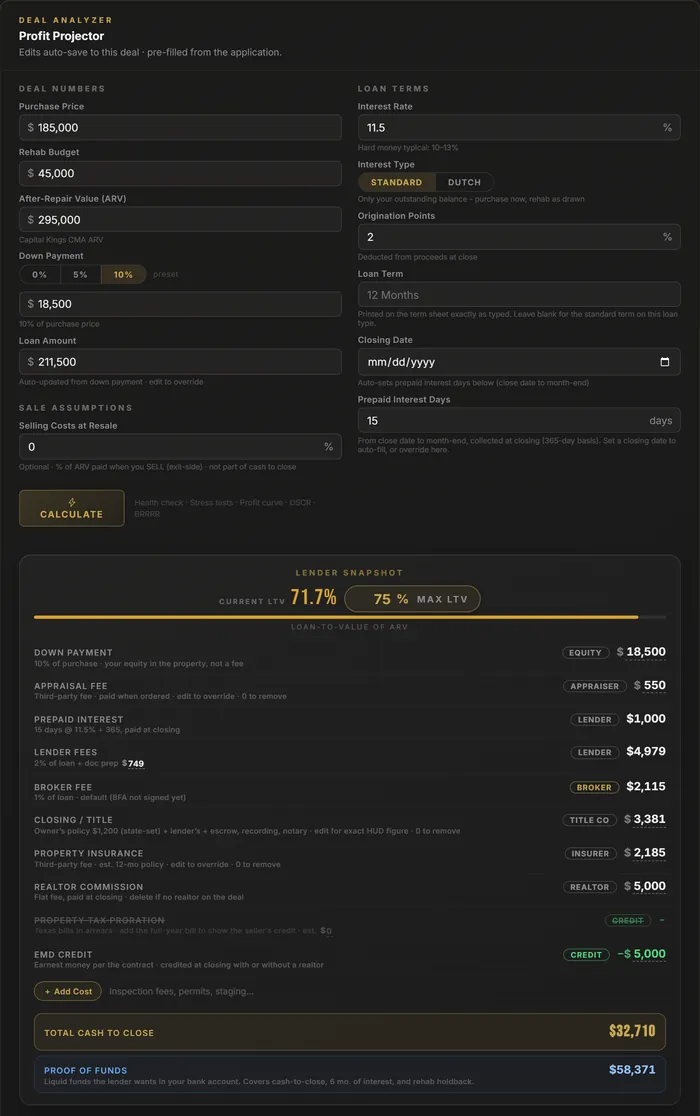
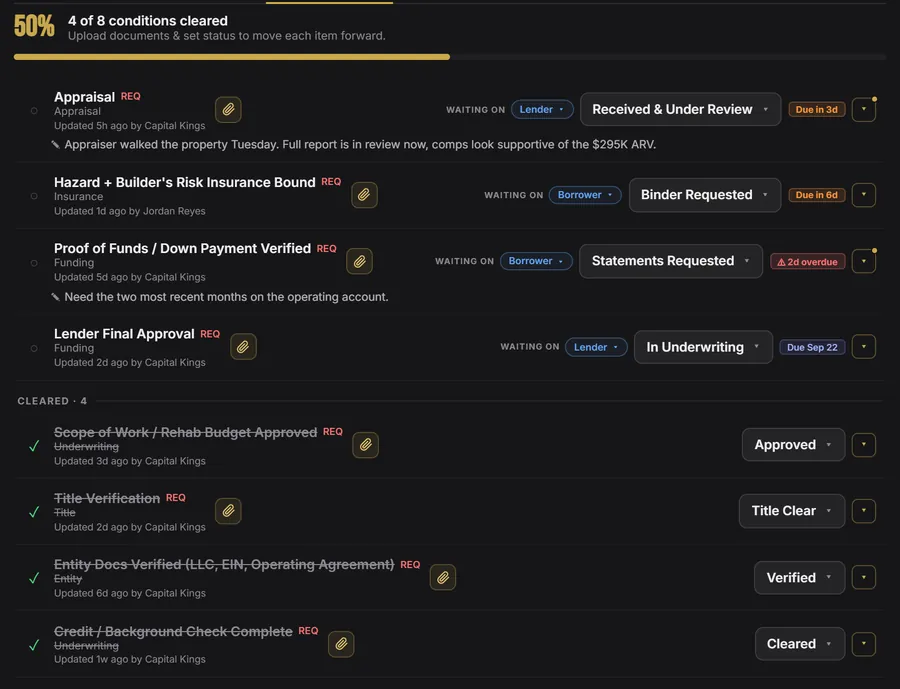
Apply once and the whole Aurora loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Aurora
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Aurora.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Aurora
We broker deals across the whole Aurora market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Colorado, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Aurora hard money FAQ
Do you lend hard money in Aurora?
Which fix and flip programs apply in Aurora?
How fast can an Aurora hard money loan close?
How much do I need to bring to close on an Aurora flip?
Do you fund the rehab budget in Aurora?
What credit score do I need for an Aurora fix and flip loan?
Can I refinance an Aurora flip into a rental loan?
Is Aurora a better flip market than Denver?
Do HOAs matter on an Aurora flip?

Before you sign anything
Ready to fund your Aurora deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.