 Broker, not a lender
Hard Money Lenders inWilmington, North Carolina
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Wilmington investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Wilmington deal right now
Prefilled with a realistic Wilmington deal. Change any number and it reprices instantly on the lanes licensed in North Carolina, using the same engine behind our term sheets.
Financing a deal in Wilmington
Wilmington is a coastal city with a port, a university and a film industry. UNCW, the hospital system, the port and a steady stream of retirees and remote workers keep the market moving. The flip stock is 1920s to 1950s houses near downtown and in Princess Place, and 1950s and 1960s ranches in Winter Park, Forest Hills and Pine Valley.
Storms set the Wilmington deal. Hurricane Florence flooded the region in 2018 and cut the city off for days, and buyers remember. Houses on higher ground with newer roofs and clean storm history sell faster and for more. We check the flood zone, the roof and the storm history before we agree on a value, and we price wind and flood insurance into your carry.
What a Wilmington deal looks like on paper
Wilmington example: $270,000 purchase, $70,000 rehab, $485,000 after repair value, 730 credit, first flip. The engine puts that borrower on the First Flip, 10% Down program at 9.99%. Picture a 1950s brick ranch in Winter Park with original baths, a closed kitchen, a carport and windows that need replacing. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (10% of purchase plus rehab)You$34,000
- Origination (2.13%)Lender$6,503
- Lender fees (flat)Lender$2,790
- Broker fee (1%)Broker$3,060
- Title and closing (estimate at Texas rates)Title$3,848
- Prepaid interest (15 days)Lender$1,256
- Property insuranceInsurer$3,230
- AppraisalAppraiser$550
Interest while you rehab: $1,965 a month on the $236,000 funded at closing, $2,547 once every draw is out. Proof of funds is cash to close plus $18,900 of rehab reserve and $15,285 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Wilmington
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| First Flip, 10% Down1 | 10% | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips4 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% and 2 to 3 points, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Wilmington prices sit right now
Before we price a Wilmington flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Wilmington median sale price at $465K for the three months ending September 2026, up 3.3% on a year earlier, with homes selling in around 55 days, up from 32. The median price per square foot is $255.
| Median sale price (Redfin) | $465K |
| Change from a year earlier | up 3.3% |
| Days on market (Redfin) | 55 |
| Median price per square foot | $255 |
Sources: Redfin, Wilmington housing market
How a Wilmington file actually gets priced
Selling times in Wilmington stretched this year, from about a month to almost two, so we use recent closed sales and how long they sat. Appraisers separate downtown, Midtown and the beach areas, and they won’t let a Wrightsville Beach sale price an in-town house. We pull renovated sales from the same neighborhood and the same flood zone.
Bradley Creek, Hewletts Creek and Burnt Mill Creek flood in heavy storms, so check each parcel. Wind and flood insurance near the coast is expensive. The historic district downtown has design review for exterior changes. Older houses bring termites and moisture under raised floors. A big rehab in a flood zone can trigger the substantial improvement rule.
Who buys your finished Wilmington deal
The finished Wilmington house sells to a retiree, a UNCW or hospital employee, or a family moving in from out of state. They ask about storms and insurance first, so a new roof and documented storm history help the sale. Near UNCW, a long-term rental on a DSCR loan works as a hold if the sale is slow.
Your whole loan, in one portal
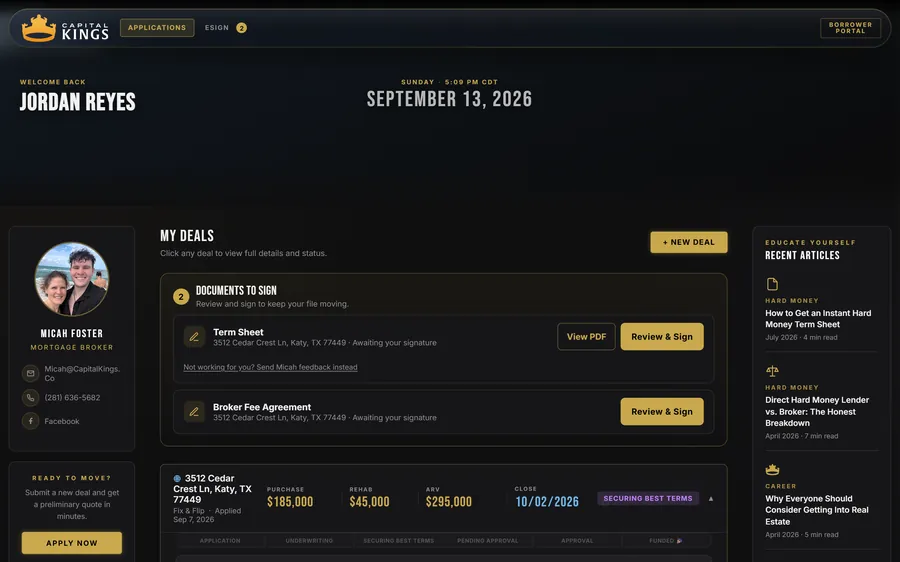
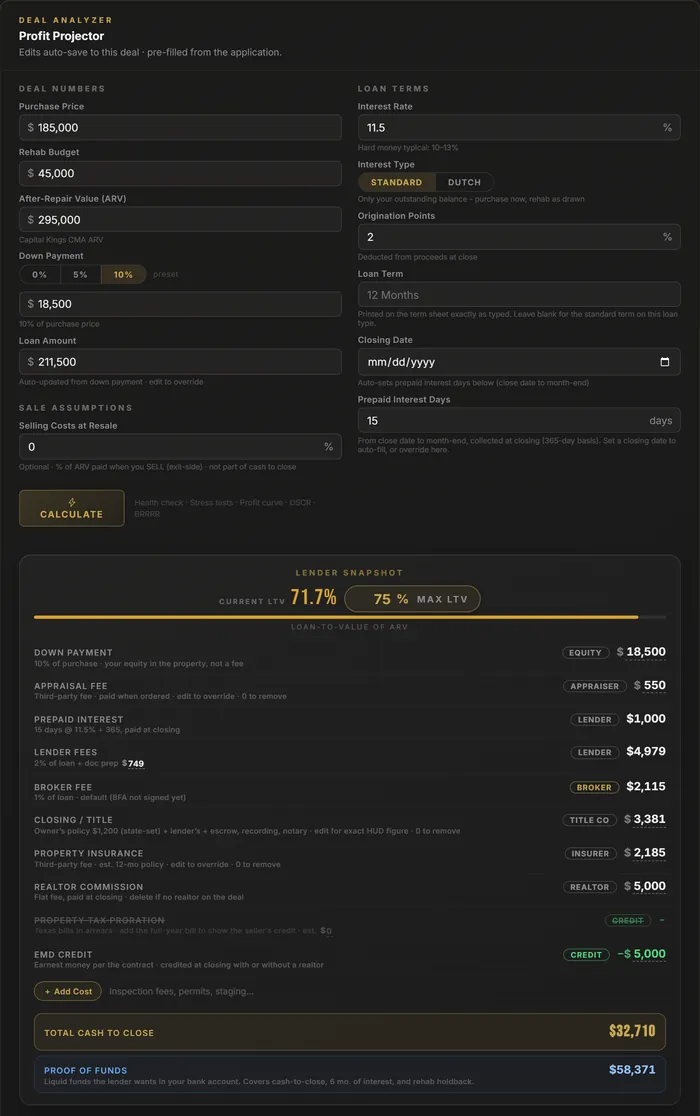
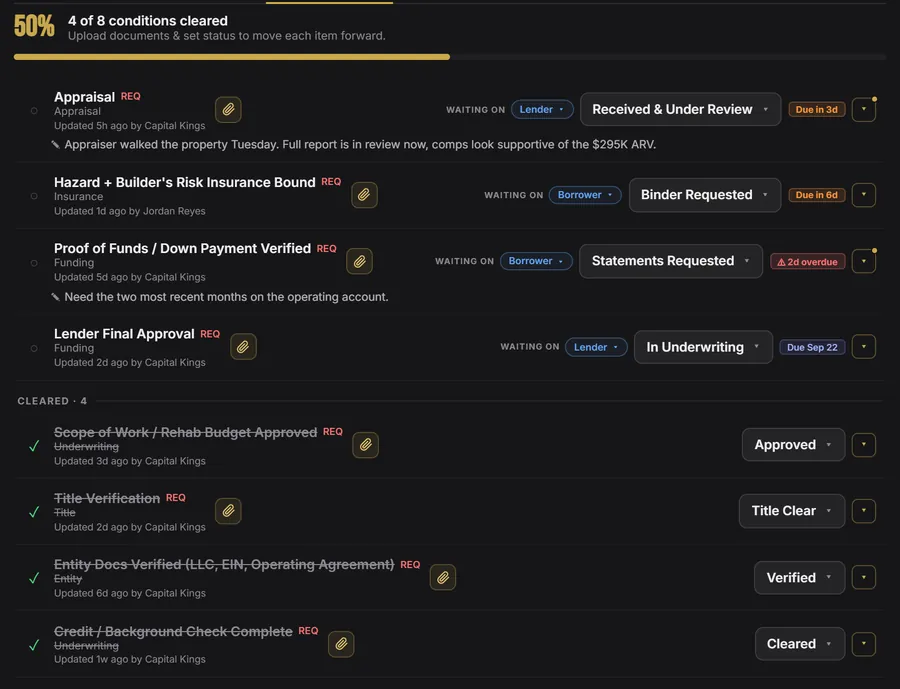
Apply once and the whole Wilmington loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Wilmington
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Wilmington.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Wilmington
We broker deals across the whole Wilmington market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in North Carolina, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
As little as 72 hours on the fastest program, 7-30 days on the others. We stay on title and the lender through funding.
Wilmington hard money FAQ
Do you lend hard money in Wilmington?
Which fix and flip programs apply in Wilmington?
How fast can a Wilmington hard money loan close?
How much do I need to bring to close on a Wilmington flip?
Do you fund the rehab budget in Wilmington?
What credit score do I need for a Wilmington fix and flip loan?
Can I refinance a Wilmington flip into a rental loan?
How much does storm history matter on a Wilmington flip?
Do Wrightsville Beach or Carolina Beach sales count for a Wilmington flip?

Before you sign anything
Ready to fund your Wilmington deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.