 Capital Kings LLC · Non-QM Mortgage Broker
Hard Money Lenders inSpokane, Washington
Fix and flip, DSCR rental and new construction financing for Spokane investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Price a Spokane deal right now
Prefilled with a realistic Spokane deal. Change any number and it reprices on the programs that lend in Washington, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Spokane
Spokane is the affordable end of Washington and a real flip market in its own right, with prices far below the west side and a housing stock that is mostly early 1900s bungalows and post-war ranches with basements. Gonzaga, the hospital district and Fairchild Air Force Base keep renters and buyers coming, and people moving from Seattle and California have added a layer of demand. The north side neighborhoods are where most flips happen; the South Hill is the premium market.
The Spokane flip is decided by the basement and the heating. Almost every older house here has a full basement, and whether it's dry, how tall it is and whether it can legally hold a bedroom decides how much square footage you can sell. Winters are cold and snowy, so a buyer's inspector looks closely at the furnace, the roof and the insulation. Houses that are priced right still move quickly here, so a finished product that looks after those three things sells.
What a Spokane deal looks like on paper
Spokane example: $215,000 purchase, $55,000 rehab, $360,000 after repair value, 700 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Say a 1910s Hillyard bungalow with a full basement: new furnace, rewiring, a kitchen, a bath, and a radon system before listing. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$32,250
- Origination (0.5%)Lender$2,000
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$2,378
- Title and closing (estimate at Texas rates)Title$3,510
- Prepaid interest (15 days)Lender$713
- Property insuranceInsurer$2,565
- AppraisalAppraiser$550
Interest while you rehab: $1,445 a month on the $182,750 funded at closing, $1,880 once every draw is out. Proof of funds is cash to close plus $14,850 of rehab reserve and $11,281 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
Fix and flip programs in Spokane
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% of purchase | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| First Flip, 10% Down1 | 10% of purchase + rehab | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% of purchase + rehab | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% of purchase | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips4 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
- Rate 9.99% with 2% to 2.25% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% with 1.5% to 1.75% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% with 2% to 3% origination, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on most programs (a few lenders set a higher one, noted above) and our broker fee is 1% with a $2,000 minimum and a $10,000 maximum. These are the numbers our term sheets use as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Spokane prices sit right now
Before we price a Spokane flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Spokane median sale price at $375,000 for the three months ending August 2026, down 1.7% from a year earlier, with homes selling after 22 days on the market on average.
| Median sale price, Spokane (Redfin, 3 months to Aug 2026) | $375,000 |
| Change from a year earlier (Redfin) | -1.7% |
| Average days on market, Spokane (Redfin) | 22 |
Sources: Redfin, Spokane housing market
How a Spokane file actually gets priced
We comp Spokane inside the same neighborhood and the same side of the river, because the South Hill premium doesn't carry to Hillyard or West Central. The appraiser separates above-grade and basement square footage, and a basement bedroom without proper egress won't count as one. We use recent closings, and on the older bungalows we want a sewer scope and a look at the foundation, since rubble and early concrete foundations are common north of downtown.
Spokane sits in a high radon area, and buyers here test for it, so budget a mitigation system on a basement house. Wildfire smoke is a summer fact and the wildland edges on the city's fringe carry insurance questions. Snow load and ice damming punish old roofs. The city has loosened its zoning to allow more middle housing types on residential lots, which can change what a corner or alley lot is worth, and permits run through the city's Development Services Center.
Who buys your finished Spokane deal
A finished Spokane house under the city median sells to first-time buyers, hospital staff, military families from Fairchild and newcomers from the west side who think it's a bargain. That last buyer expects updated systems and a finished basement done right. The South Hill supports higher prices for character homes. Rents are solid near Gonzaga and the medical district, so a lot of north side flips can refinance into a DSCR rental if the sale market slows.
What happens after you apply
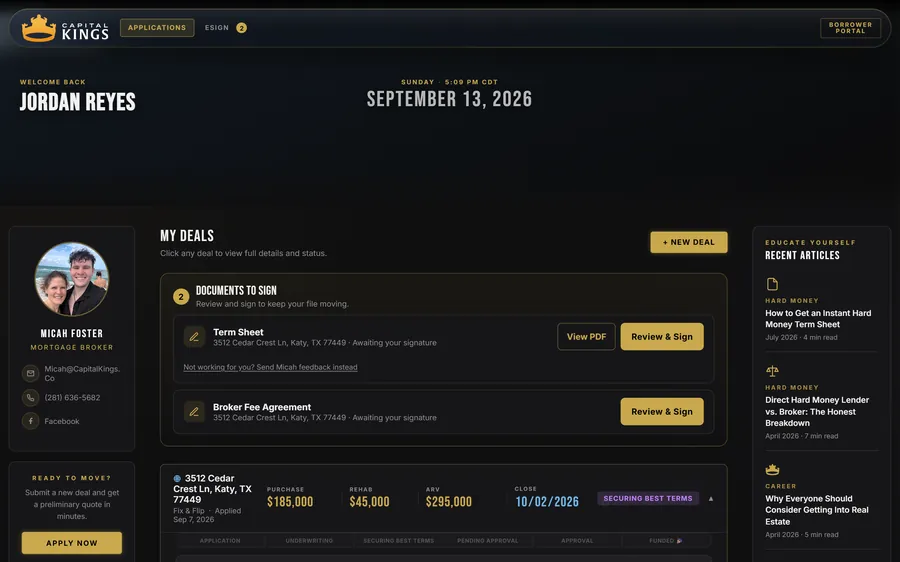
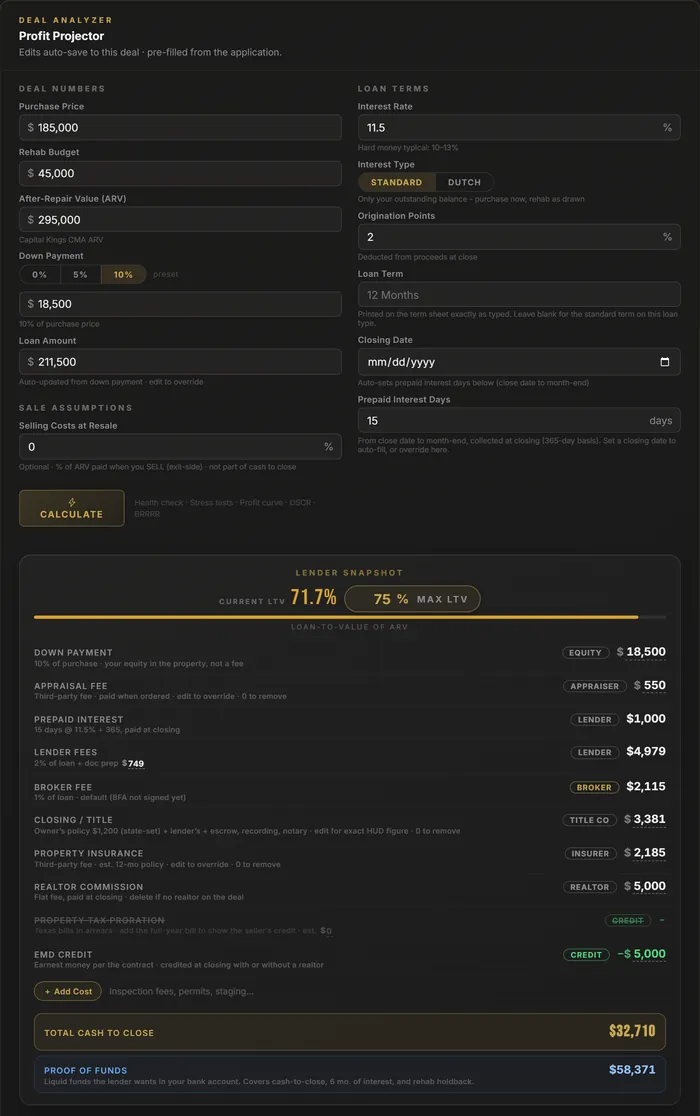
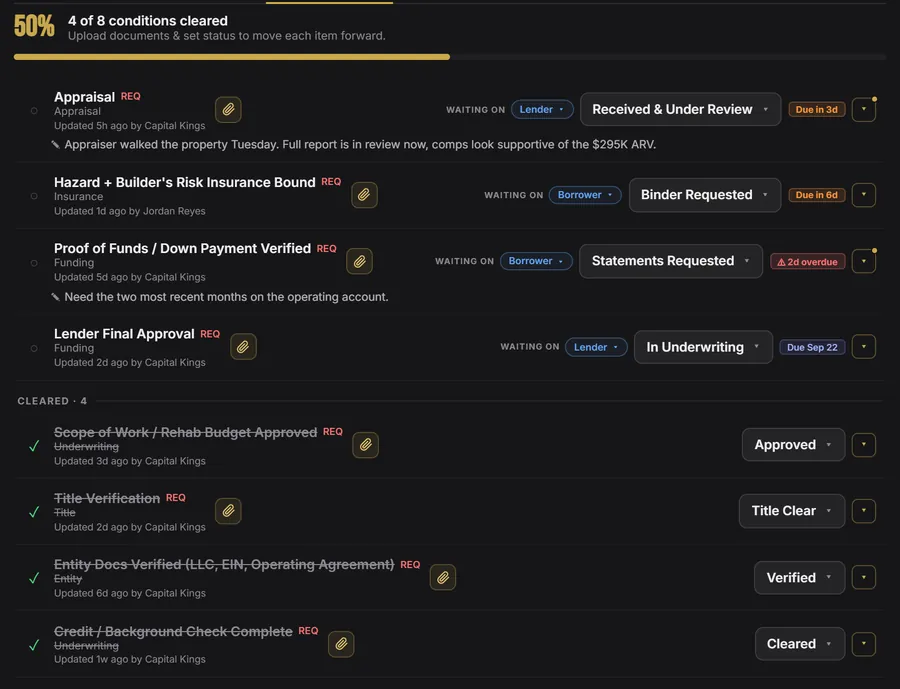
Apply once and the whole Spokane loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
The full walkthrough is on how it works, and you can tour the borrower portal before you apply.
What we fund in Spokane
Fix and flip
- Rates
- from 8.99% at 760+ credit
- With experience
- 0% down with 2+ completed flips, purchase plus rehab under 70% of ARV
- Rehab
- 100% funded, paid in draws
Rental (DSCR)
- Qualify on
- the rent, no W-2s or tax returns
- Down
- from 20% at 700+ credit
- Good for
- buy-and-hold, and the refinance when a flip becomes a rental
New construction
- Rates
- from 8.49% with 5+ completed builds
- First build
- 85% of cost with a GC who has 5+ builds
- Builds
- single family to small multifamily
Where we lend in Spokane
We broker deals across the whole Spokane market. The submarkets investors ask us about most are Hillyard (99207), Emerson-Garfield and the Northwest (99205), Logan and East Central (99202), West Central (99201), Shadle and Audubon (99205), South Hill (99203 / 99223) and Nevada Heights (99208 / 99207).
How long does a Spokane loan take to fund?
You send the address, purchase price, rehab budget and your ARV, which takes about five minutes and no credit pull. We take it to the lenders in our network that fit it and are licensed in Washington, and the rate, origination, leverage and cash to close come back side by side. 5-14 days to fund. We stay on title and the lender through funding.
Spokane hard money FAQ
Do you lend hard money in Spokane?
Which fix and flip programs apply in Spokane?
How fast can a Spokane hard money loan close?
How much do I need to bring to close on a Spokane flip?
Do you fund the rehab budget in Spokane?
What credit score do I need for a Spokane fix and flip loan?
Can I refinance a Spokane flip into a rental loan?
Is Spokane a good city for a first flip?
Does a finished basement count toward the ARV in Spokane?
What to read before you sign a term sheet
- Points, fees & rate: how to compare hard money lenders
- How construction draws and the rehab holdback actually work
- Dutch vs standard interest: what it really costs you
- Cash to close on a flip: the number most investors miss
Hard money near Spokane: Seattle and Tacoma. More Washington city guides: Bellevue, Kent and Vancouver. Or see everything we fund in Washington.
Ready to fund your Spokane deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.