 Broker, not a lender
Hard Money Lenders inLexington, Kentucky
Fix and flip, DSCR rental and new construction financing for Lexington investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Lexington deal right now
Prefilled with a realistic Lexington deal. Change any number and it reprices instantly on the lanes licensed in Kentucky, using the same engine behind our term sheets.
Financing a deal in Lexington
Lexington flips like a supply-constrained college and hospital town, because that’s what it is. Fayette County has drawn a hard line around where the city can grow since the 1950s, the Urban Service Boundary, and the horse farms on the other side of it aren’t getting subdivided. That keeps the older housing inside the line in demand. The flippable stock is the brick ranches and Cape Cods of the 1940s through the 60s on the north and east side, and the bungalows closer to downtown.
The Lexington deal is decided by scarcity cutting both ways. Buyers compete for anything move-in ready under the city median, so a well-finished ranch in Castlewood, Meadowthorpe or Southland doesn’t sit long. But you’re competing for the purchase with every other investor who knows the same thing, and that squeezes the buy. The council approved a 2,800 acre expansion of the boundary in November 2023, and the new areas will take years to build out, so the pressure on the existing stock isn’t going away soon. And because the Kentucky programs want completed flips, this is a market for investors who’ve already finished a few.
What a Lexington deal looks like on paper
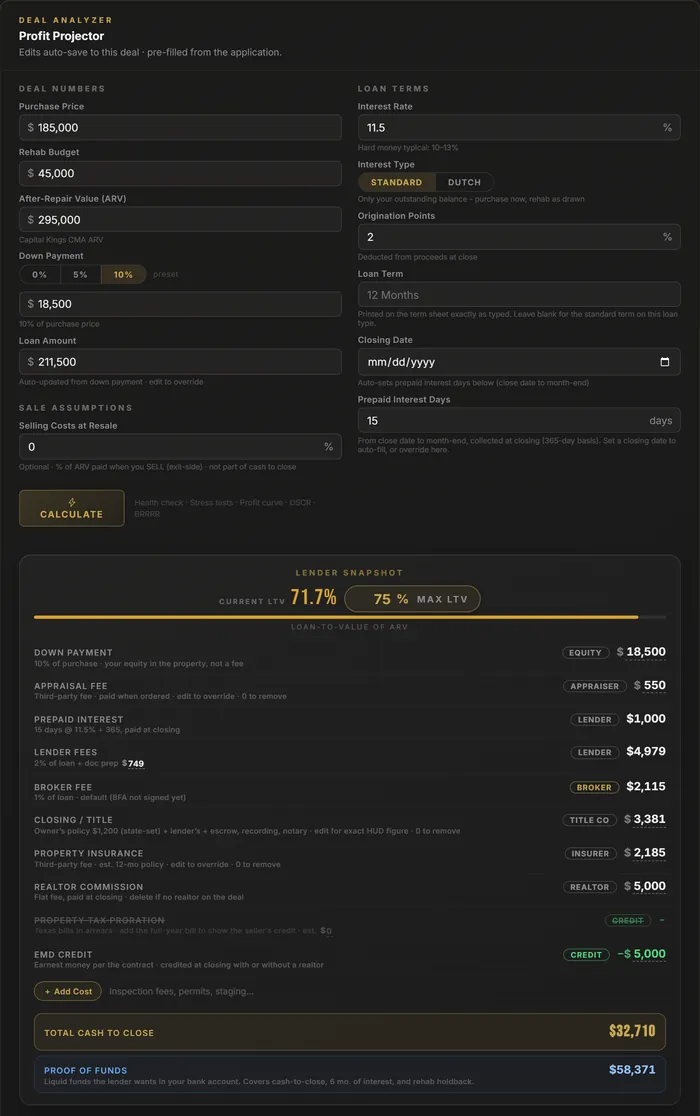
Lexington example: $175,000 purchase, $50,000 rehab, $305,000 after repair value, 730 credit, 4 to 10 flips completed. The engine puts that borrower on the 5% Down, 3+ Flips program at 11.00%. Think a 1950s brick ranch near Castlewood Park in 40505 with a dated kitchen, one bath, original windows and a tired HVAC system. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (5%)You$8,750
- Origination (2%)Lender$4,325
- Doc prepLender$749
- Broker fee (1%)Broker$2,163
- Title and closingTitle$3,404
- Prepaid interest (15 days)Lender$978
- Property insuranceInsurer$2,138
- AppraisalAppraiser$550
Interest while you rehab: $1,524 a month on the $166,250 funded at closing, $1,982 once every draw is out. Proof of funds is cash to close plus $13,500 of rehab reserve and $11,894 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Lexington
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Experienced Investor Rate1 | 15% | 680+ | 2+ completed flips | 9.00% | 0.75% | 75% of ARV | 12-24 months | 7-14 days |
| 5% Down, 3+ Flips2 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips3 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Rate and origination are the program floor; two completed projects in the last 36 months preferred.
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Lexington comps say
Redfin puts the Lexington median sale price at $365,000 for the three months ending August 2026, up 4.2% from a year earlier, with homes selling in about 34 days. Zillow’s home value index for the city is $333,115, up 3.4%. In 40505 on the north and east side, where our example sits, Redfin’s median is $259,000, up 7.1%.
| Median sale price, Lexington (Redfin, 3 months to Aug 2026) | $365,000 |
| Days on market, Lexington (Redfin) | 34 |
| Zillow home value index, Lexington (Aug 2026) | $333,115 |
| Median sale price, 40505 (Redfin) | $259,000 |
Sources: Redfin, Lexington housing market · Zillow, Lexington home values · Redfin, 40505 housing market · CivicLex, the Urban Service Boundary
How a Lexington file actually gets priced
Appraisers in Lexington price by neighborhood identity more than by ZIP, and the lines are sharp. Kenwick and Bell Court carry a premium over blocks a few streets east, and the campus-adjacent streets behave like a rental market rather than an owner-occupant one. We want comps from the same named neighborhood, closed in the last 90 days, with matching bedroom count and basement or no basement. The finished ranch with a second full bath is the product that appraises cleanly; a two-bedroom, one-bath with no parking has a lower ceiling than its square footage suggests.
Lexington sits on the Inner Bluegrass limestone, and that karst ground means sinkholes and settling show up in inspections more than people expect, so look hard at the foundation and the yard grade. Most of the flip stock predates 1978, so plan for lead-safe practices, and the 1950s houses often still have original galvanized supply lines. Structural, electrical, plumbing and HVAC work goes through the Lexington-Fayette Urban County Government’s building inspection division. In the H-1 historic overlay neighborhoods, Bell Court, South Hill, Northside and Gratz Park among them, exterior changes like windows, siding and porches need Board of Architectural Review sign-off first.
Who buys your finished Lexington deal
The finished Lexington house sells to University of Kentucky and UK HealthCare staff, the Toyota plant commute up in Georgetown, and a steady stream of first-time buyers priced out of the south-end subdivisions. Owner-occupants pay for a second bath, a fenced yard and off-street parking. Near campus, the buyer is often a landlord, and the price is set by what it rents for, so those houses are usually better held. Pricing both exits before you pick a scope keeps you from over-building a rental.
Your whole loan, in one portal
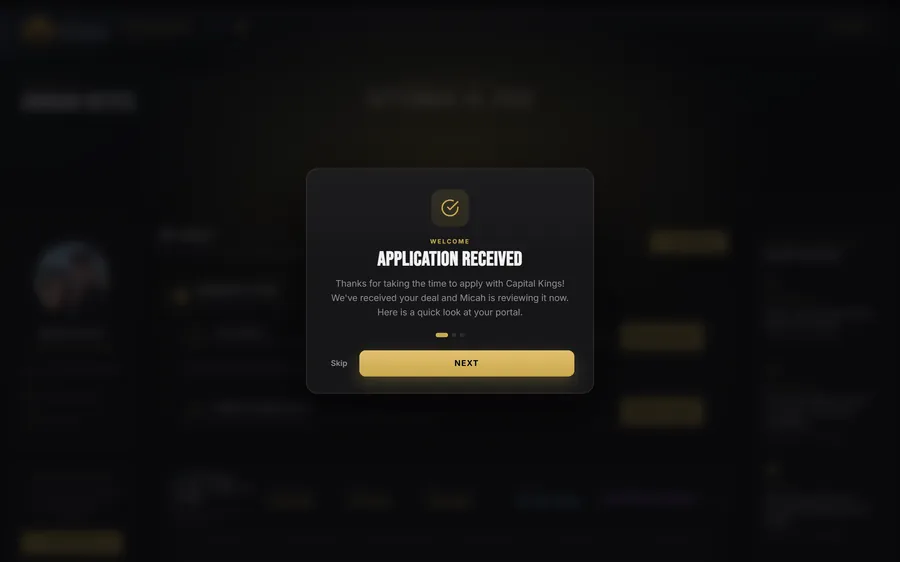
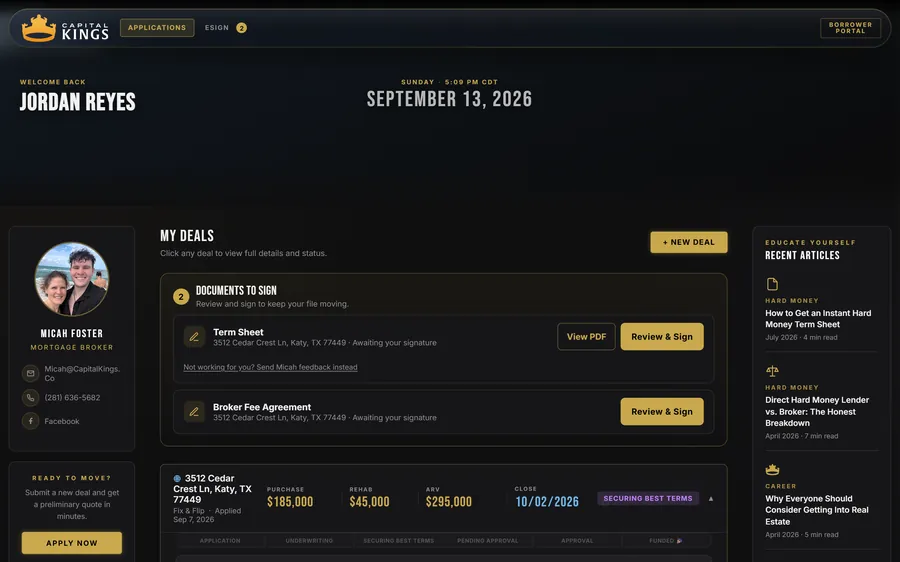
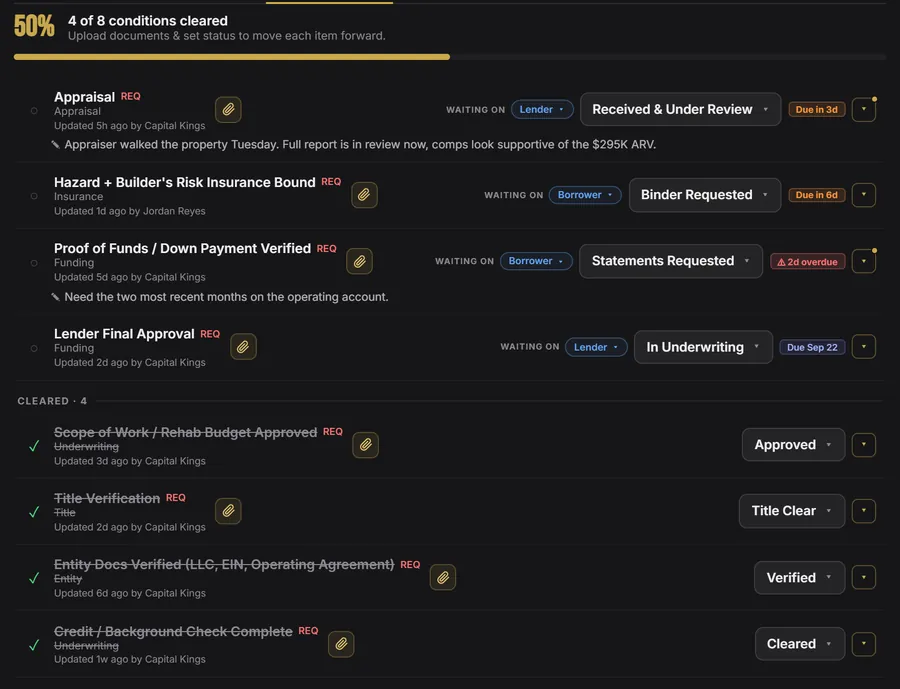
Apply once and the whole Lexington loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Lexington
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Lexington.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Lexington
We broker deals across the whole Lexington market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Kentucky, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Lexington hard money FAQ
Do you lend hard money in Lexington?
Which fix and flip programs apply in Lexington?
How fast can a Lexington hard money loan close?
How much do I need to bring to close on a Lexington flip?
Do you fund the rehab budget in Lexington?
What credit score do I need for a Lexington fix and flip loan?
Can I refinance a Lexington flip into a rental loan?
Why does the Lexington example assume I’ve done flips before?
Does the Urban Service Boundary change how I should flip in Lexington?

Before you sign anything
Ready to fund your Lexington deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.