 Broker, not a lender
Hard Money Lenders inHonolulu, Hawaii
Fix and flip, DSCR rental and new construction financing for Honolulu investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Honolulu deal right now
Prefilled with a realistic Honolulu deal. Change any number and it reprices instantly on the lanes licensed in Hawaii, using the same engine behind our term sheets.
Financing a deal in Honolulu
Honolulu is a non-standard market for most national lenders, and we would rather say that up front. Many programs that lend coast to coast leave Hawaii out, and the ones that stay look hard at the property, the tenure and the borrower. It's also a market of two halves: the median sale price across the city is pulled down by condos, while a single-family house on Oahu sells for well over a million. Flips here are almost always single-family homes, and they carry big balances.
The Honolulu flip is decided by the paperwork on the land and what's eating the wood. Check first whether the house is fee simple or leasehold, because a leasehold house with a short lease left is a very different asset and many lenders won't touch it. Then check for termites. Formosan subterranean termites are everywhere on Oahu, and many older homes are single-wall construction with no framing inside the walls, so the damage can be structural and the fix can be a partial rebuild. Budget both before you negotiate.
What a Honolulu deal looks like on paper
Honolulu example: $850,000 purchase, $130,000 rehab, $1,350,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1950s single-wall Kalihi Valley house, fee simple: termite repair, new electrical, a kitchen and baths, and a sewer lateral check before listing. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$127,500
- Origination (0.5%)Lender$4,263
- Doc prepLender$749
- Broker fee (1%)Broker$8,525
- Title and closingTitle$6,547
- Prepaid interest (15 days)Lender$3,325
- Property insuranceInsurer$9,310
- AppraisalAppraiser$550
Interest while you rehab: $5,714 a month on the $722,500 funded at closing, $6,742 once every draw is out. Proof of funds is cash to close plus $26,000 of rehab reserve and $40,451 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Honolulu
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| 5% Down, 5+ Flips1 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Honolulu comps say
Redfin puts the Honolulu median sale price at $615,000 for the three months ending August 2026, a figure pulled down by condos. The Honolulu Board of Realtors reports an Oahu single-family median of $1,240,000 for August 2026, up 12.2% from a year earlier, with single-family homes spending a median of 17 days on the market; the Oahu condo median was $510,000.
| Median sale price, Honolulu, all home types (Redfin, 3 months to Aug 2026) | $615,000 |
| Oahu single-family median sales price (HBR, Aug 2026) | $1,240,000 |
| Oahu condo median sales price (HBR, Aug 2026) | $510,000 |
| Oahu single-family median days on market (HBR, Aug 2026) | 17 |
Sources: Redfin, Honolulu housing market · Honolulu Board of Realtors, August 2026 market report
How a Honolulu file actually gets priced
Honolulu ARVs are set within tight valleys and ridges. Kaimuki, Palolo and Kalihi sit close together on a map and far apart in price, and ocean or mountain views move value more than square footage. We use recent single-family closings from the same area and the same construction type, and we keep condos out of a house file entirely. Leasehold sales are comped against leasehold, and a single-wall house is compared with single-wall houses, not with a remodeled post-and-beam home down the street.
Permits are the local risk that surprises everyone. The Department of Planning and Permitting has had long backlogs, so anything beyond cosmetic work can add months, and unpermitted additions are common in older Oahu houses. Cesspools are another line: state law requires them to be upgraded or converted over the coming decades, and a buyer may ask. Check flood and tsunami zone maps near the coast, and watch the short-term rental rules, since the city now requires much longer minimum stays outside resort areas.
Who buys your finished Honolulu deal
A finished Honolulu house sells to local families, military households from Pearl Harbor-Hickam and Schofield on VA loans, and buyers moving from the mainland. Single-family homes still move quickly on Oahu, and a lot of buyers want a separate ohana unit for extended family, which can add real value when it is permitted. Condos compete at lower prices but carry their own risks with association insurance and assessments. Renting is a fallback, but at these prices a DSCR loan needs strong rent to cover the payment.
Your whole loan, in one portal
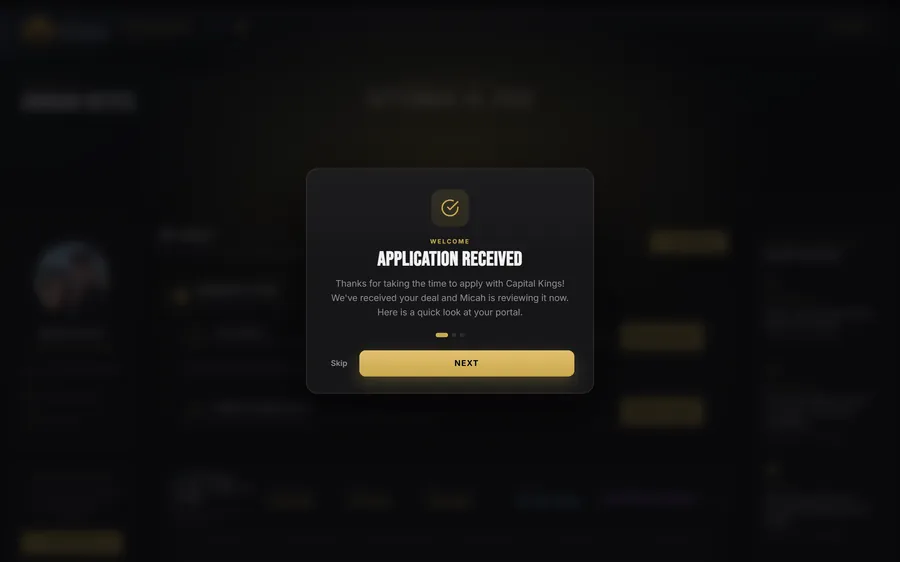
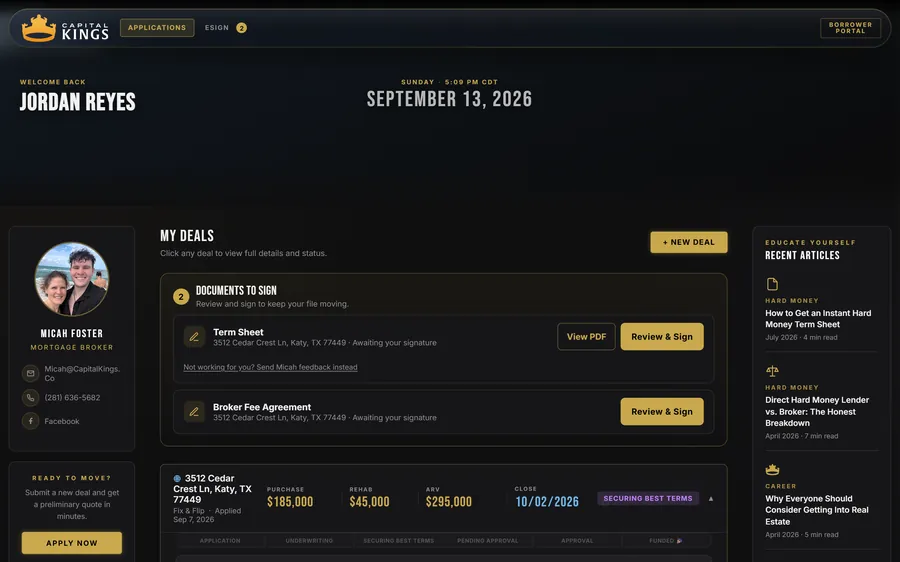
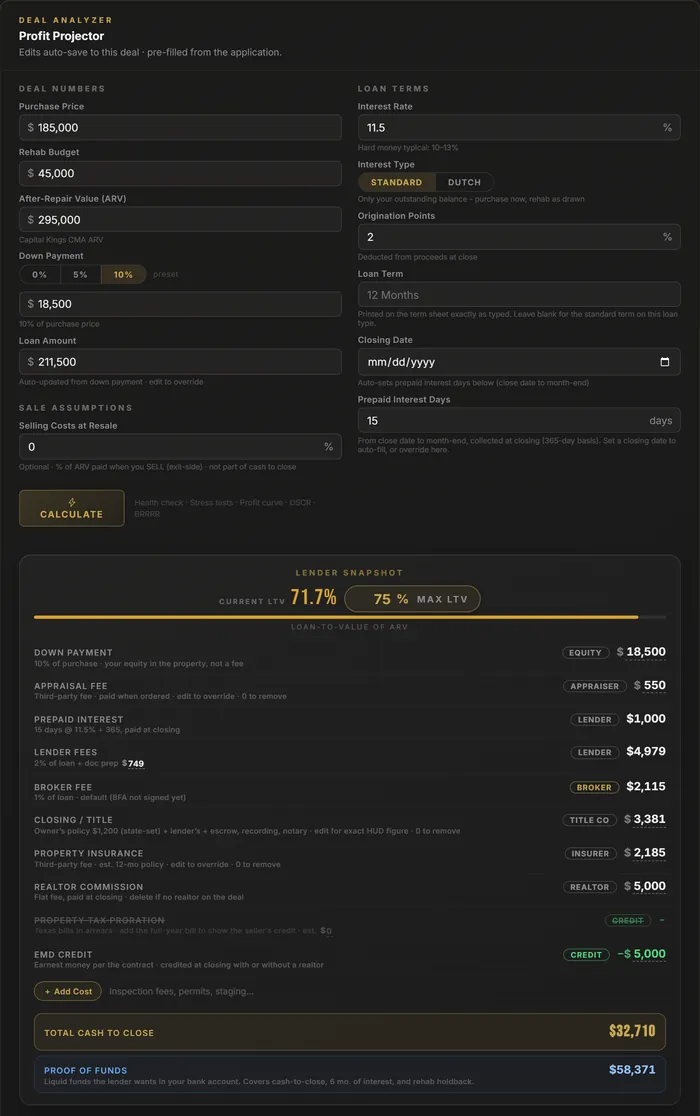
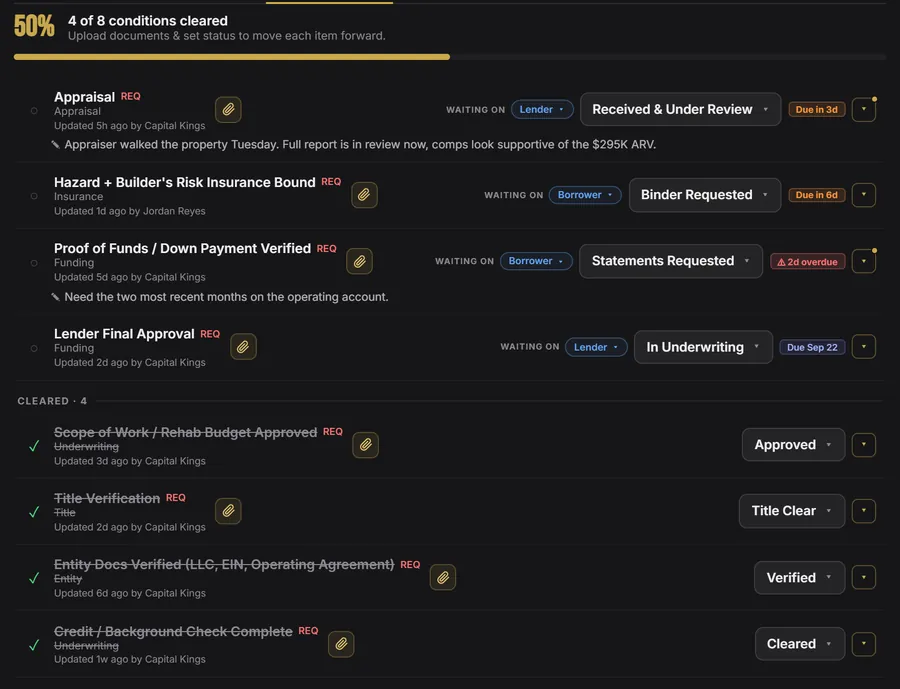
Apply once and the whole Honolulu loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Honolulu
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Honolulu.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Honolulu
We broker deals across the whole Honolulu market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Hawaii, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Honolulu hard money FAQ
Do you lend hard money in Honolulu?
Which fix and flip programs apply in Honolulu?
How fast can a Honolulu hard money loan close?
How much do I need to bring to close on a Honolulu flip?
Do you fund the rehab budget in Honolulu?
What credit score do I need for a Honolulu fix and flip loan?
Can I refinance a Honolulu flip into a rental loan?
Why do so many lenders avoid Hawaii?
Will a lender finance a leasehold house in Honolulu?

Ready to fund your Honolulu deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.