 Broker, not a lender
Hard Money Lenders inBaltimore, Maryland
Fix and flip, DSCR rental and new construction financing for Baltimore investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Baltimore deal right now
Prefilled with a realistic Baltimore deal. Change any number and it reprices instantly on the lanes licensed in Maryland, using the same engine behind our term sheets.
Financing a deal in Baltimore
Baltimore is a rowhouse city with some of the widest value gaps of any market on the East Coast. A renovated row in Canton or Hampden and a vacant shell a mile away can be worth wildly different amounts, and the flip lives in the neighborhoods in between: Belair-Edison, Hamilton, Highlandtown, Pigtown. Redfin has the city median up a little on a year ago with homes selling in about six weeks. The investors who do well here know the block, the permit history and the vacant building list.
The Baltimore deal starts with one question: does the house have a Vacant Building Notice? The city issues one to vacant or unsafe properties, and it stays until the house is rehabbed under permit and gets a use and occupancy permit. Sellers have to disclose it, and buyers of rehabbed homes are told to ask. A flip that skips permits can leave the notice in place and wreck the resale. We ask about the notice and the permit plan before we shop the file.
What a Baltimore deal looks like on paper
Baltimore example: $105,000 purchase, $70,000 rehab, $255,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Think a 1920s porch-front rowhouse in Belair-Edison: full gut of the kitchen and baths, new HVAC and electric, roof, and a use and occupancy permit at the end. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$15,750
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,123
- Prepaid interest (15 days)Lender$621
- Property insuranceInsurer$1,663
- AppraisalAppraiser$550
Interest while you rehab: $706 a month on the $89,250 funded at closing, $1,259 once every draw is out. Proof of funds is cash to close plus $18,900 of rehab reserve and $7,556 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Baltimore
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Baltimore comps say
Redfin puts the Baltimore median sale price at $245K for the last three months, up 2.0% on a year earlier, with homes selling in about 44 days. Zillow’s average Baltimore home value is $186,741 (updated 8/31/2026), down 3.4% on the year.
| Median sale price, Baltimore (Redfin, last 3 months) | $245,000 |
| Days on market, Baltimore (Redfin) | 44 |
| Zillow home value index, Baltimore (Aug 2026) | $186,741 |
Sources: Redfin, Baltimore housing market · Zillow, Baltimore home values · Baltimore City DHCD, Property Registration and Rental Licensing · Baltimore City DHCD, Buying a Rehabbed Home
How a Baltimore file actually gets priced
Baltimore ARVs are set block by block, and the appraiser wants renovated rows on the same or the next street, sold recently. A nicer neighborhood nearby isn’t a comp, even if it’s within a few blocks. We look for sales that closed with permits and a use and occupancy certificate, since that’s what the finished house will be judged against. Heavy rehab is normal here, often a full gut, so we want a detailed scope with the budget broken out by trade before a lender sees it.
Permits and inspections are the Baltimore risk. Any rental must be registered and licensed with the Department of Housing and Community Development, which requires a passing inspection by a state licensed home inspector registered with the city. Maryland also requires a lead inspection certificate on rentals built before 1978. On the building itself, plan for shared party walls, flat roofs, rear additions that settle, and old sewer lines to the alley.
Who buys your finished Baltimore deal
A renovated Baltimore rowhouse sells mostly to first-time buyers, many using FHA loans or city and state down payment help, and they and their lenders will look for the use and occupancy permit. Hampden, Remington and Highlandtown draw young professionals and hospital staff; Belair-Edison and Hamilton draw local families. The rental exit is also real. A well-rehabbed row can be licensed, leased and refinanced into a DSCR loan (a rental loan qualified on the rent, not your income).
Your whole loan, in one portal
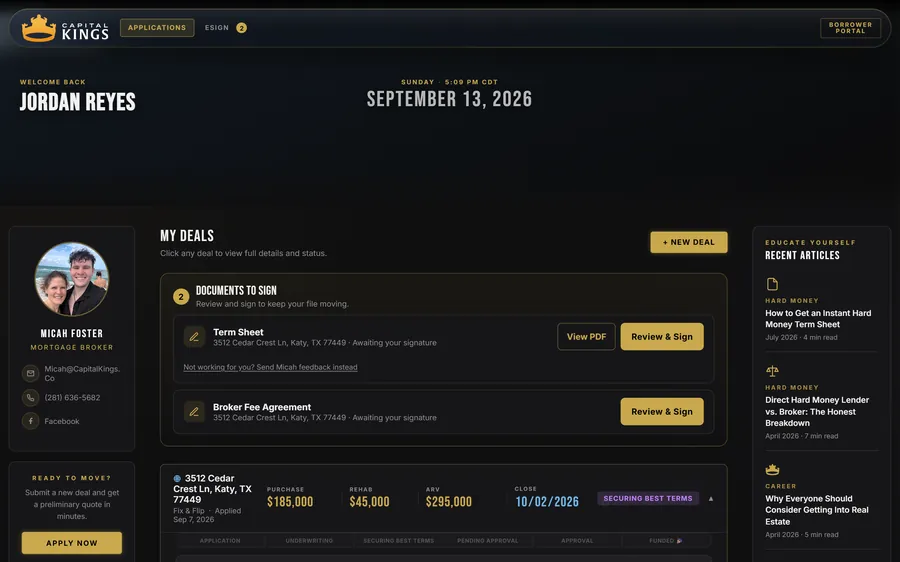
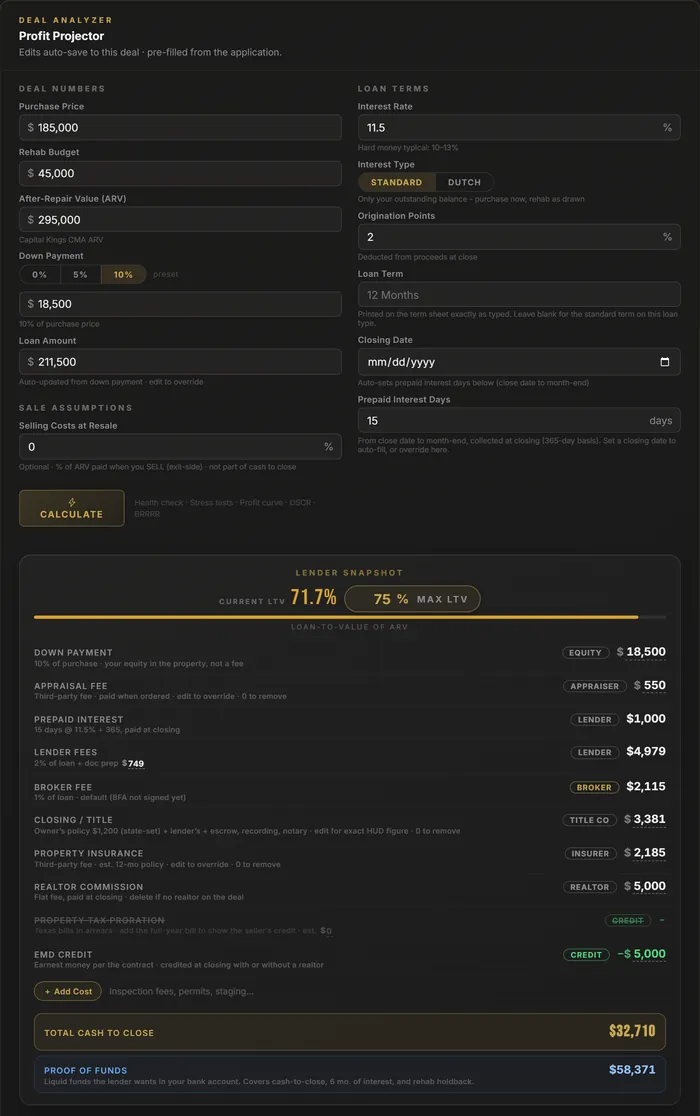
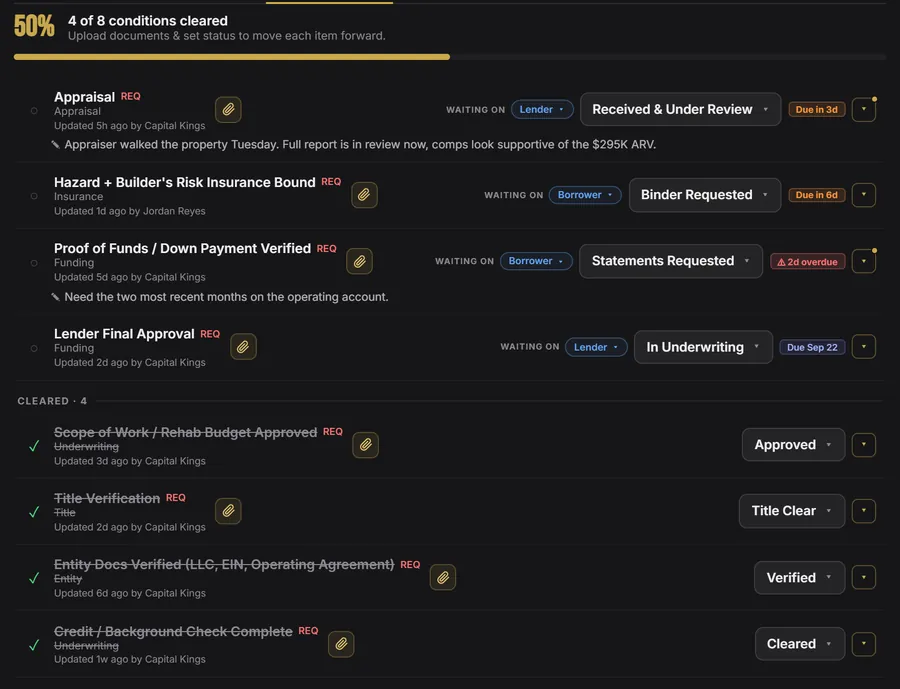
Apply once and the whole Baltimore loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Baltimore
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Baltimore.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Baltimore
We broker deals across the whole Baltimore market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Maryland, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Baltimore hard money FAQ
Do you lend hard money in Baltimore?
Which fix and flip programs apply in Baltimore?
How fast can a Baltimore hard money loan close?
How much do I need to bring to close on a Baltimore flip?
Do you fund the rehab budget in Baltimore?
What credit score do I need for a Baltimore fix and flip loan?
Can I refinance a Baltimore flip into a rental loan?
Can I get a hard money loan on a Baltimore house with a Vacant Building Notice?
Can I flip my first house in Baltimore with a hard money loan?

Before you sign anything
Ready to fund your Baltimore deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.