 Broker, not a lender
Hard Money Lenders inHartford, Connecticut
Fix and flip, DSCR rental and new construction financing for Hartford investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Hartford deal right now
Prefilled with a realistic Hartford deal. Change any number and it reprices instantly on the lanes licensed in Connecticut, using the same engine behind our term sheets.
Financing a deal in Hartford
Hartford is Connecticut’s capital and one of the cheapest places to buy a house in the state, sitting inside a county where the typical home is worth nearly twice as much. That gap is the opportunity. The city’s stock is old and solid: colonials and capes in Blue Hills, Victorians and Tudors in the West End, and the multifamily Hartford is known for, the stacked two family “perfect six” and the triple decker, filling the South End, Frog Hollow, Parkville and the North End.
A Hartford deal lives or dies on the block. Prices can change sharply across a single avenue, and a renovated house on the wrong street will sit while the same house four blocks over sells in a week. Buyers here are local, value driven and often using assistance programs, so the finish has to be durable rather than fancy. Most of the money in a Hartford rehab goes behind the walls: steam and hot water heat, old electrical service, galvanized supply lines, slate or asphalt roofs at the end of their life.
What a Hartford deal looks like on paper
Hartford example: $150,000 purchase, $55,000 rehab, $290,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1920s brick colonial in Blue Hills, vacant a couple of years, needing a boiler, a kitchen, two baths and plaster repair. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15%)You$22,500
- Origination (0.5%)Lender$2,000
- Doc prepLender$749
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,238
- Prepaid interest (15 days)Lender$712
- Property insuranceInsurer$1,948
- AppraisalAppraiser$550
Interest while you rehab: $1,008 a month on the $127,500 funded at closing, $1,443 once every draw is out. Proof of funds is cash to close plus $14,850 of rehab reserve and $8,660 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Hartford
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 75% of ARV | 12 months | 14 days |
| 5% Down, 3+ Flips1 | 5% | 600+ | 3+ completed flips | 11.00% to 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips2 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
- Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of September 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
What the Hartford comps say
Redfin puts the Hartford median sale price at $340,000 over the three months through August 2026, up 7.9% from a year earlier, with homes selling in about 37 days and 134 sales in August. Zillow’s typical home value for the city is $203,792 as of August 31, 2026, against $388,728 for Hartford County. The two measures differ because Redfin reports what actually sold while Zillow values every home, so price your own block, not the citywide number.
| Median sale price, Hartford (Redfin, 3 months to Aug 2026) | $340,000 |
| Days on market, Hartford (Redfin) | 37 |
| Homes sold in August 2026 (Redfin) | 134 |
| Zillow home value index, Hartford (Aug 2026) | $203,792 |
| Zillow home value index, Hartford County (Aug 2026) | $388,728 |
| Share of properties at severe 30-year flood risk (First Street via Redfin) | 9% |
Sources: Redfin, Hartford housing market · Zillow, Hartford home values · City of Hartford, apply for a rental license
How a Hartford file actually gets priced
Hartford values need close comps and patience. Fewer homes trade here than in the suburbs, so an appraiser may reach back several months or across a neighborhood line, and that is where values drift. We build the number from renovated sales on the same side of the city and the same building type, a single against singles and a two family against two families, and we treat a suburban West Hartford sale as irrelevant no matter how close it is on the map. For multifamily we want the market rent for each unit, because the income approach carries real weight here.
Hartford sits behind Connecticut River dikes, and the Park River that once ran through the city now runs underground in conduits, so most flooding is localized, and Redfin’s First Street data puts roughly one property in eleven at severe 30 year risk. Check the map near the river and the old Park River routes. The bigger local item is paperwork: Hartford requires a residential rental license with a city inspection for rental properties, so a flip that turns into a rental, or a two family sold to a landlord, has to be ready to pass. Pull permits through the city for anything beyond paint and floors, and plan on lead safe work in pre-1978 homes.
Who buys your finished Hartford deal
Finished Hartford singles sell mostly to first time owner occupants on FHA or Connecticut housing finance programs, which means the house must clear an FHA appraisal and its condition list. Renovated two and three family houses sell to owner occupants who use the rent to qualify and to small investors buying cash flow. Because the purchase prices are low and rents are real, a DSCR refinance is often the better ending here than a sale, and we price both before you close.
Your whole loan, in one portal
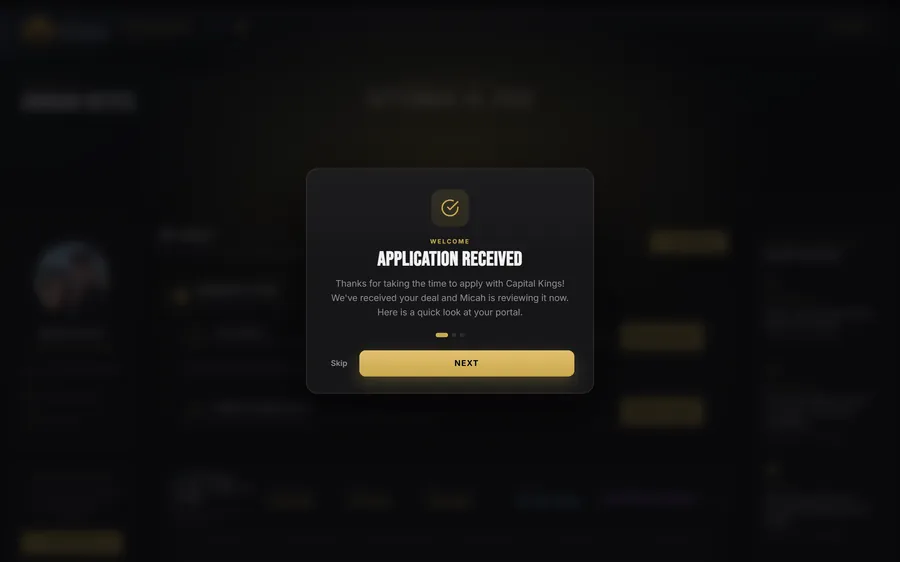
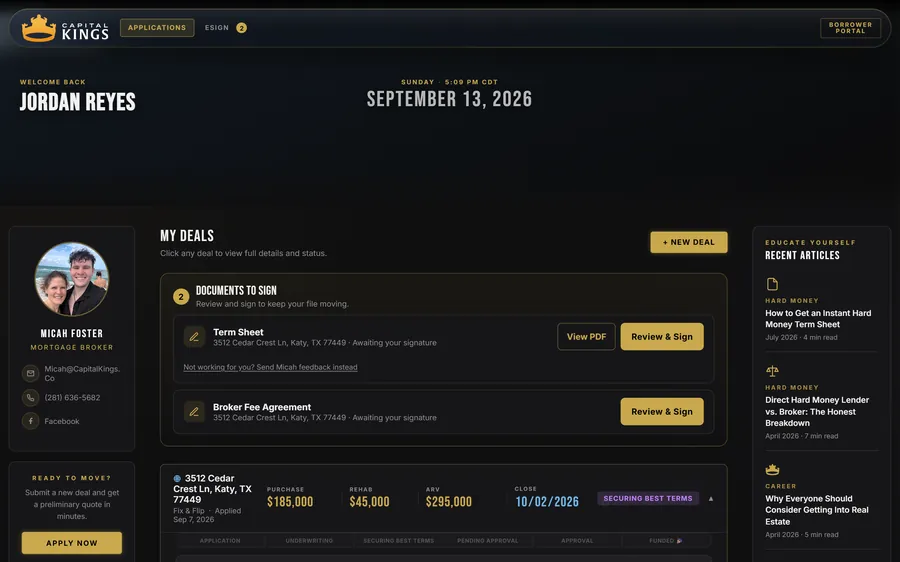
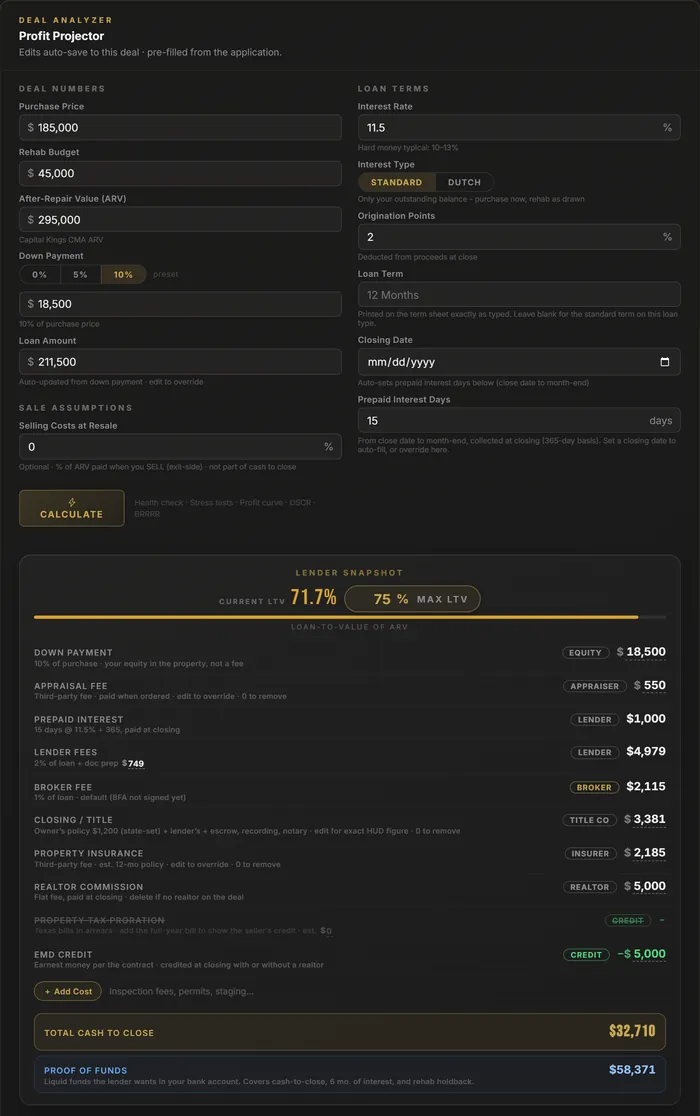
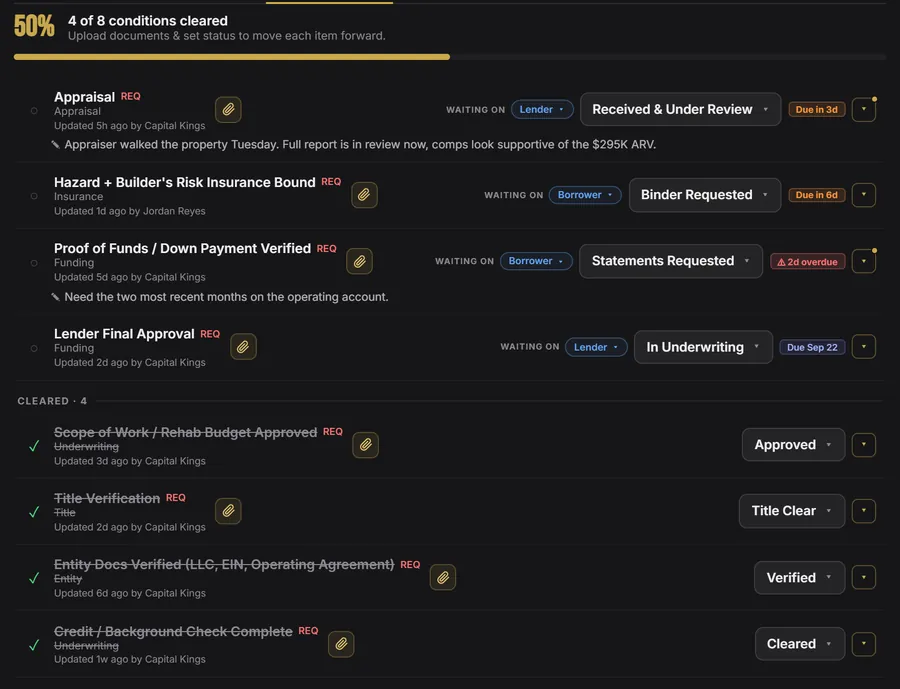
Apply once and the whole Hartford loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Hartford
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Hartford.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Hartford
We broker deals across the whole Hartford market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Connecticut, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
7 to 10 days typical. We stay on title and the lender through funding.
Hartford hard money FAQ
Do you lend hard money in Hartford?
Which fix and flip programs apply in Hartford?
How fast can a Hartford hard money loan close?
How much do I need to bring to close on a Hartford flip?
Do you fund the rehab budget in Hartford?
What credit score do I need for a Hartford fix and flip loan?
Can I refinance a Hartford flip into a rental loan?
Do I need a rental license if my Hartford flip becomes a rental?
Is Hartford a first flip friendly market?

Before you sign anything
Ready to fund your Hartford deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.