 Broker, not a lender
Hard Money Lenders inCranston, Rhode Island
Fix and flip, DSCR rental and new construction financing for Cranston investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price a Cranston deal right now
Prefilled with a realistic Cranston deal. Change any number and it reprices instantly on the lanes licensed in Rhode Island, using the same engine behind our term sheets.
Financing a deal in Cranston
Cranston borders Providence to the south and west and runs from dense, older neighborhoods by the city line out to farmland. Edgewood, near Roger Williams Park and the bay, has Colonial Revival homes and bungalows from the early 1900s. Eden Park, Auburn, Arlington and Knightsville are capes, colonials and small multifamily from the 1920s through the 1950s, Garden City is midcentury, and western Cranston has newer homes on larger lots.
Cranston is a steady family market where a well finished house sells. The east side neighborhoods by Providence are the core flip inventory: solid older homes from long time owners that need heat, wiring, kitchens and baths. Western Cranston is a different business, with bigger homes and higher price points. Buyers here pay for space, so adding a bath or finishing a basement often matters more than a premium finish.
What a Cranston deal looks like on paper
Cranston example: $330,000 purchase, $75,000 rehab, $560,000 after repair value, 730 credit, first flip. The engine puts that borrower on the First Flip, 10% Down program at 9.99%. Picture a 1940s Eden Park cape with a hot water boiler near the end, plaster walls, one bath upstairs and a basement that could be finished. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (10% of purchase plus rehab)You$40,500
- Origination (2.13%)Lender$7,746
- Lender fees (flat)Lender$2,790
- Broker fee (1%)Broker$3,645
- Title and closing (estimate at Texas rates)Title$4,137
- Prepaid interest (15 days)Lender$1,496
- Property insuranceInsurer$3,848
- AppraisalAppraiser$550
Interest while you rehab: $2,410 a month on the $289,500 funded at closing, $3,034 once every draw is out. Proof of funds is cash to close plus $18,750 of rehab reserve and $18,207 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Cranston
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Experienced Investor Rate1 | 15% | 680+ | 2+ completed flips | 9.00% | 0.75% | 75% of ARV | 12-24 months | 7-14 days |
| First Flip, 10% Down2 | 10% | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips3 | 7.5% | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 3+ Flips4 | 5% | 600+ | 3+ completed flips | 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips5 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips6 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
- Rate and origination are the program floor; two completed projects in the last 36 months preferred.
- Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate from 12%, set per file. Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% and 2 to 3 points, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Cranston prices sit right now
Before we price a Cranston flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Cranston median sale price at $500,000 over the three months through September 2026, up 4.0% from a year earlier, with homes selling in about 28 days and 233 sales in September.
| Median sale price, Cranston (Redfin, 3 months to Sep 2026) | $500,000 |
| Days on market, Cranston (Redfin) | 28 |
| Homes sold in September 2026 (Redfin) | 233 |
| Share of properties at severe 30-year flood risk (First Street via Redfin) | 4% |
Sources: Redfin, Cranston RI housing market
How a Cranston file actually gets priced
Cranston has steady sales across its neighborhoods, so comps are rarely the problem; mixing them is. Edgewood and western Cranston price well above Eden Park and Knightsville, and Providence sales just over the line do not carry a Cranston value. We comp within the same neighborhood and style. Prices rose over the year while price per square foot slipped, so a bigger, updated house is what the market rewards.
Redfin’s First Street data puts about 4% of Cranston properties at severe 30 year flood risk, mostly along the Pawtuxet River and Pocasset River, where the 2010 flood did real damage, and the bay edge in Edgewood. Check those streets. Pre-1978 homes are the norm in eastern Cranston, so plan lead safe work, and Rhode Island requires a lead certificate on most older rental units. Pull permits through the city for anything structural, electrical or mechanical.
Who buys your finished Cranston deal
The finished Cranston house sells to Rhode Island families moving up, Providence workers who want a yard, and first time buyers on FHA or state programs in the lower price neighborhoods. They want updated systems, a good kitchen and enough bathrooms. Small multifamily in Knightsville and near the Providence line sells to owner occupants and landlords, and a DSCR refinance works as a hold.
Your whole loan, in one portal
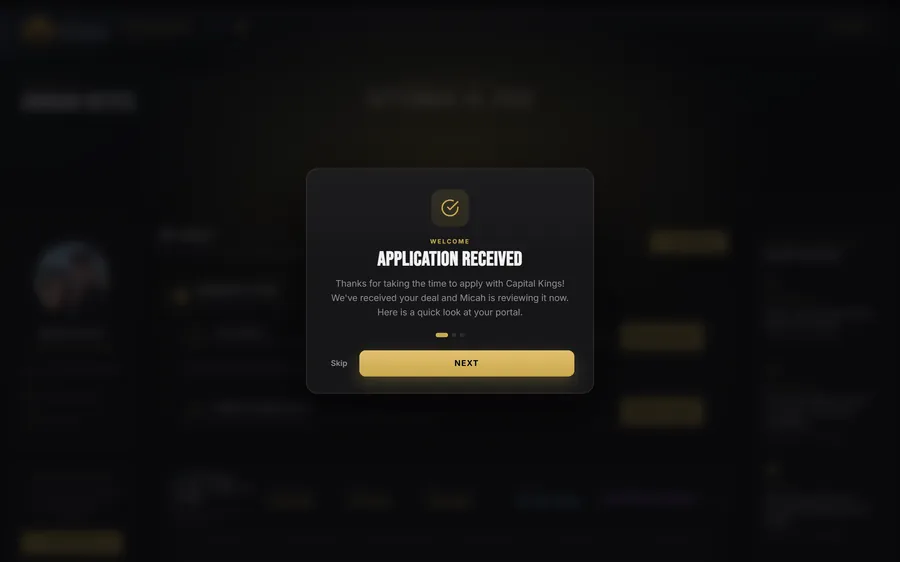
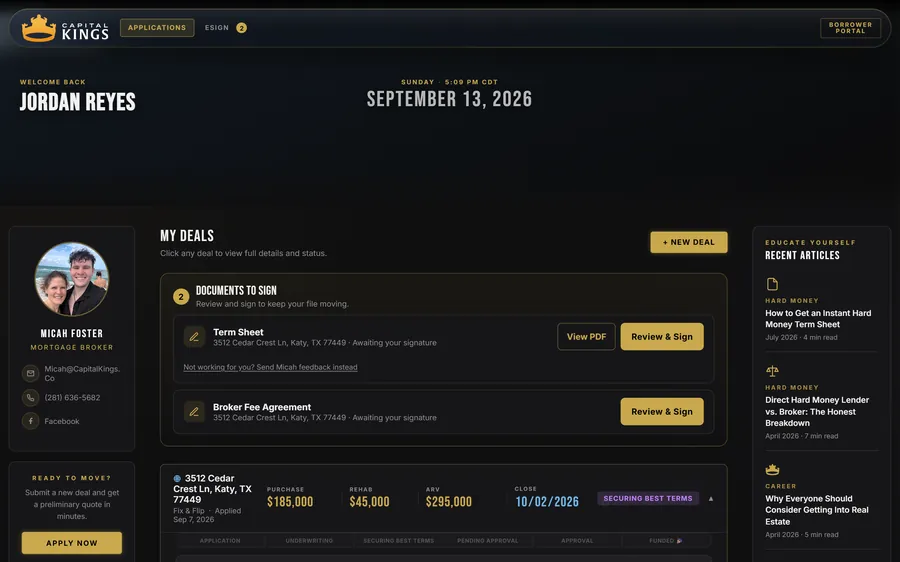
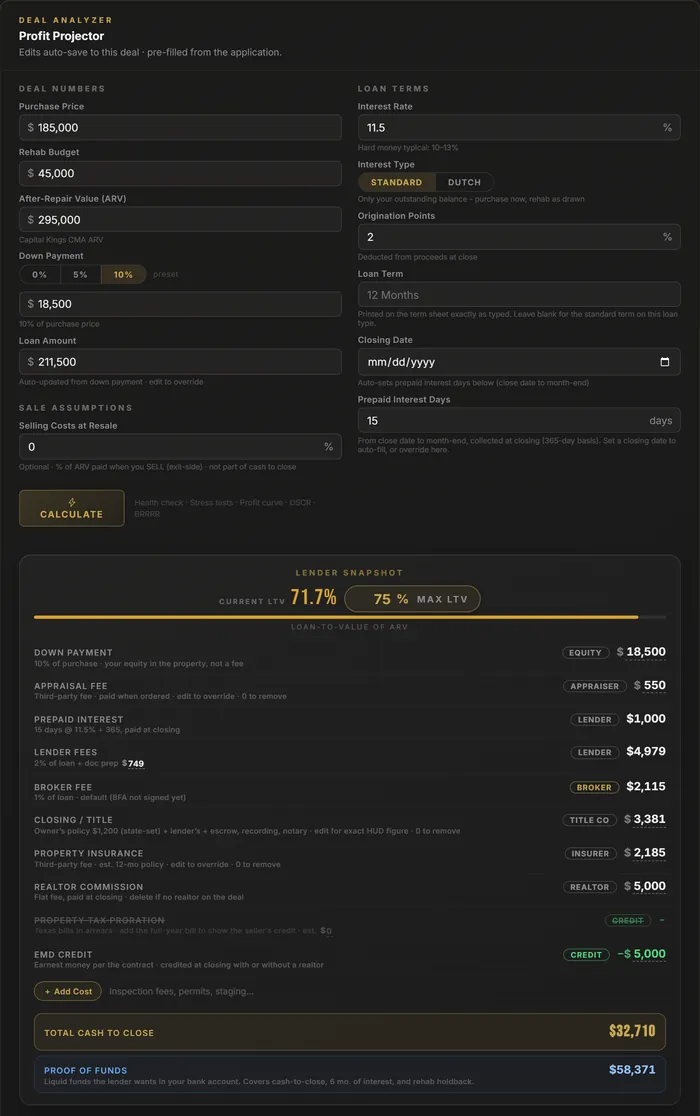
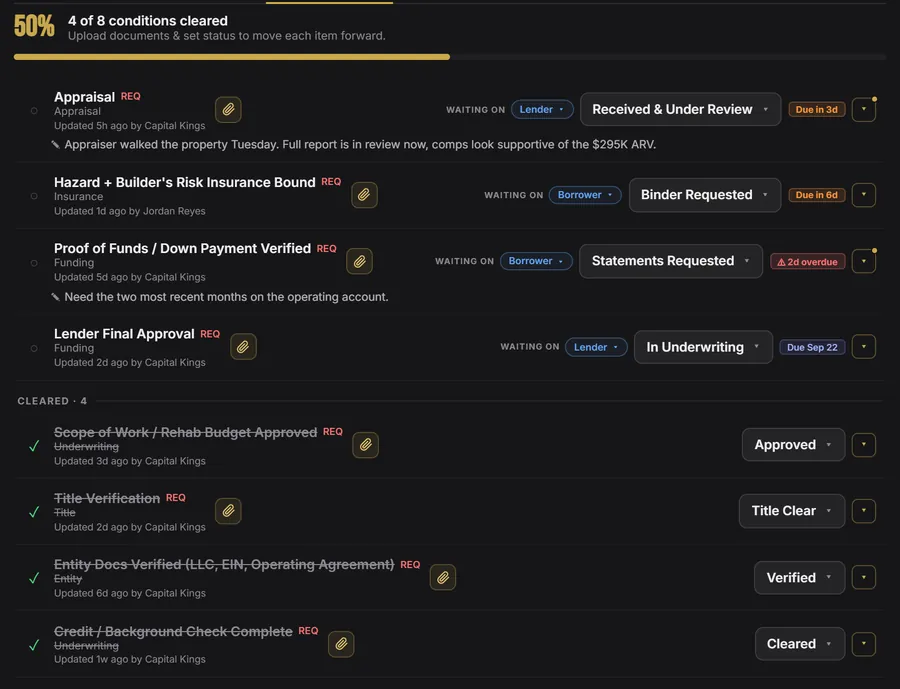
Apply once and the whole Cranston loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Cranston
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Cranston.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Cranston
We broker deals across the whole Cranston market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. Three minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Rhode Island, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
Plan on 7-14 days with completed flips and 21-30 days on a first flip. We stay on title and the lender through funding.
Cranston hard money FAQ
Do you lend hard money in Cranston?
Which fix and flip programs apply in Cranston?
How fast can a Cranston hard money loan close?
How much do I need to bring to close on a Cranston flip?
Do you fund the rehab budget in Cranston?
What credit score do I need for a Cranston fix and flip loan?
Can I refinance a Cranston flip into a rental loan?
Can I finance my first flip in Cranston?
How fast do Cranston homes sell?

Before you sign anything
Ready to fund your Cranston deal?
Submit your scenario in under 3 minutes. We shop it and come back with real terms, not a generic rate sheet.