 Broker, not a lender
Hard Money Lenders inAlpharetta, Georgia
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Alpharetta investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
What you get working with us
Price an Alpharetta deal right now
Prefilled with a realistic Alpharetta deal. Change any number and it reprices on the programs that lend in Georgia, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Alpharetta
Alpharetta is the north end of the GA 400 corridor, home to corporate campuses along Windward Parkway, Avalon and a downtown that has been rebuilt around City Center. Families move here for the Fulton County schools, so the housing is mostly 1980s and 1990s two-story subdivision homes with swim and tennis amenities. The typical flip is a dated, well-located house that needs a 2026 kitchen and baths, not a gut job.
In Alpharetta the school attendance zone and the subdivision name do most of the pricing. Two similar houses a mile apart can sell well apart if they feed different high schools. Buy inside a strong zone, keep the scope to what buyers in that subdivision expect, and price against closed sales on the same streets. Redfin has the median flat on a year earlier, so this is not a market that bails out an overpriced resale.
What an Alpharetta deal looks like on paper
Alpharetta example: $470,000 purchase, $90,000 rehab, $780,000 after repair value, 730 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1990s two-story in a swim and tennis neighborhood: the original kitchen and baths replaced, builder brass and carpet gone, new paint and a full exterior inspection. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$70,500
- Origination (0.5%)Lender$2,448
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$4,895
- Title and closing (estimate at Texas rates)Title$4,754
- Prepaid interest (15 days)Lender$1,558
- Property insuranceInsurer$5,320
- AppraisalAppraiser$550
Interest while you rehab: $3,159 a month on the $399,500 funded at closing, $3,871 once every draw is out. Proof of funds is cash to close plus $22,500 of rehab reserve and $23,227 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
What we can fund in Alpharetta
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| New Investor Program | 12.5% | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| First Flip, 10% Down1 | 10% | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 3+ Flips3 | 5% | 600+ | 3+ completed flips | 12.00% | 2% | 75% of ARV | 12 months | 7-14 days |
| 5% Down, 5+ Flips4 | 5% | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips5 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
| Fastest Close (3 days) | 10% | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% at 2 to 2.25 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% at 1.5 to 1.75 points by credit; buy down to 8.99%. Loans under $150,000 add 0.5% to the rate and half a point, under $100,000 1.5% and a point. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate from 12%, set per file. Origination steps down with experience: 1.5% at 5+ deals, 1% at 8+.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% and 2 to 3 points, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on every program and the broker fee is 1% with a $2,000 minimum. These are the numbers the instant term sheet uses as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Alpharetta prices sit right now
Before we price an Alpharetta flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Alpharetta median sale price at $750K for the three months ending September 2026, essentially flat from a year earlier, with homes selling after about 50 days on the market, compared with 41 days a year earlier.
| Median sale price, Alpharetta (Redfin, 3 months to Sep 2026) | $750K |
| Days on market, Alpharetta (Redfin) | 50 |
| Year over year change in median (Redfin) | Flat (0.0%) |
Sources: Redfin, Alpharetta housing market
How an Alpharetta file actually gets priced
Loan sizes here run larger than in most of Georgia, and lenders look harder at the ARV when they do. Appraisers stay within the subdivision and school zone and lean on recent closed sales of renovated houses. We send the file with the scope, before and after photos of similar flips nearby and the comps we expect, so the appraiser sees the finish level you are building to.
A lot of north Fulton houses from this era were built with synthetic stucco (EIFS) or hardcoat stucco, and trapped moisture behind it is the costly surprise. Get a stucco inspection before you close. Some homes from the late 1970s to mid 1990s still have polybutylene supply lines, which insurers and buyers flag. Most neighborhoods have an HOA with an architectural review for exterior changes, and the city regulates tree removal, so check before you clear a lot or widen a driveway.
Who buys your finished Alpharetta deal
The finished house sells to a relocating corporate family or a local family moving up within the school zone, usually with conventional or jumbo financing and a sharp inspector. They want an open kitchen, updated primary bath, fresh paint and a clean inspection report. Rent demand is strong from the same corporate workforce, so a DSCR hold is realistic, but the purchase price means you need a strong rent to cover the payment.
Your whole loan, in one portal
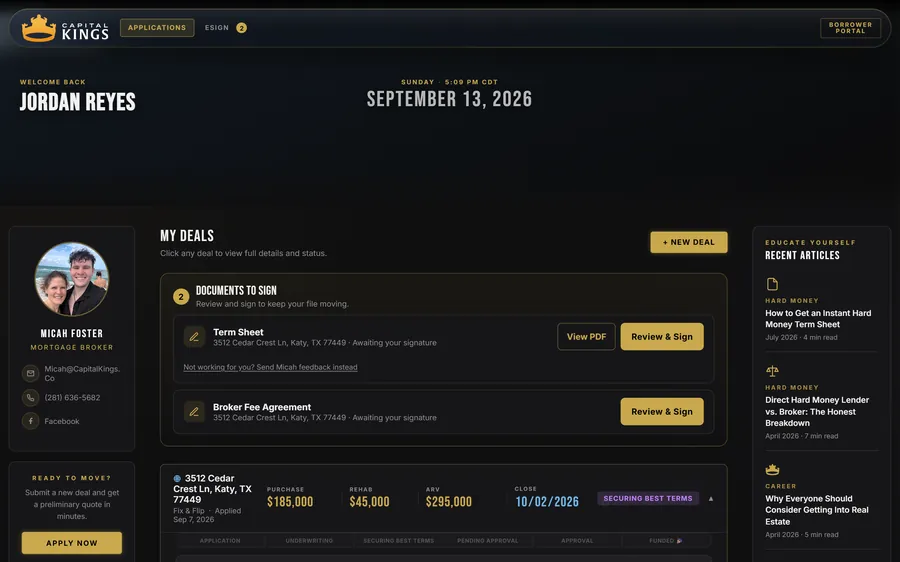
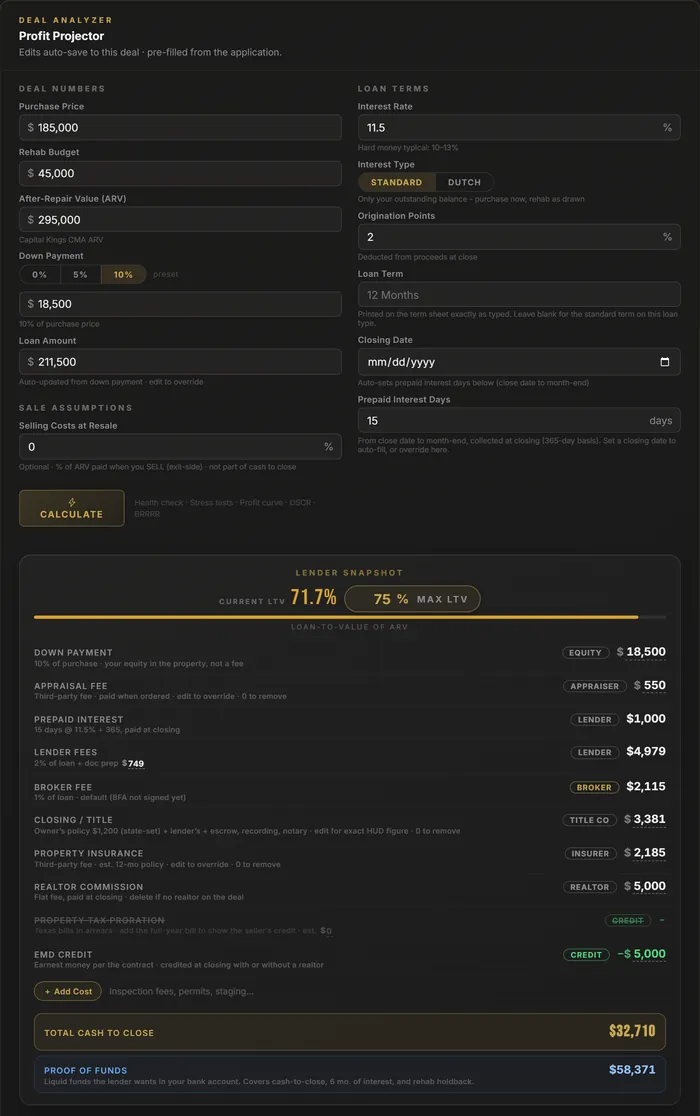
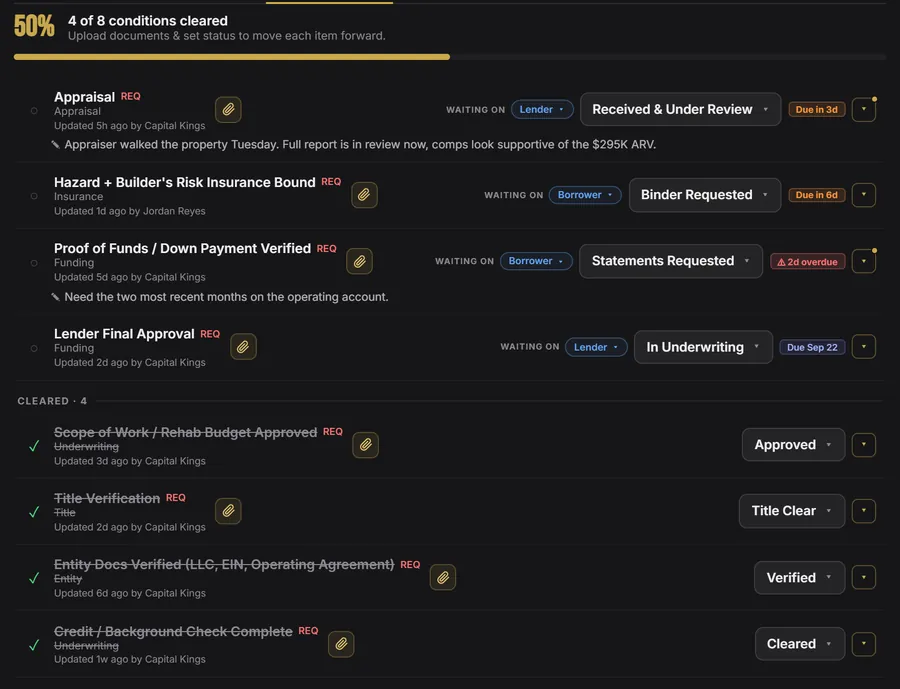
Apply once and the whole Alpharetta loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
What we fund in Alpharetta
Fix & Flip
Purchase plus 100% of rehab, released in draws. The core product in Alpharetta.
DSCR Rental
Qualifies on the property’s rent, not your W-2. The usual exit when a flip becomes a hold, and the long-term financing on a BRRRR.
Bridge & Purchase Only
For clean properties that need speed rather than rehab money. Auction buys, off-market deals, and 1031 timing.
New Construction
Ground-up for builders and infill developers, with a draw schedule matched to the build timeline.
Where we lend in Alpharetta
We broker deals across the whole Alpharetta market. These are the submarkets investors ask us about most:
From deal to funded
Send the deal
Address, purchase price, rehab budget and your ARV. About five minutes, no credit pull.
We shop it
Your scenario goes to the lenders in our network that actually fit it and are licensed in Georgia, not all 400 at once.
Real terms back
Rate, origination, leverage and cash to close side by side, so you can compare on total cost.
Close
5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Alpharetta hard money FAQ
Do you lend hard money in Alpharetta?
Which fix and flip programs apply in Alpharetta?
How fast can an Alpharetta hard money loan close?
How much do I need to bring to close on an Alpharetta flip?
Do you fund the rehab budget in Alpharetta?
What credit score do I need for an Alpharetta fix and flip loan?
Can I refinance an Alpharetta flip into a rental loan?
Who are the hard money lenders for Alpharetta flips?
Do I need a stucco inspection on an Alpharetta flip?
Before you sign anything
More Georgia city guides
Ready to fund your Alpharetta deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.